

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Harbor House Collective is stocked at 151 licensed dispensaries across Massachusetts, with the deepest coverage in Worcester, Boston, Fall River, Brockton, and Framingham. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
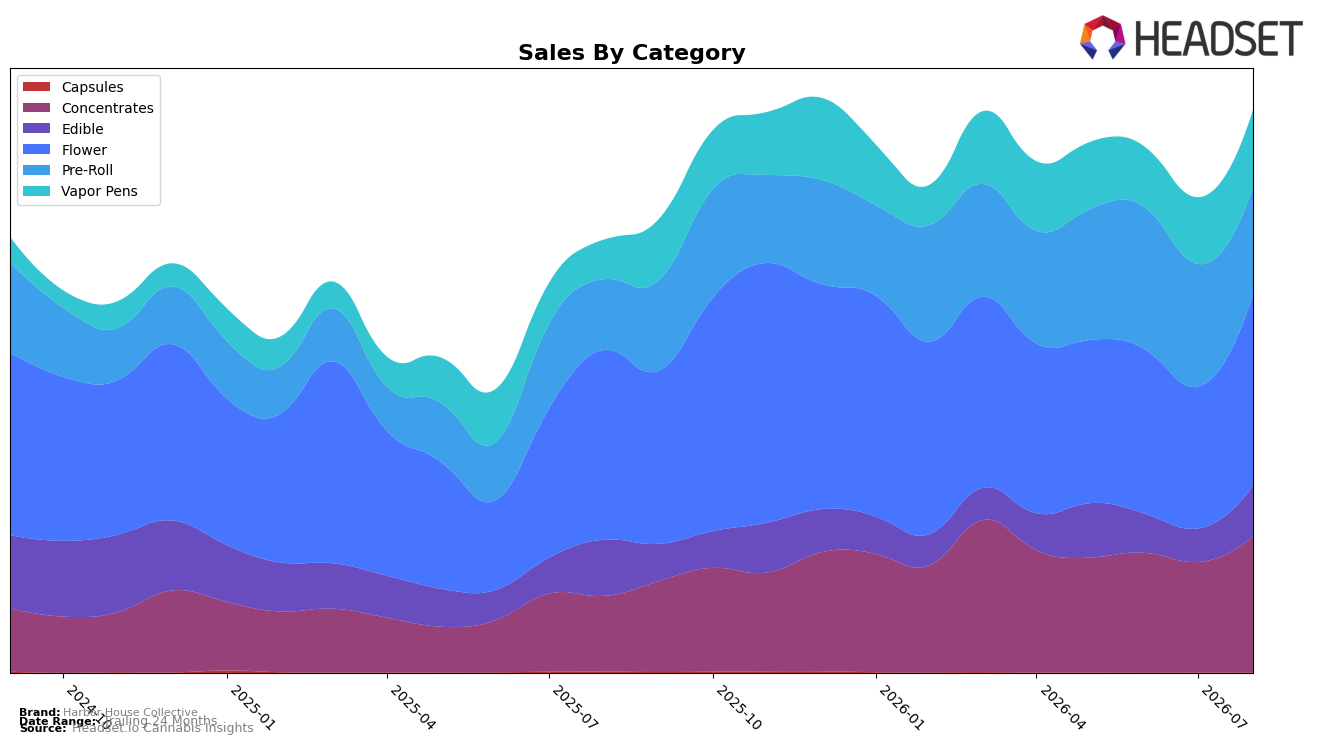
In August 2026, Harbor House Collective’s mix tilted toward Flower at 34.04% share with 35.38% month-over-month growth but only 1.35% year-over-year, while Pre-Roll slipped to 18.92% share with -12.66% MoM despite 50.81% YoY. Concentrates climbed to 24.17% share with 23.63% MoM and 80.19% YoY, and Vapor Pens reached 13.76% share with 16.26% MoM and 95.74% YoY, as Edible lifted 50.57% MoM despite -9.81% YoY to 8.97% share; Capsules remained marginal at 0.14% share with -49.27% YoY and 4.60% MoM. The pattern implies Harbor House Collective is redistributing growth from Pre-Roll into higher-velocity inhalables—Concentrates and Vapor Pens—while Flower’s surge is recent rather than longitudinal, and Edible’s spike appears promotional given the brand’s average price of $16.93 alongside an 18.54% price decline year over year.
These shifts position Harbor House Collective to lean into inhalable depth where double-digit MoM in Flower (35.38%) and Vapor Pens (16.26%) coincides with outsized YoY in Concentrates (80.19%) and Vapor Pens (95.74%), supporting scale moves in Massachusetts despite a Flower category rank of 43. The mix suggests an efficiency trade-off: near-term share capture in Concentrates and Vapor Pens could offset Pre-Roll volatility (-12.66% MoM) while Flower acts as a traffic anchor, but sustained positioning will depend on converting August 2026 MoM lifts into durable share without further average price compression after an 18.54% YoY decline.
Competitive Landscape
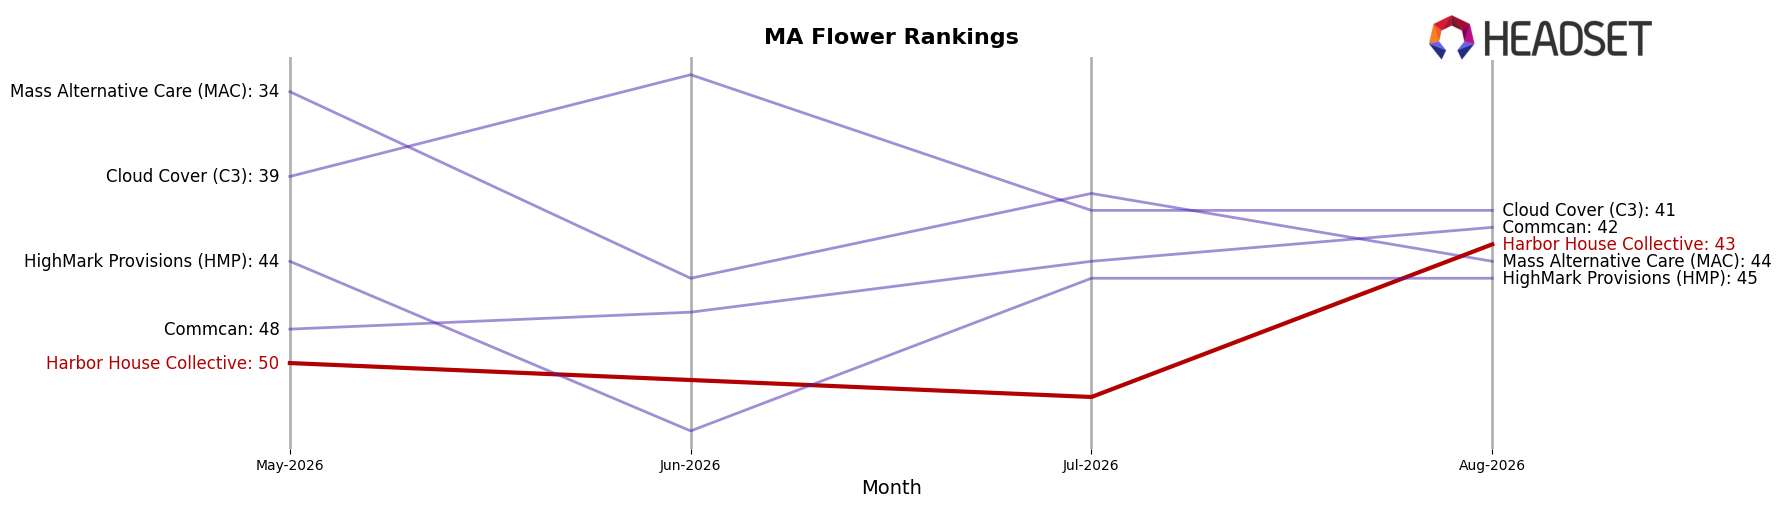
Harbor House Collective ranks #43 in Massachusetts Flower for August 2026, improving 4 positions year over year from #47 while climbing 7 spots since May 2026 from #50, yet still sits 15 places below its peak at #28 from November 2025. In contrast, Perpetual Harvest moved from #4 to #1 with a 51.9% year-over-year sales increase, and Root & Bloom advanced from #9 to #5 on 50.6% growth, indicating that Harbor House Collective’s modest rank gains are lagging leaders that are accelerating faster; this trajectory implies Harbor House Collective is stabilizing but not closing the competitive gap without a sharper share or velocity shift.
Notable Products
Sour Tangie Pre-Roll (1g) posted the steepest decline at -6.6% month over month, slipping to rank 5, while Aspen OG Pre-Roll (1g) rose 12.5% to rank 8. TKO (3.5g) gained 47.4% MoM at rank 6, and Grape Cream Cake (3.5g) added 10.2% MoM at rank 10. Six of the top ten are Pre-Rolls, anchored by Durban Poison Pre-Roll (1g) at rank 2 and Garlic Drip Pre-Roll (0.5g) at rank 3, indicating assortment weight sits in value-sized combustion rather than premium eighths despite Fire As Fuck (3.5g) leading at rank 1 with $32,478.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

