

California Sales Growth Returns After 50 Months: What's Behind It

Introduction
As the largest legal cannabis market in the world, the industry looks to California to spot emerging trends and new tastes. Since 2021, the story has revolved around shrinking demand, price compression, and market consolidation, with sales declining roughly 6% year over year for much of that stretch. In 2026, however, California's sales growth is essentially flat through eight months. In fact, every month since May has posted positive year-over-year growth. This is the first time this has happened since February 2022, ending 50 straight months of decline with four consecutive months in the green.
While encouraging, and to some extent genuinely positive, California still faces significant headwinds in turning this into a long-term trend. Beyond perennial hurdles like a high tax burden and illicit market competition, continued price compression in certain categories and aggressive retailer discounting remain real concerns for the industry's growth. Still, while caution is warranted, the real wins and opportunities shouldn't be ignored. The reality is that falling prices have meaningfully boosted unit volumes, enough to buoy sales in certain categories and formats for the time being.
In this report, we take a close look at the state of the California market: its current conditions, the clear areas of opportunity, and some potential future red flags. When one door closes, another opens, and the operators quickest to react to shifting trends are the ones who stand to benefit most.
Methodology
Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset's business intelligence software. Headset's data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider.
This report examines sales from US Headset Insights markets, including AZ, CA, CO, CT, IL, MA, MD, MI, MO, NJ, NV, NY, OH, OR, and WA. All figures are in USD. Year-over-year comparisons use January 1 through August 31 of each year so that 2026's partial-year data compares on a like-for-like basis. Basket-level metrics and package size detail are available from 2024 forward.
Key Takeaways
- California has found its first real sales growth in years. The state previously experienced fifty straight months of year-over-year decline, a streak that was finally broken in May, with sales posting positive year-over-year results for four consecutive months.
- California leads mature markets in both dollar (-0.1%) and unit (+4%) growth.
- The turn is volume, not price. Gross sales grew 3.5% through August, but a discount rate that climbed from 20.3% to 23.1% pulled net sales back to flat.
- Vapor Pens, nearly 30% of the market, found a price floor: deflation slowed from 11.9% to 2.9% year over year, and that alone accounts for most of the category holding steady.
- Growth is concentrated in beverage, pre-roll, and disposable vapor pens, the same categories where Gen Z, the only generation adding dollars this year, is over-indexed and accelerating.
- Flower is the drag. Per-gram price is down 18% since 2024, largely because consumers are trading up to cheaper 7g and 14g formats rather than the category losing value outright.
- Discounting is the risk to watch. California still discounts less than most peers, but the rate is rising faster than most of them, meaning some of the volume recovery is being bought rather than earned.
- The shelf is consolidating (207 brands exited this past year) and market share is flowing to well-positioned products within establish California brand.
The Turn
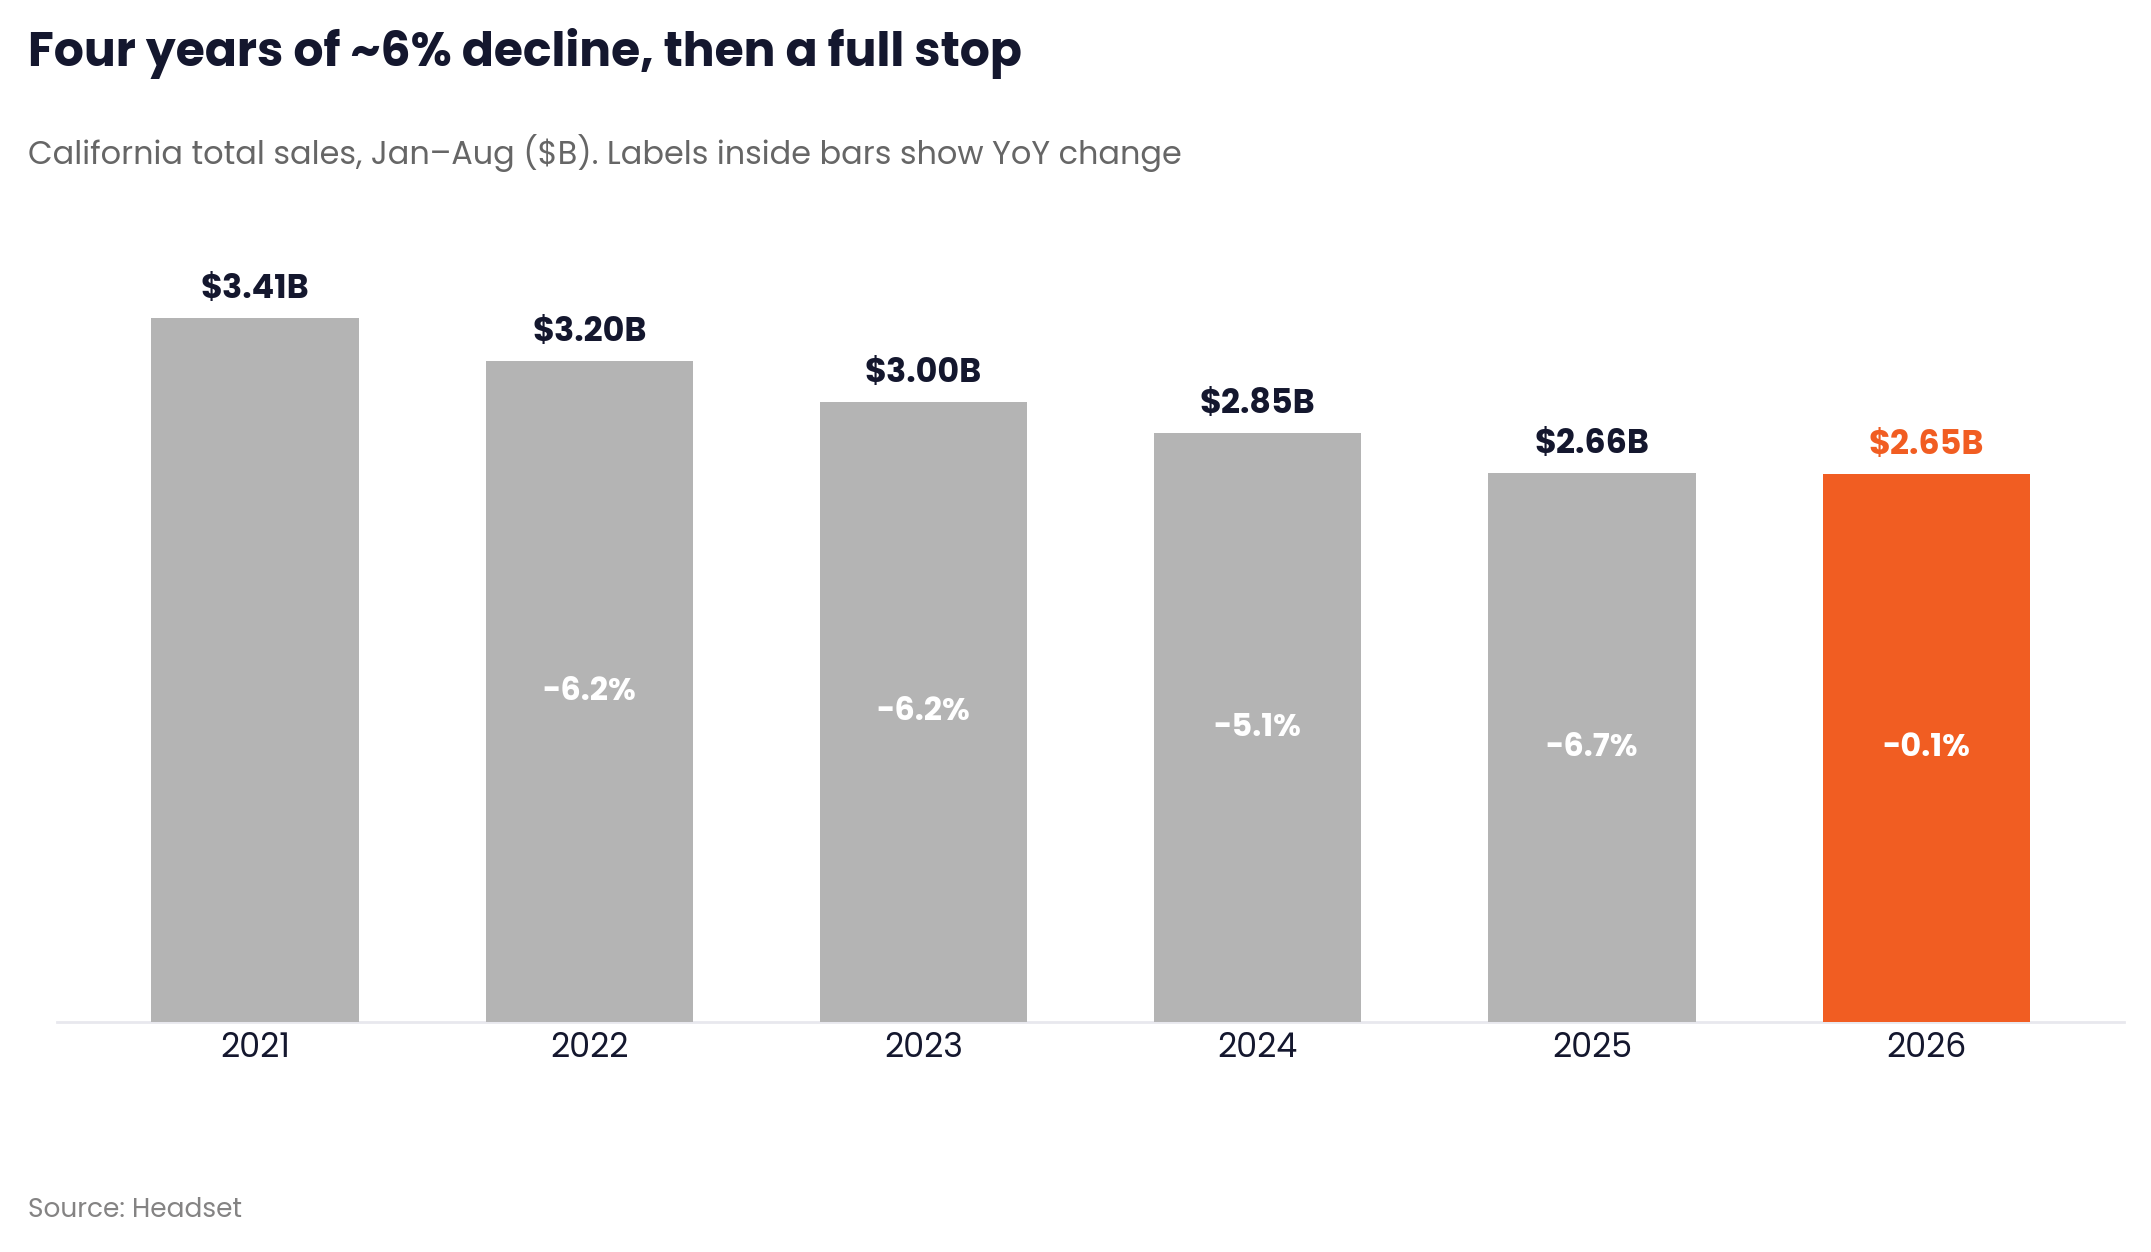
California gave back $753M of January-through-August sales between 2021 and 2025, a 22.1% contraction. Four years, four declines, all of them within a point and a half of each other. Then 2026 landed within a few million of the 2025 total, a difference of 0.1%.
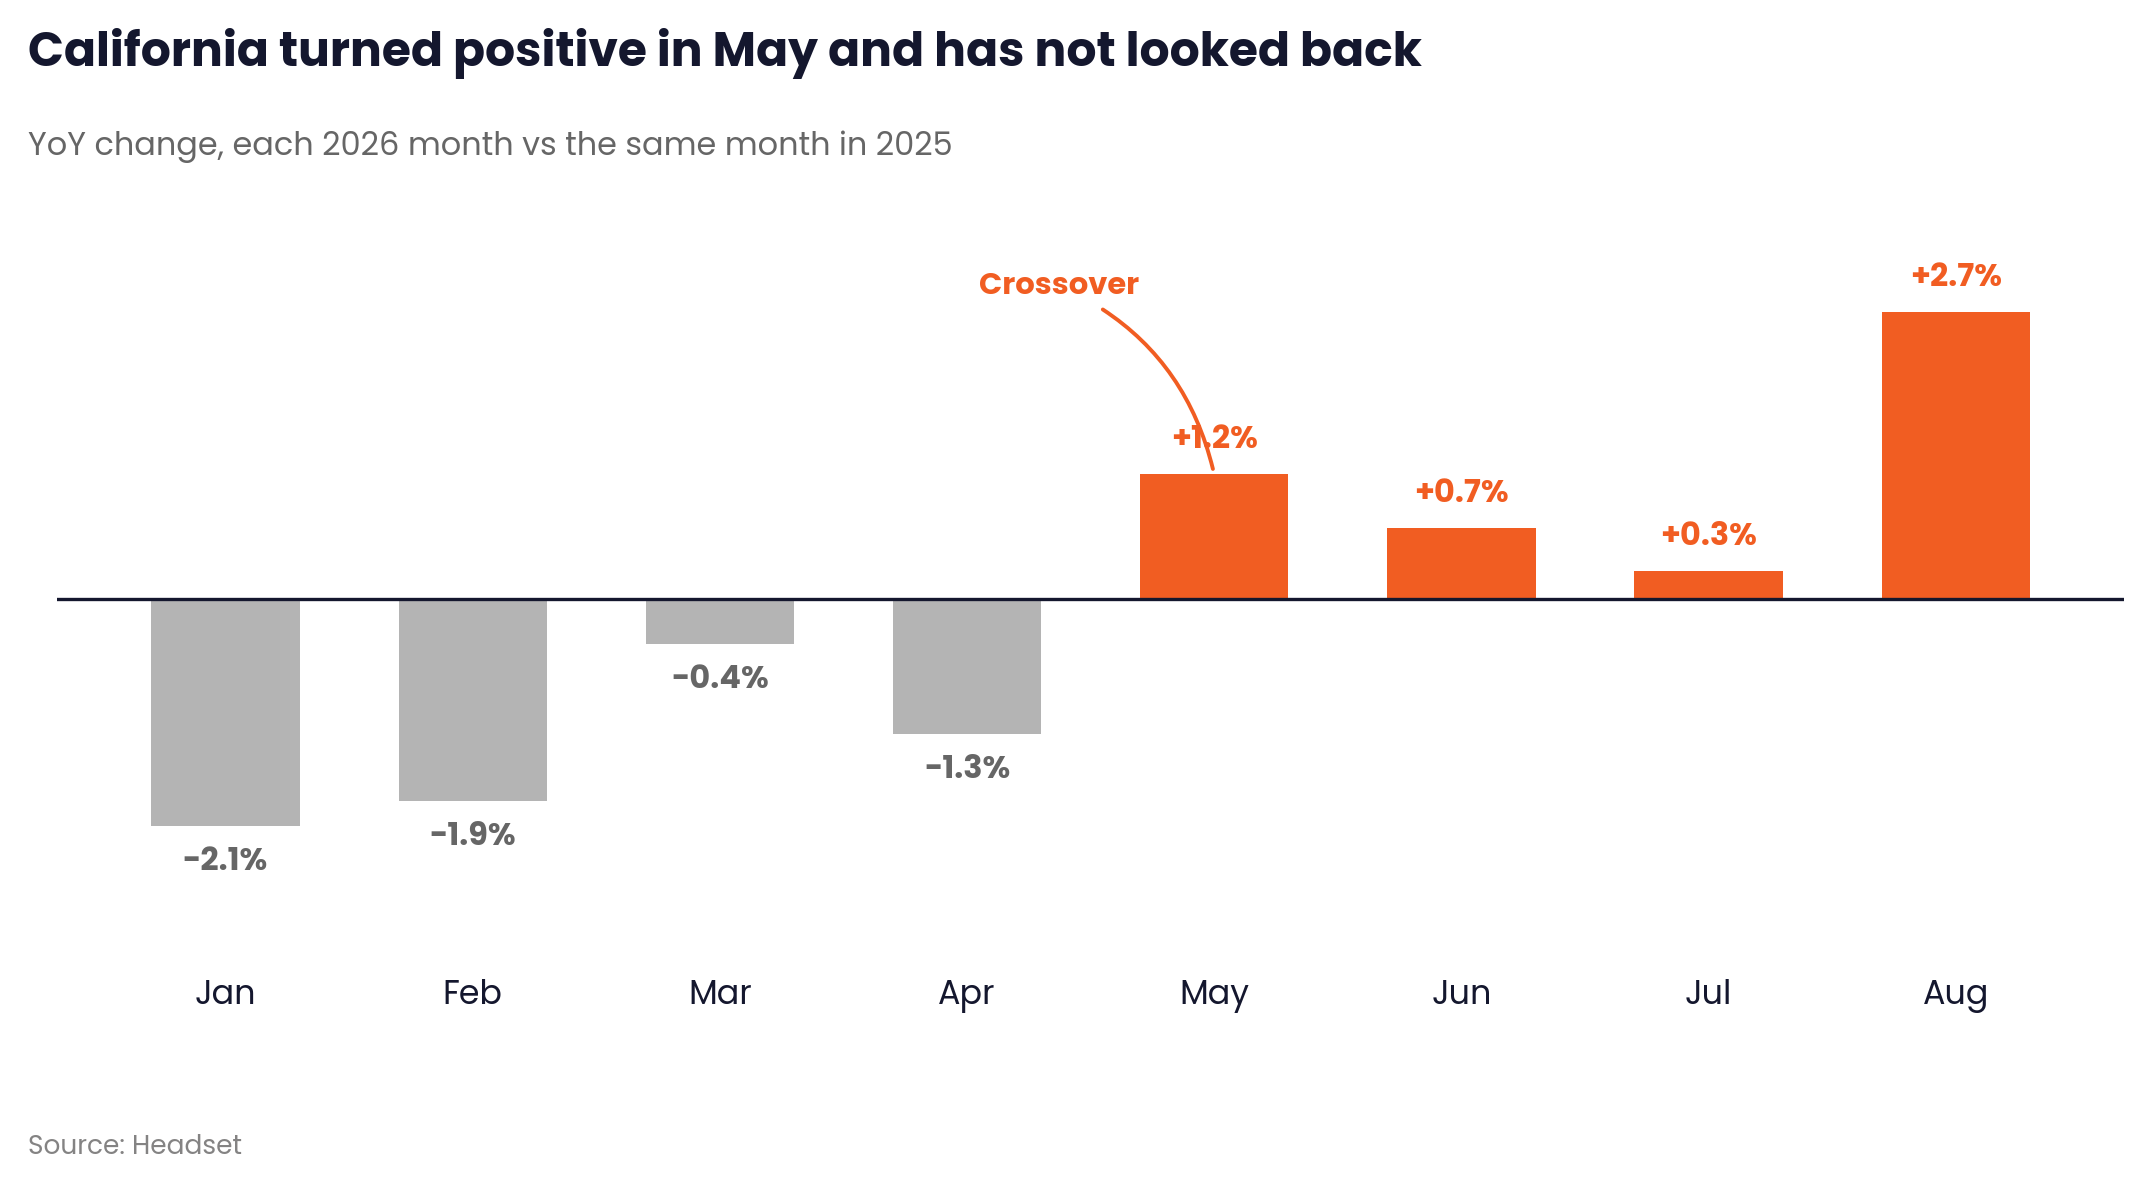
The monthly detail confirms it is not an averaging artifact. January through April ran negative, but progressively less so. May crossed into growth. June, July, and August held there, and August posted the strongest month of the year at +2.7%. Four consecutive months of growth after four years of decline is a floor you can plan around.
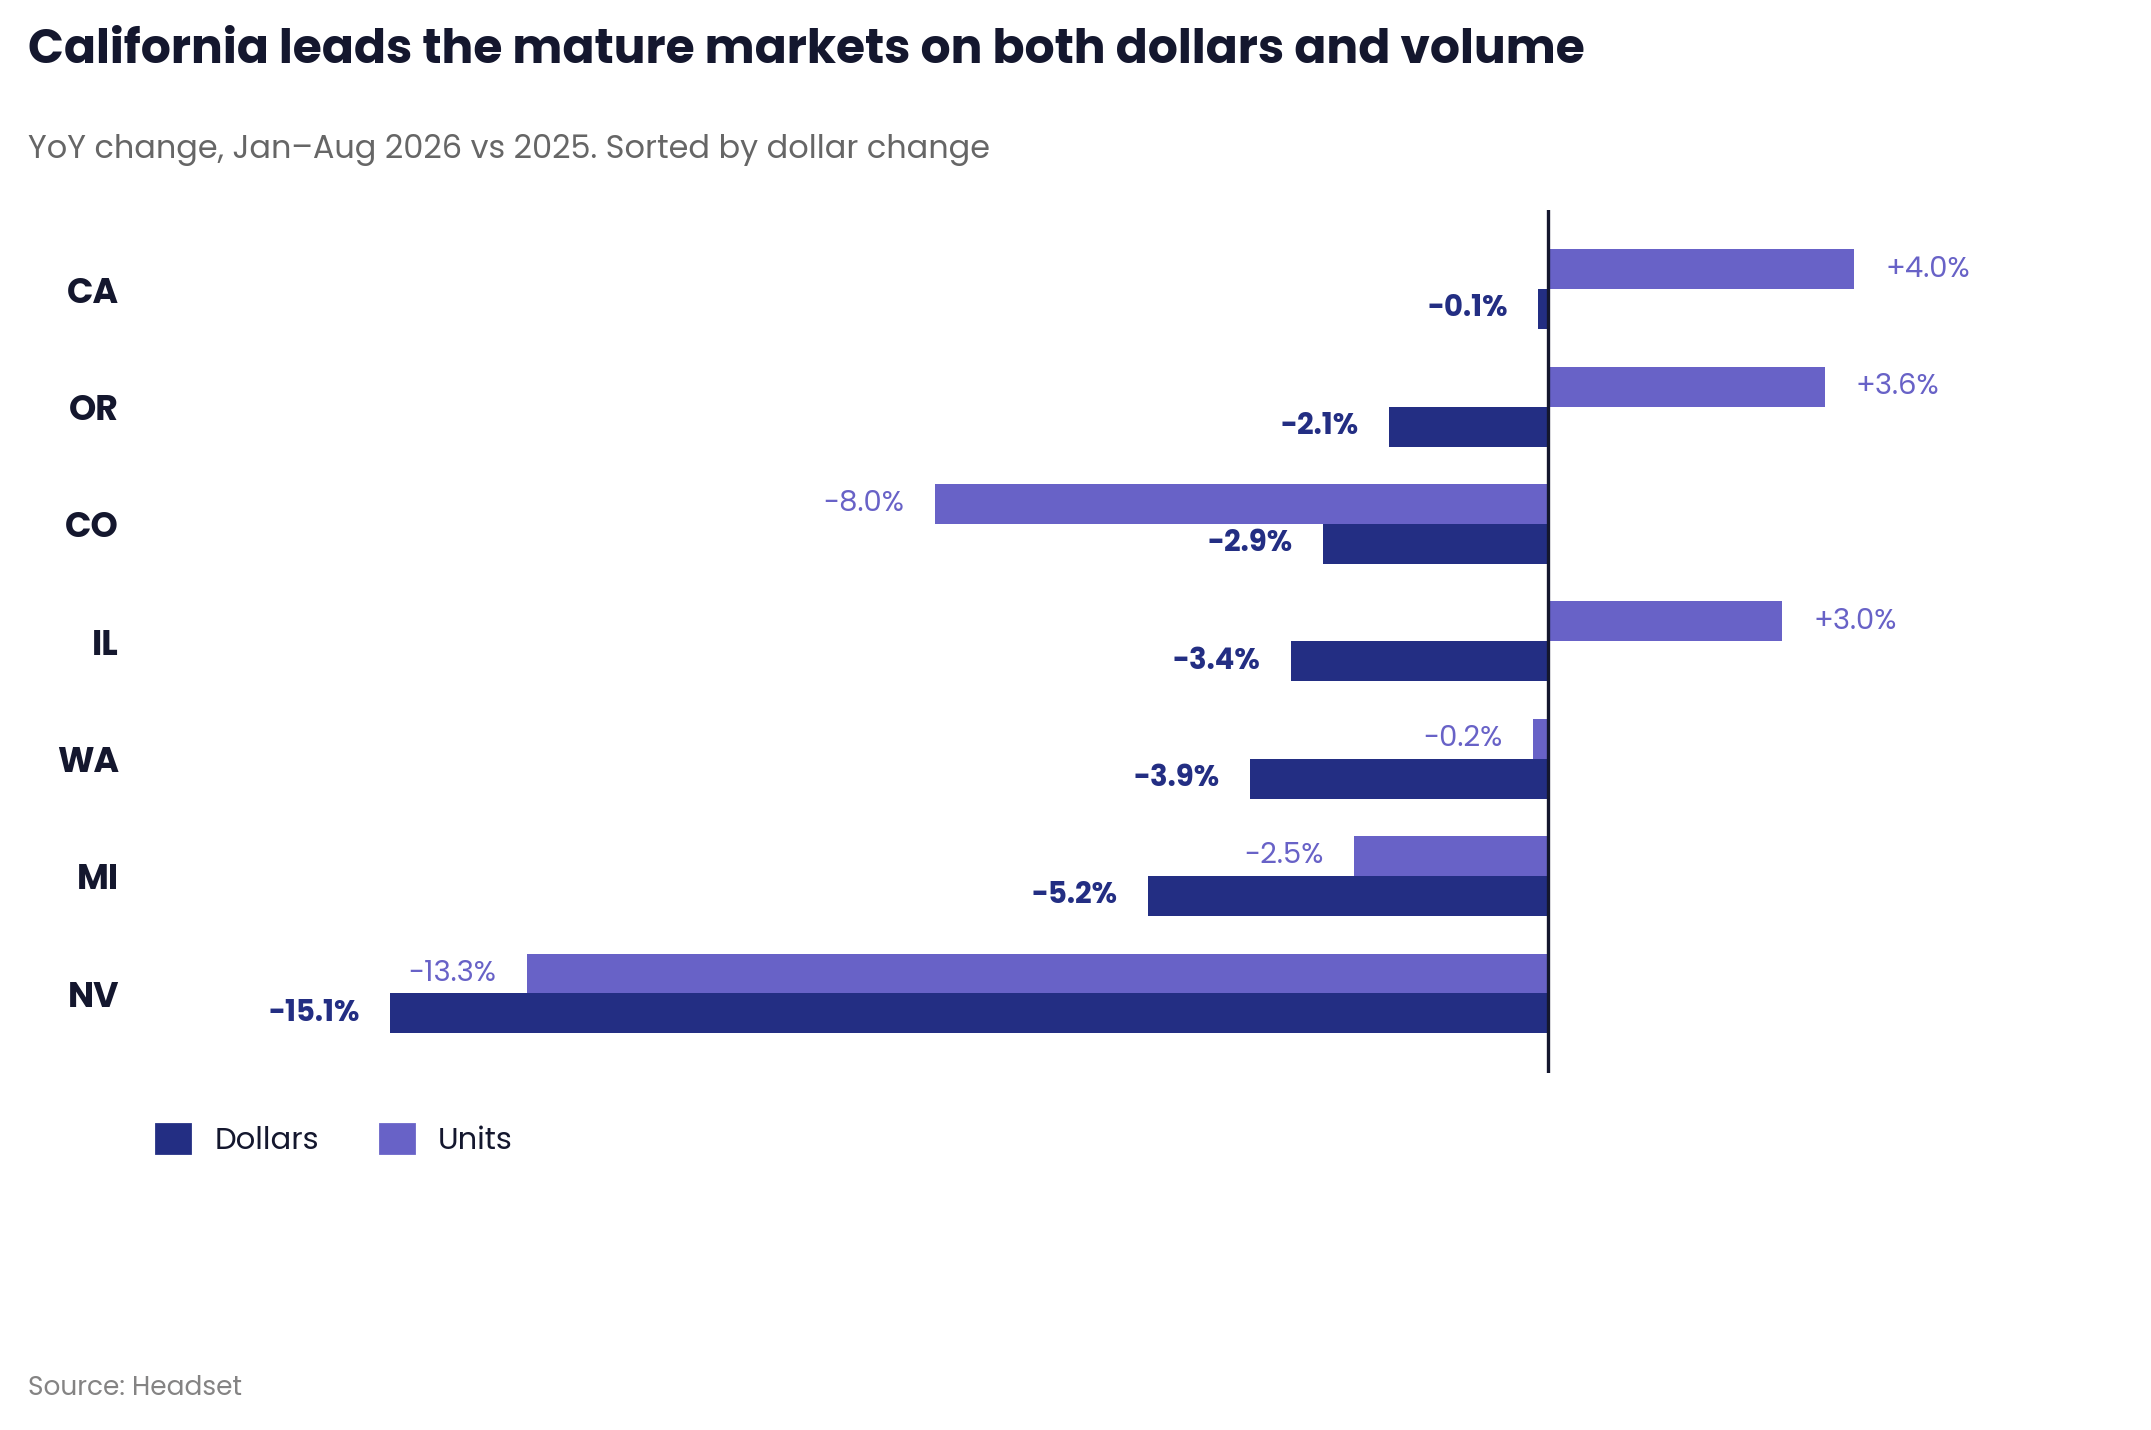
Set against its peers, California now leads the mature markets on both measures. Its 0.1% dollar decline is the smallest in the group, and its 4% unit growth is the largest. Michigan, the market that spent five years as the industry's growth narrative, is down 5.2% in dollars and 2.5% in units. Nevada has fallen 15.1%. Colorado, which corrected earlier than anyone, is giving up 8% of its units this year.
Worth naming the caveat plainly: California's dollar performance is not growth. It is the absence of decline. What follows is the case that the absence of decline is being produced by real demand rather than by accounting.
Why It Turned: Volume, Not Price
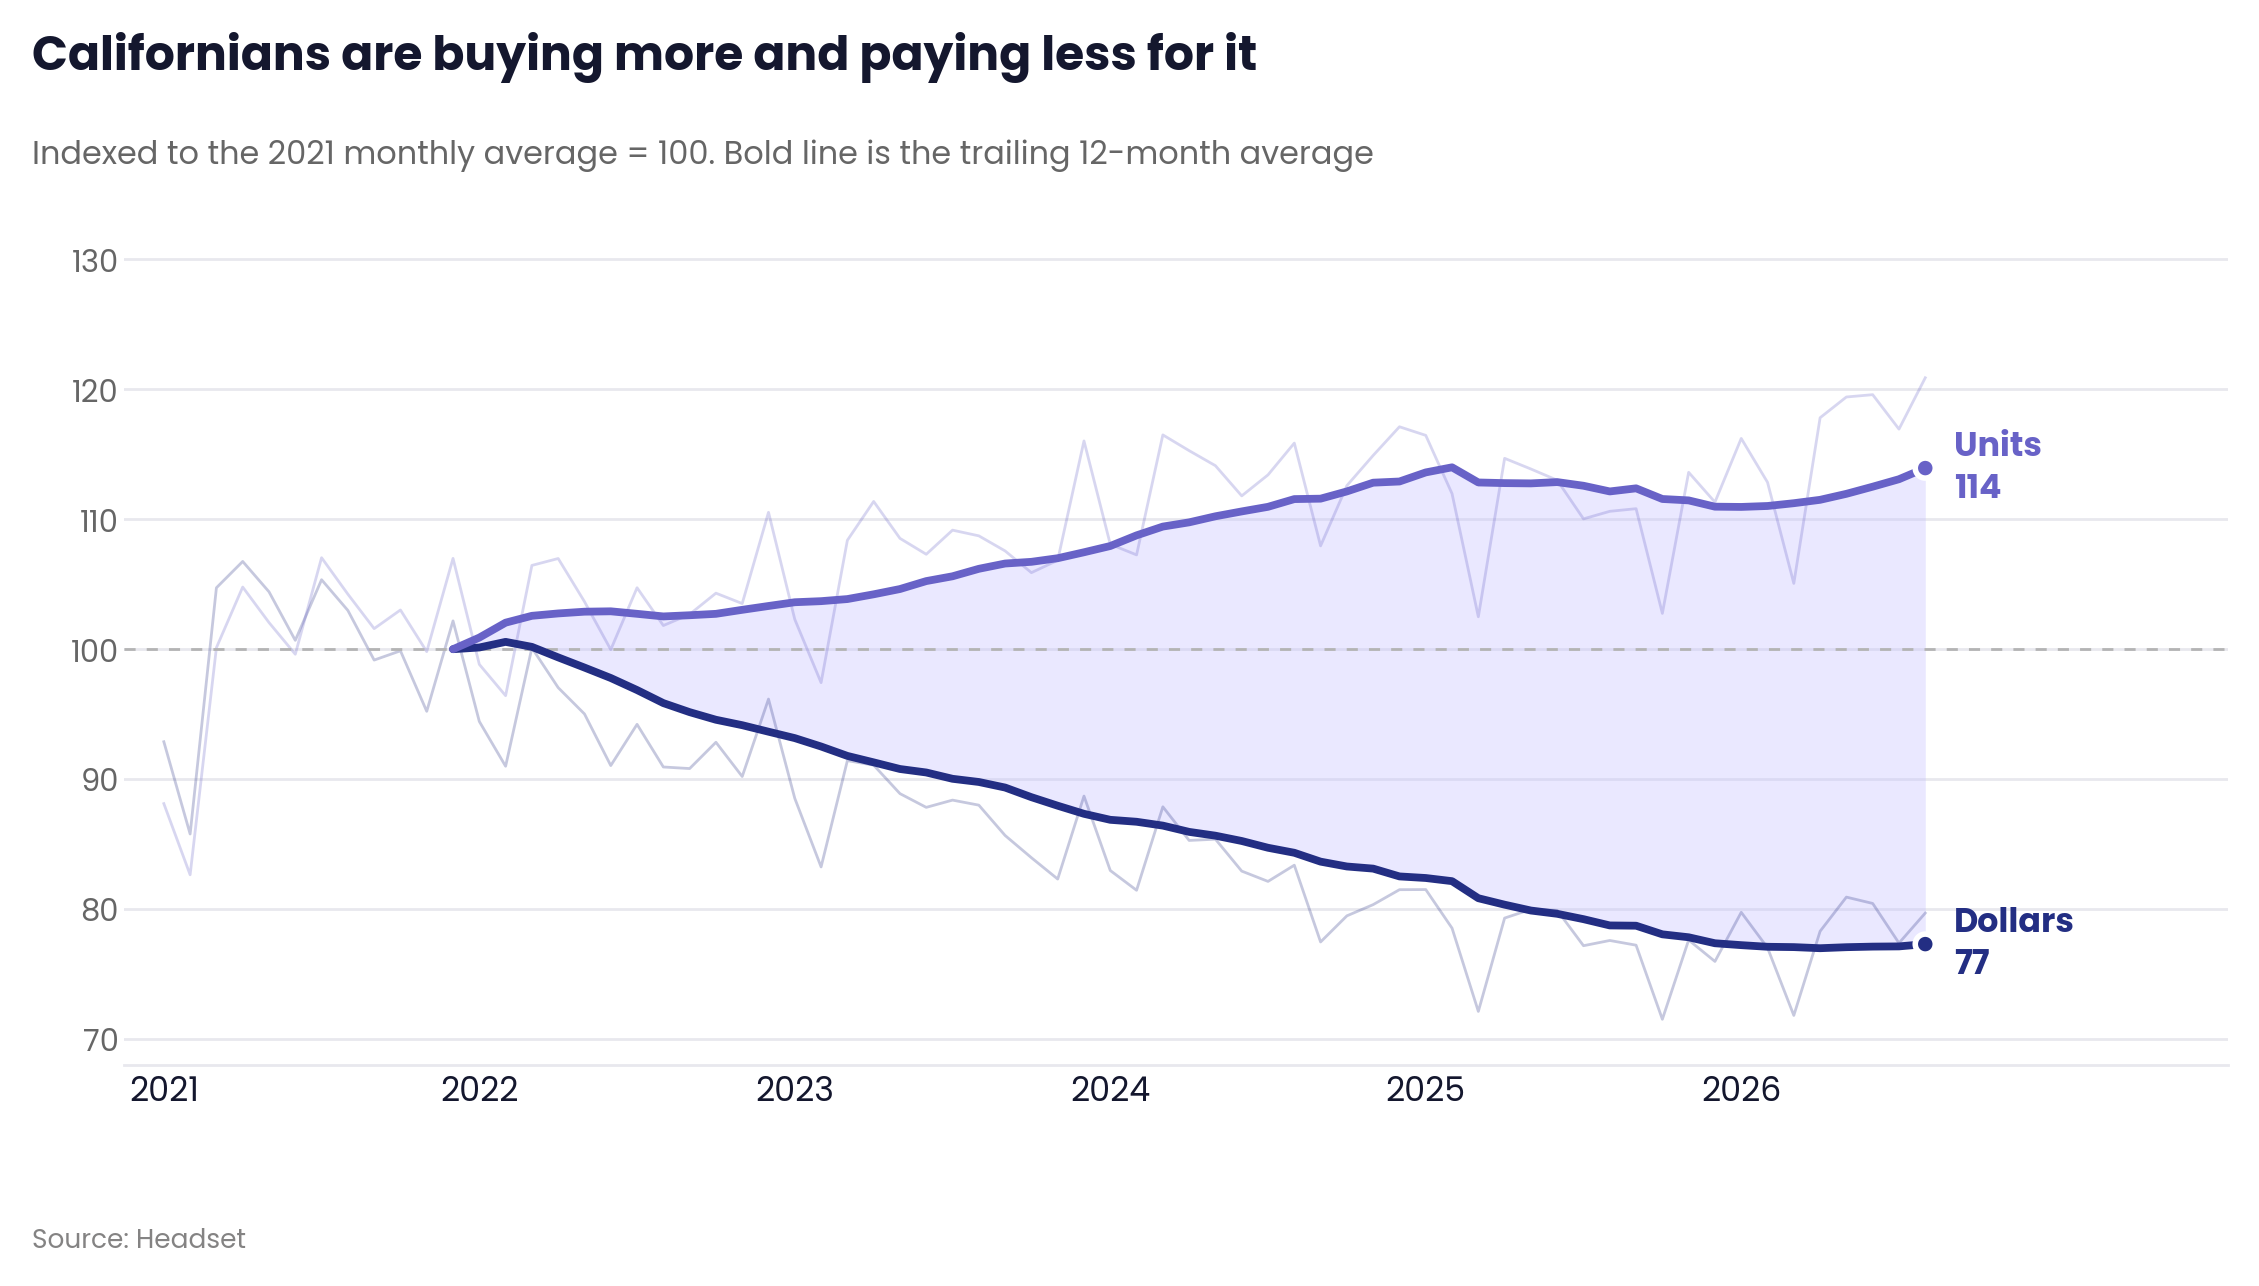
Strip out price and California looks like a different market. Unit volume now sits 14% above the 2021 average while dollars sit 23% below it, and the gap has widened every year since 2022. Cheaper cannabis expanded consumption rather than simply redistributing it: Flower fell to $3.79 a gram from $4.62 in 2024, and consumers answered by buying larger formats more often. Demand is outrunning the price decline before it reaches the bottom line: gross sales, measured before retailer discounts, rose 3.5% January through August, while net sales were flat at −0.1% because the discount rate climbed from 20.3% to 23.1%. The recovery is real and larger than the headline suggests. It is being handed back at the register.
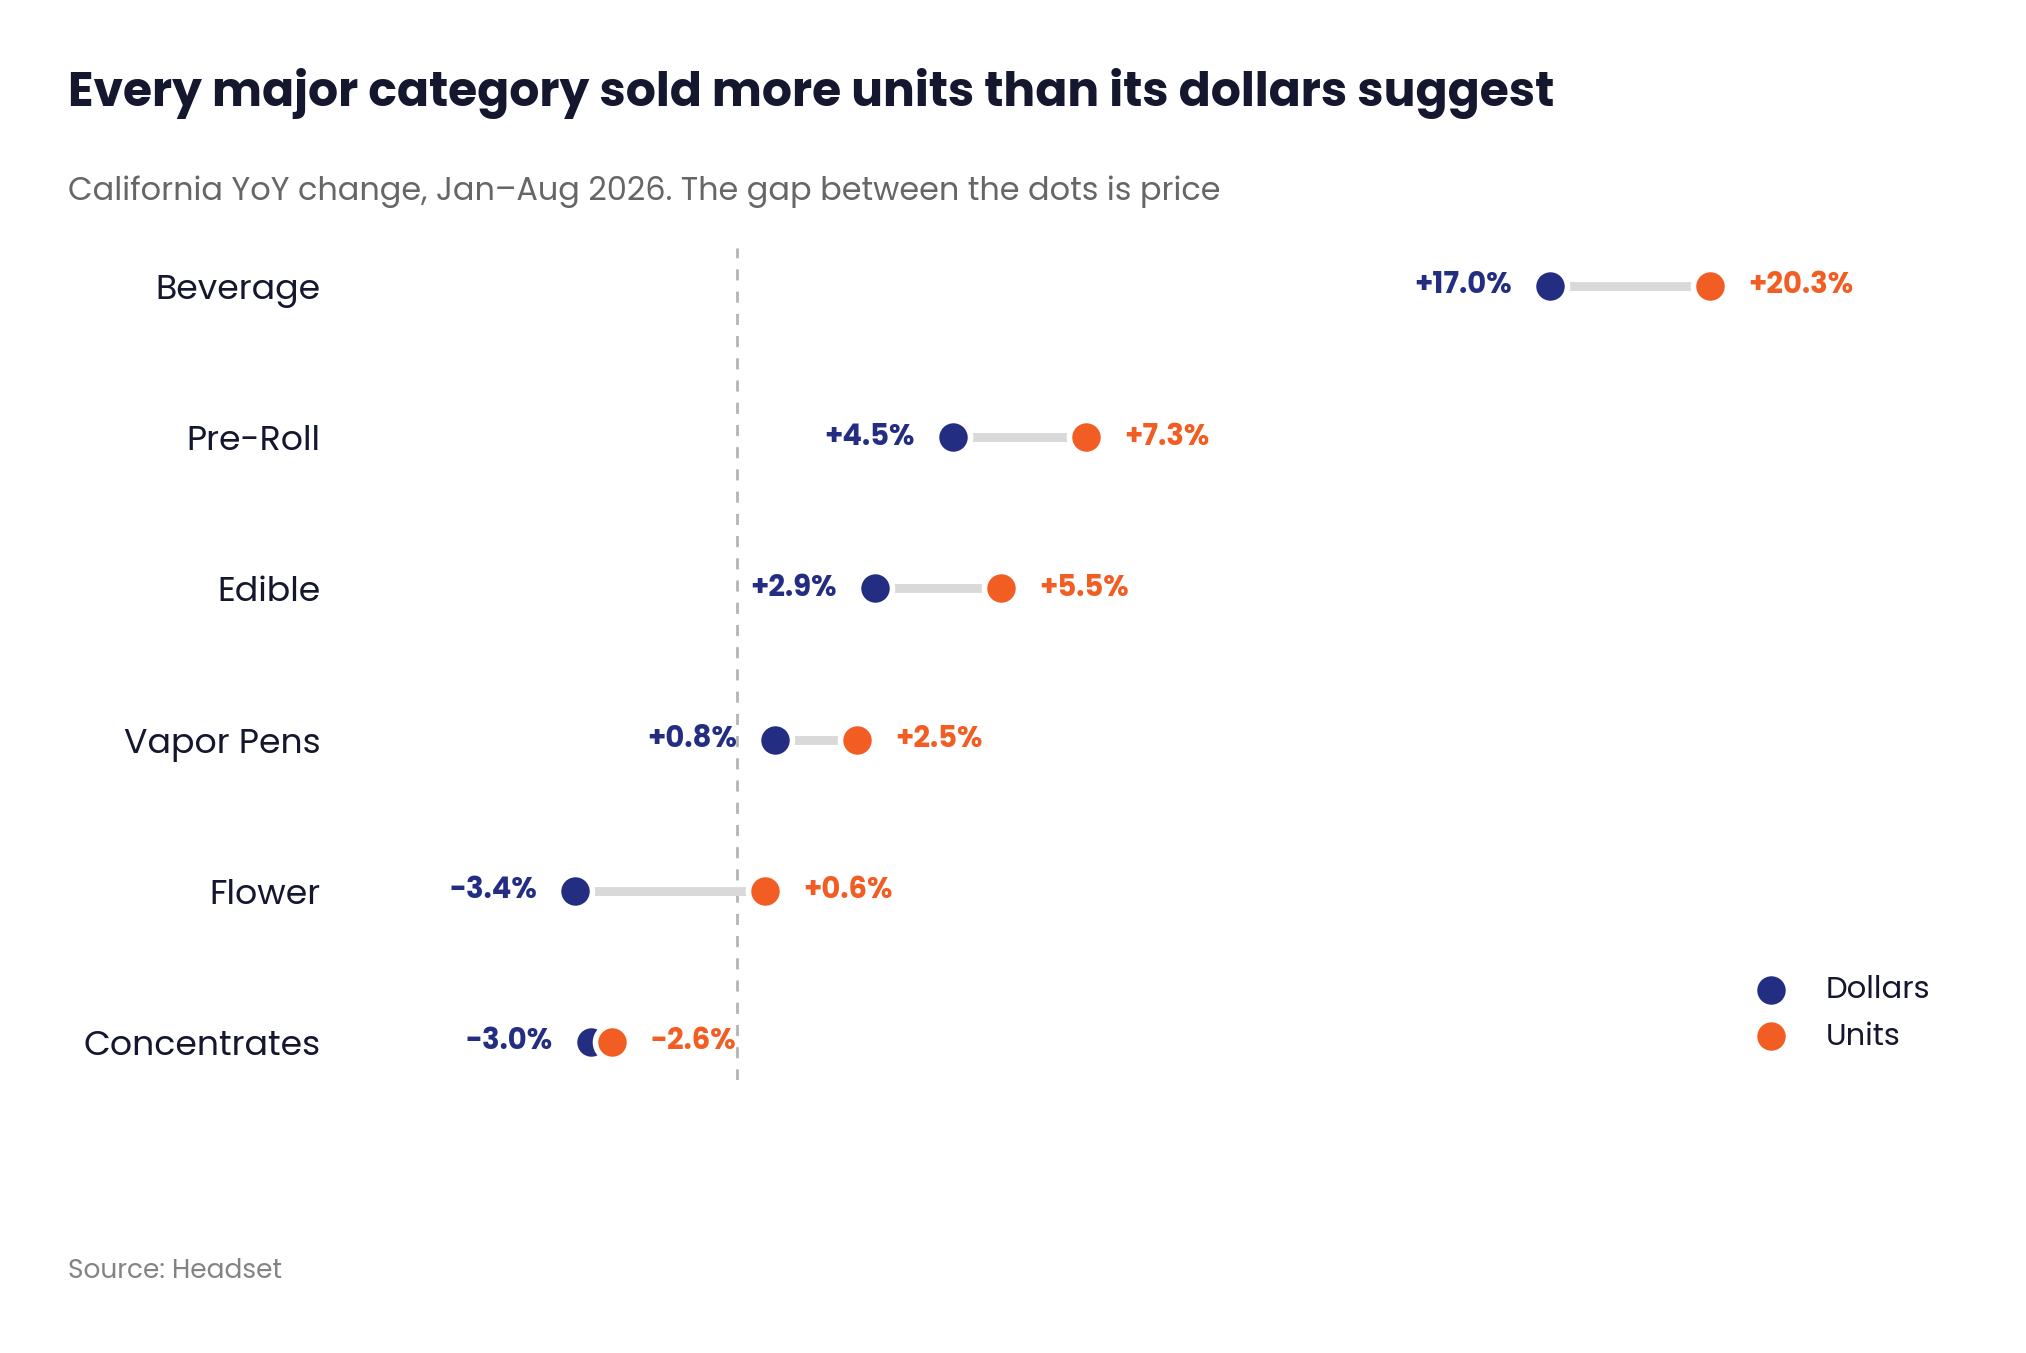
The category detail says the same thing. Every major category except concentrates moved more units in 2026 than in 2025, and in every single one the unit line sits above the dollar line. Flower dollars fell 3.4% while flower units rose 0.6%. Vapor Pen dollars grew 0.8% while units grew 2.5%. Pre-roll dollars grew 4.5% against units at 7.3%.
The gap between the two dots is price, and in California it runs between 1.7 and 4 points across the board.
For anyone modeling this market, that distinction decides the forecast. A market losing units is losing consumers, and the only fix is bringing people back. A market gaining units while losing dollars has its consumers, but it also has a pricing problem. Those are different businesses with different timelines, and the second one resolves the moment deflation slows.
Vapor Pens are the clearest case of deflation slowing. Price per equivalent unit fell 11.9% from 2024 to 2025 and only 2.9% from 2025 to 2026. The state's second-largest category, nearly 30% of all dollars, has effectively found its price floor. That is most of why the total held flat this year.
Where the Growth Is
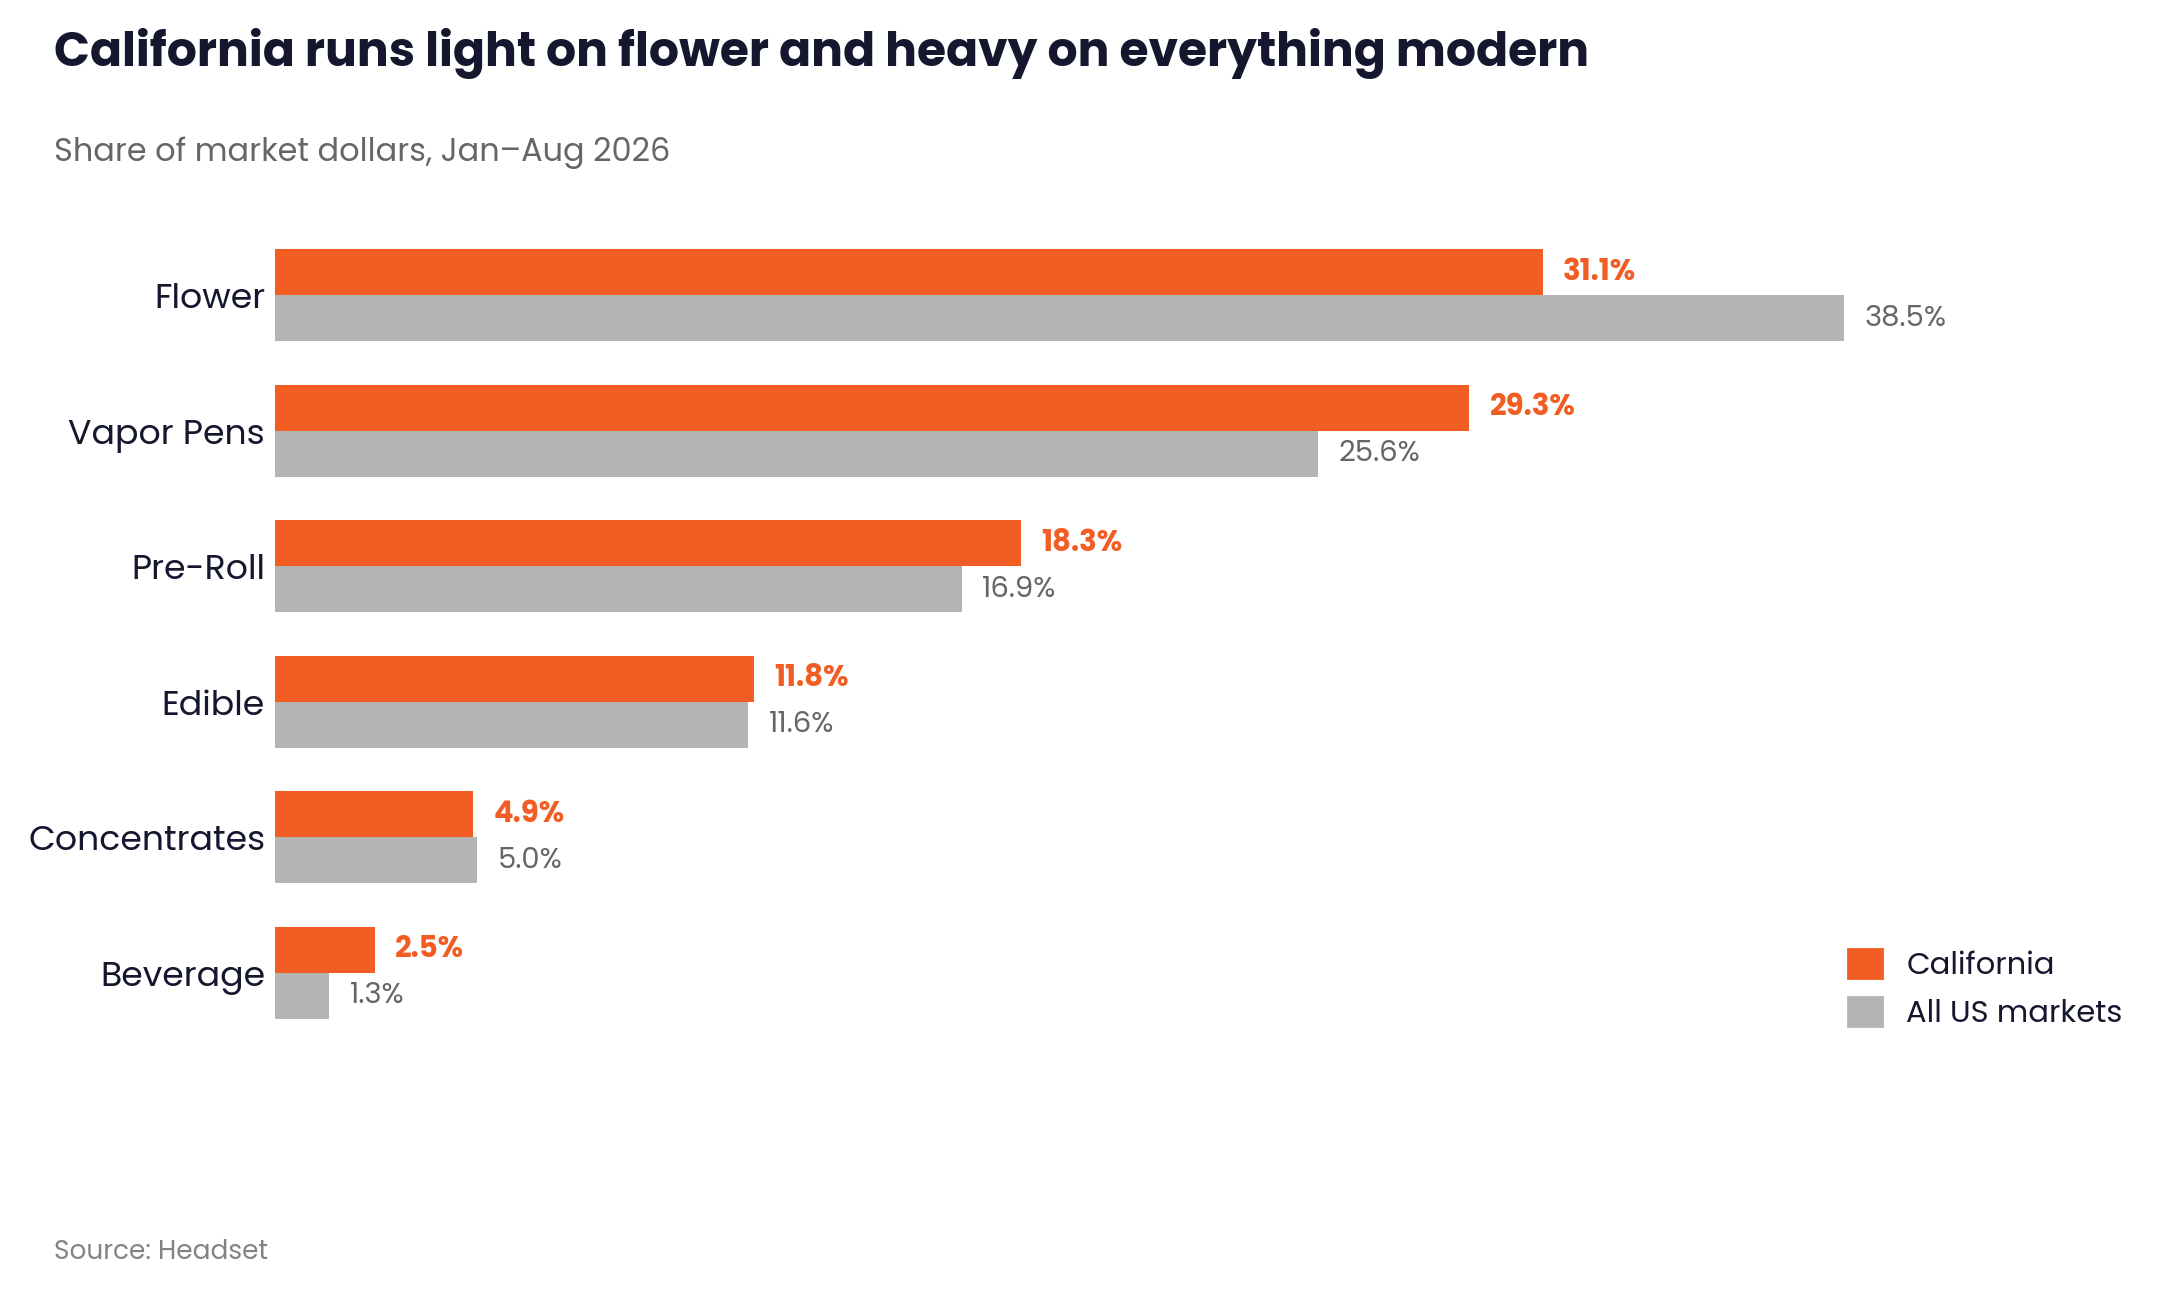
California's shelf looks different from everyone else's. Flower takes 31.1% of dollars here against 38.5% across all US Insights markets, and Vapor Pens take 29.3% against 25.6%. Beverage runs at 2.5% against 1.3% nationally, close to twice the national rate and the widest over-index among the state's major categories.
This is what one of the most competitive, innovation-dense markets in the country produces: a consumer base that a thousand-plus competing brands have trained to try things. California does not have a flower habit to break. It has an appetite for whatever is next.
That appetite is where the 2026 growth is sitting. The five segments that added the most dollars this year were all-in-one disposable vapes (+$41.7M), specialty and infused flower (+$11.0M, up 40.4%), hybrid single-strain pre-rolls (+$9.1M), gummies (+$8.8M), and indica flower (+$8.3M). Carbonated beverages added $5.9M on a $12.7M base.
Vapor Pens
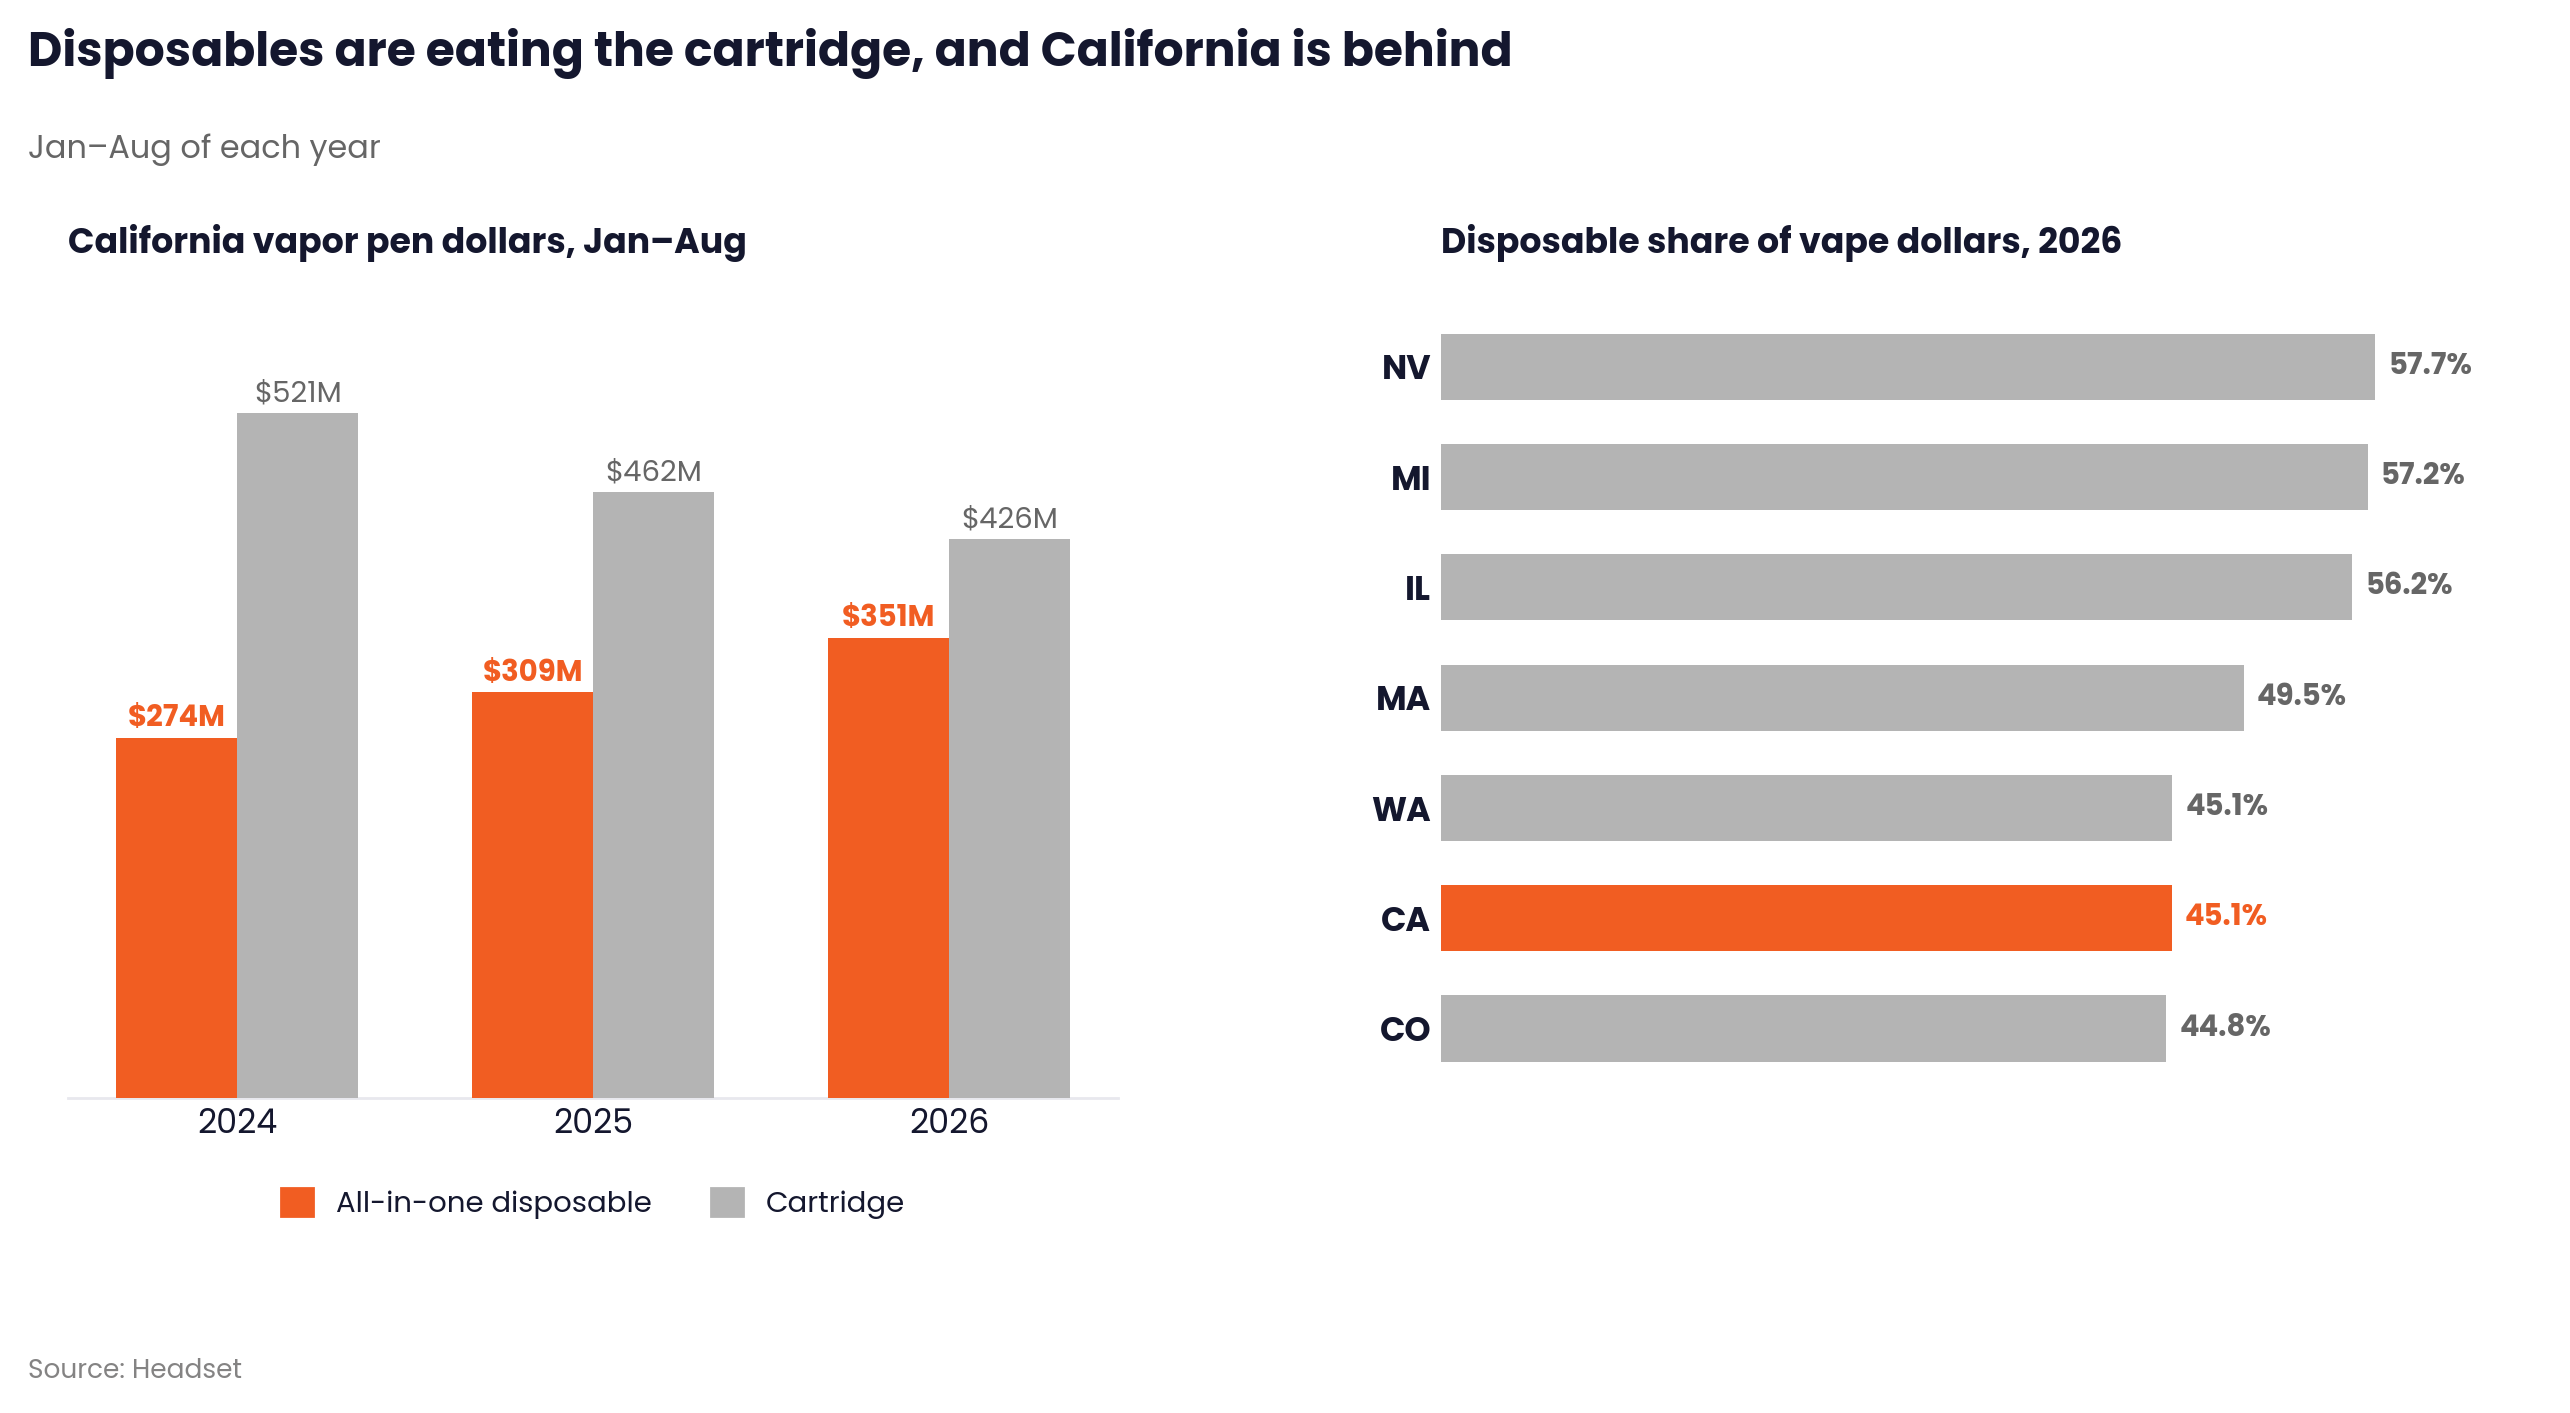
Vapor Pens are California's second-largest category at 29.3% of dollars, and internally the category is being rebuilt. All-in-one disposables took $350.7M of the first eight months of 2026, up $41.7M. Cartridges took $425.6M, down $35.9M. Disposable share of category dollars has moved from 34.5% in 2024 to 40.1% in 2025 to 45.1% in 2026, roughly five points a year with no sign of slowing.
The format also commands a premium. Average item price on a disposable is $23.76 against $20.80 for a cartridge, and that gap has held: disposable pricing has been stable since 2024, while cartridge pricing kept falling.
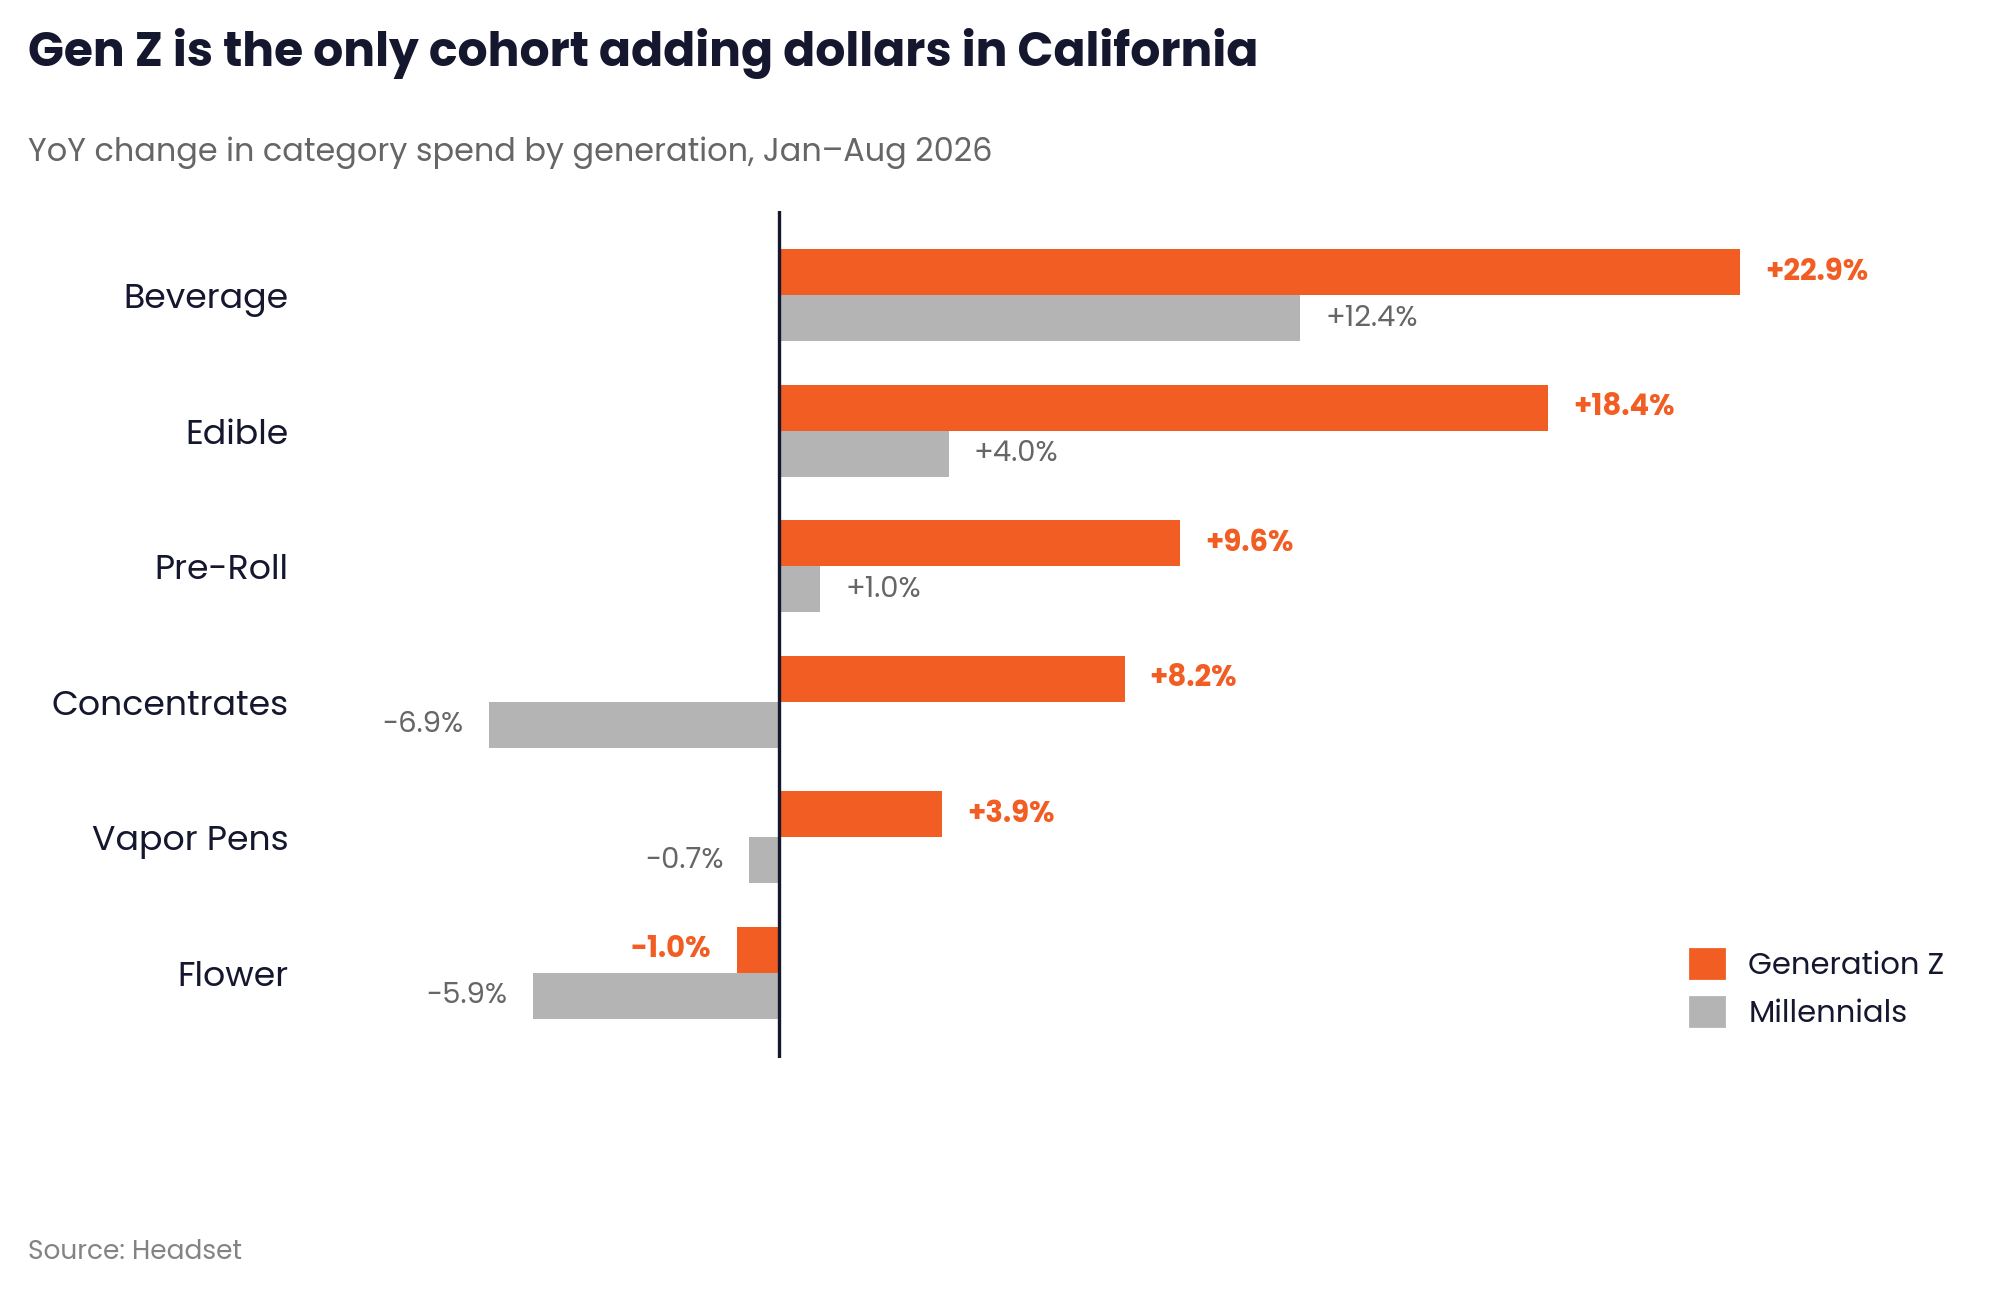
Part of why this format is moving is who is buying it. Gen Z is the only generation adding dollars in California. Its spend grew 5% year over year and its share of the market climbed from 21.4% to 22.6%. Millennials fell 2.2%, Boomers fell 2%, and Gen X was flat at -0.4%. Millennials still own the market at 41.8% of dollars, but they are not the growth.
Gen Z puts 44.8% of its California spend into vapor pens. Millennials put 29.9%, and send 32.1% to flower against Gen Z's 22.1%. That is a fifteen-point gap in the largest category in the state, running in opposite directions.
The categories carrying California's volume recovery, Beverage and Pre-Roll and disposable Vapor Pens, are the same categories where Gen Z is over-indexed and accelerating. That is not a coincidence, and it is the most reliable forward indicator in this data. California's Gen Z share (22.6%) already trails only Washington (24.8%) among mature markets, and it is the cohort still expanding.
Beverage
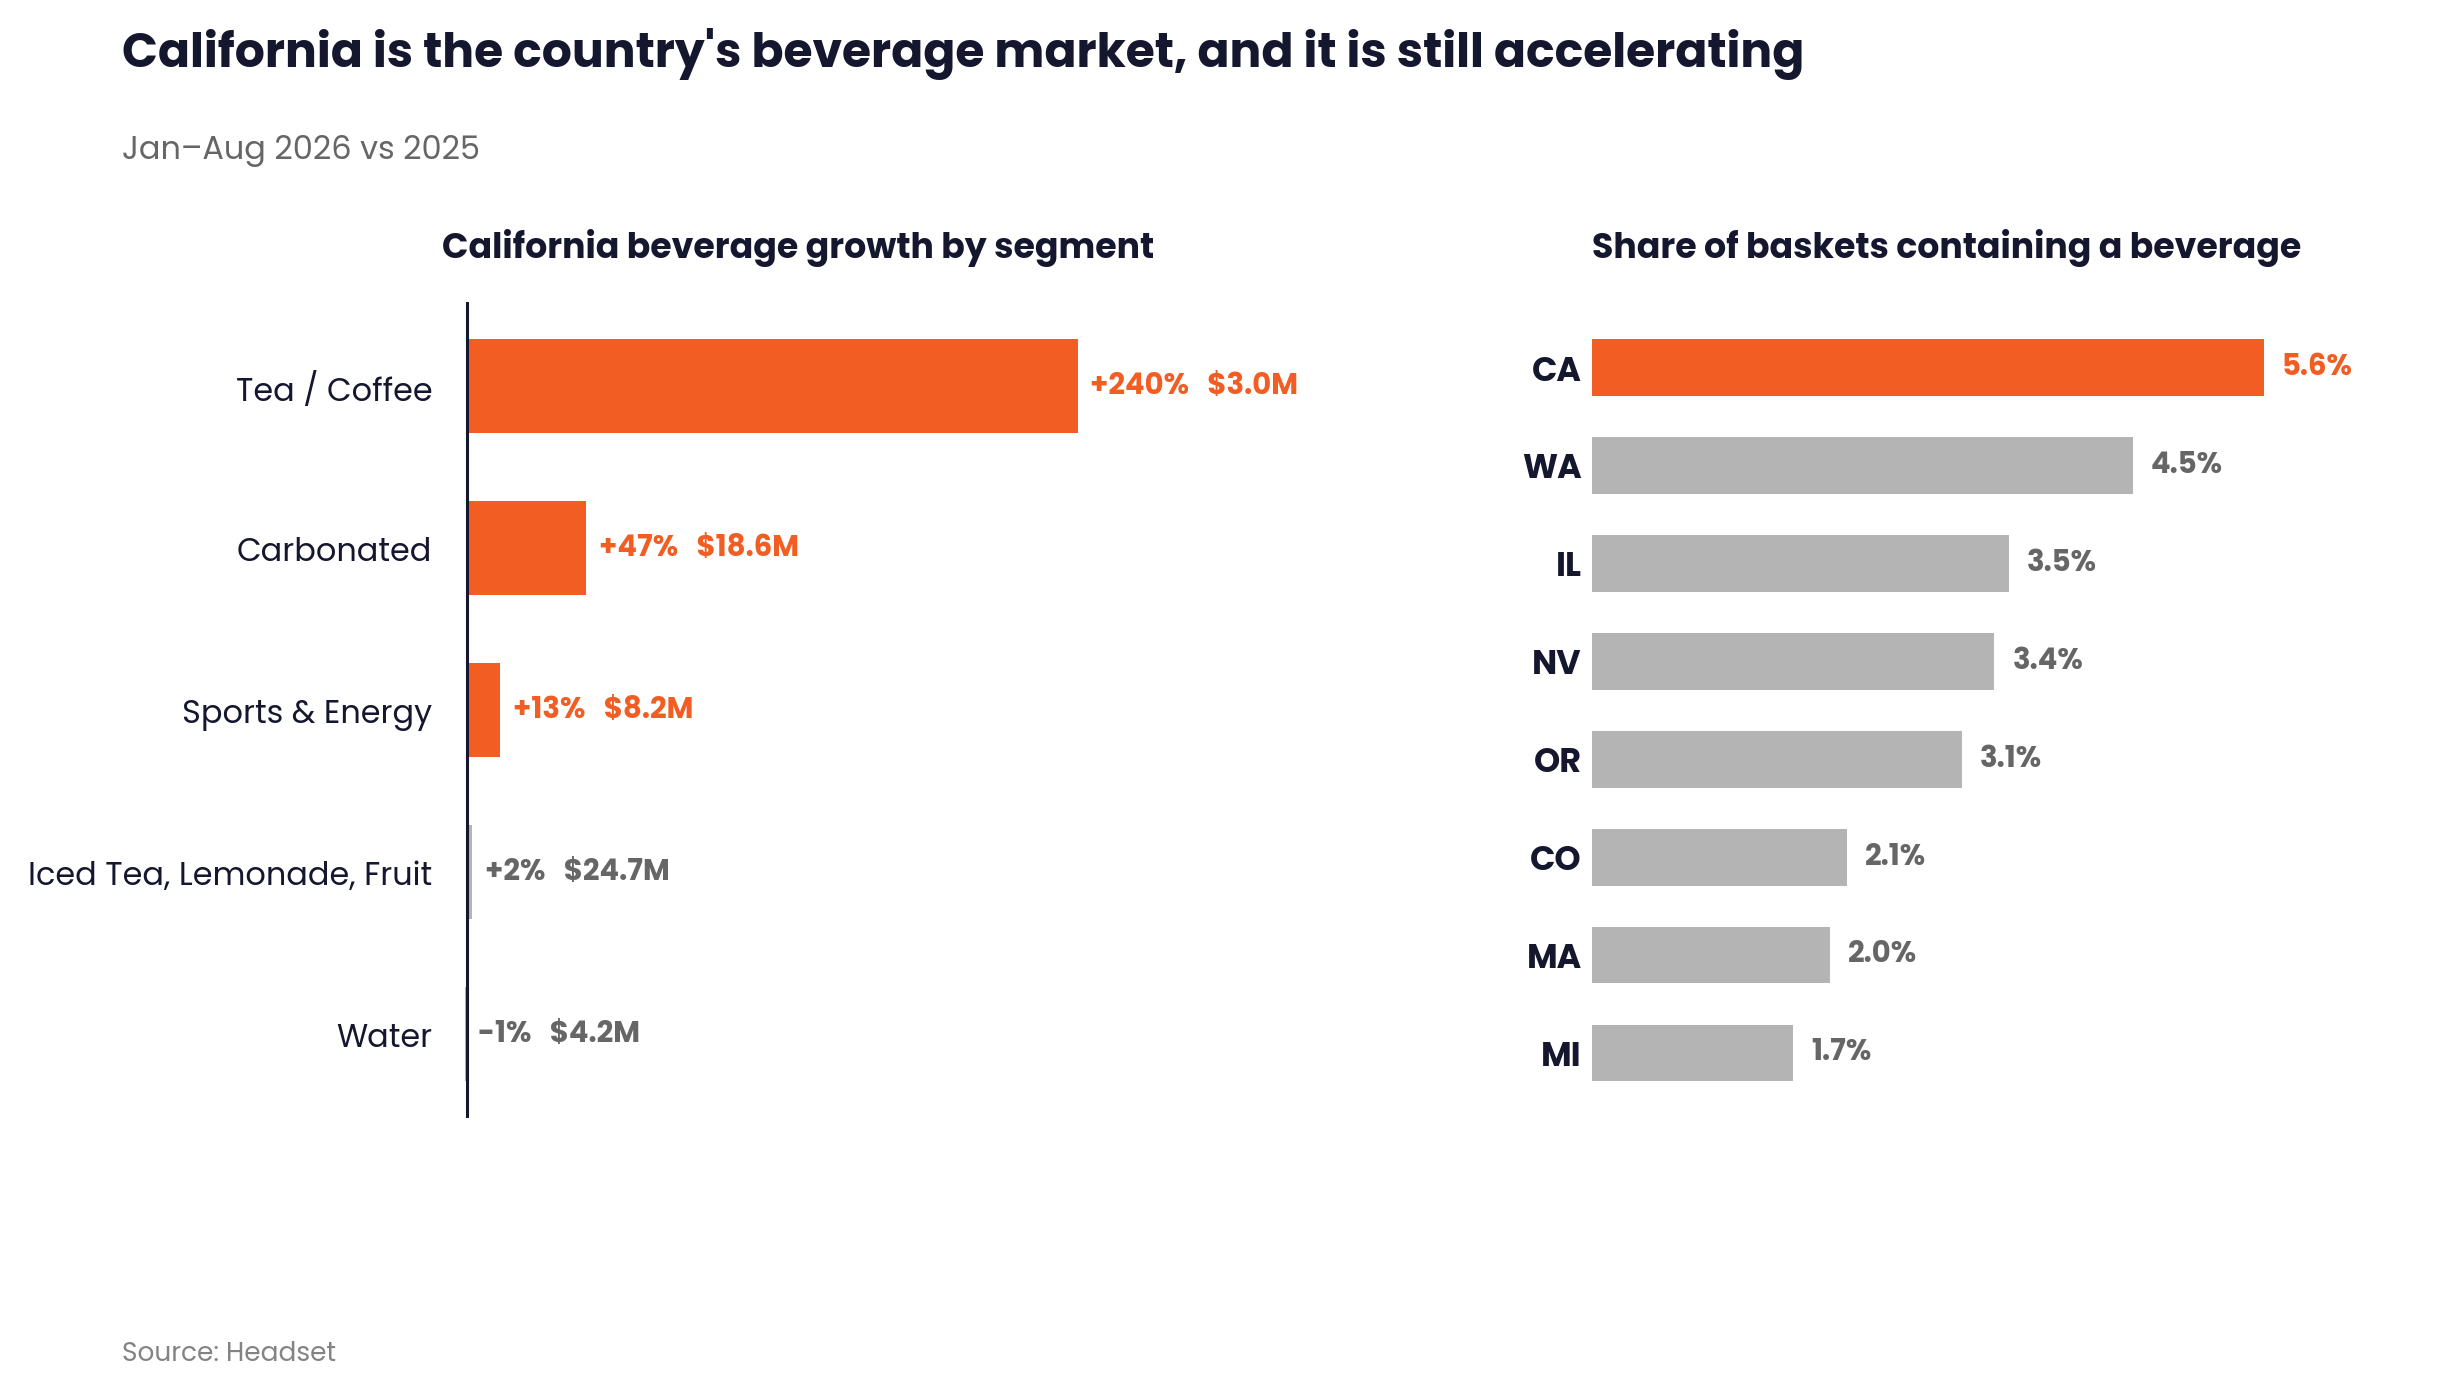
Cannabis beverage has been "the next big category" for many years and mostly failed to be one. It's still just 2.5% of California dollars, but the state is at the vanguard of developing the category. Beverage grew 17% to $64.9M and basket penetration reached 5.6%, the highest rate in the country and more than triple Michigan's. The growth isn't price as price per unit has been flat for three years, so this is real consumption and not inflation.
It's also concentrating fast: brands fell from 71 to 46 in a year, and St Ides, Uncle Arnie's, and Not Your Father's Root Beer, all growing faster than the category, now hold 71.4% of it. Revenue per surviving brand is up 80.6%. Growth is shifting toward familiar occasions like carbonated and coffee drinks, and Gen Z, already over-indexing on vapor pens, grew its beverage spend 23%. A category this concentrated growing this fast won't stay open long.
Pre-Roll
Pre-roll is California's third category at 18.3% of dollars, and it grew 4.5% in dollars and 7.3% in units. Basket penetration rose from 30.7% to 31.7%. Healthy on the surface, and the composition underneath is the interesting part.
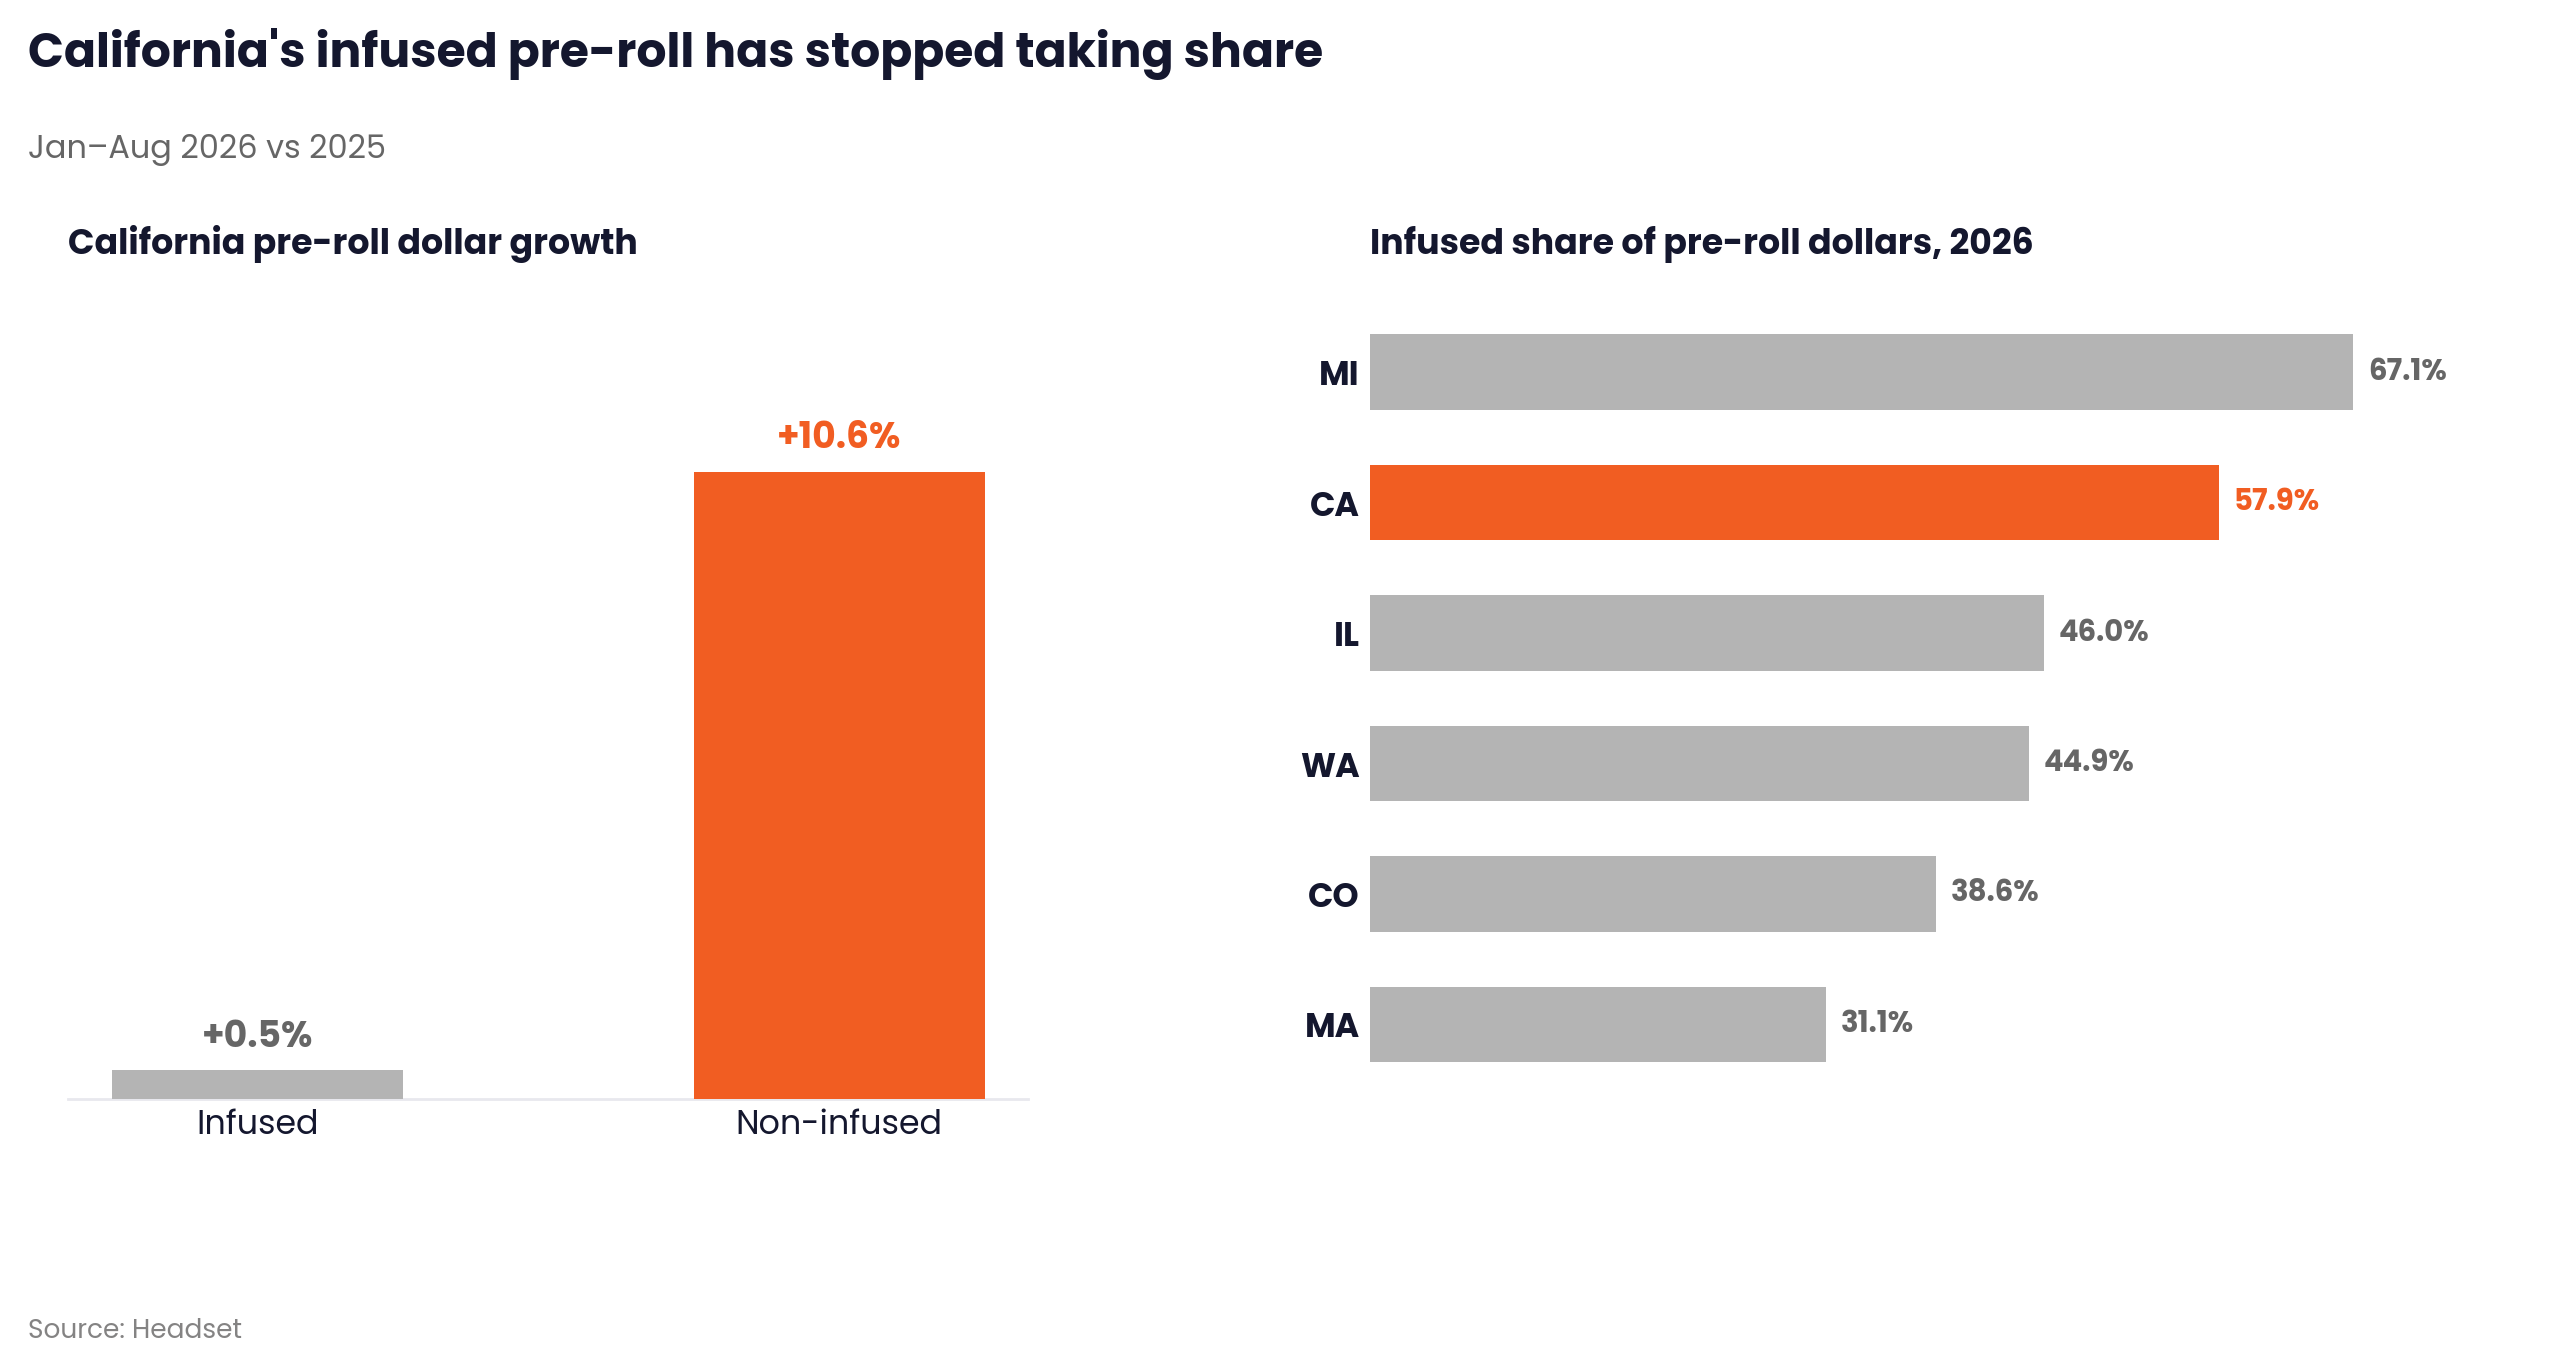
Infused pre-rolls have stopped taking share. The segment holds 57.9% of category dollars, second only to Michigan's 67.1% and well ahead of Colorado at 38.6% and Massachusetts at 31.1%. But it grew only 0.5% in dollars this year, while non-infused grew 10.6%. Share moved two full points back toward the plain joint.
That is a reversal of the pattern every other market is running, and it fits the broader California story. This consumer already adopted infused. Having adopted it, they are now optimizing on price, and a non-infused multi-pack is the cheapest way to hold a pre-roll habit. Multi-packs took 64.9% of category dollars with units up 10.2%, nearly double the 5.5% unit growth on singles.
For brands, the read is that the infused premium has been competed away in California and the growth is in accessible formats with credible strain positioning. The fastest-growing pre-roll segments this year were indica single-strain (+20%), sativa single-strain (+9.2%), and hybrid single-strain (+8.4%, and the largest dollar gain in the category at $9.1M).
Where It's Dragging: Flower Economics
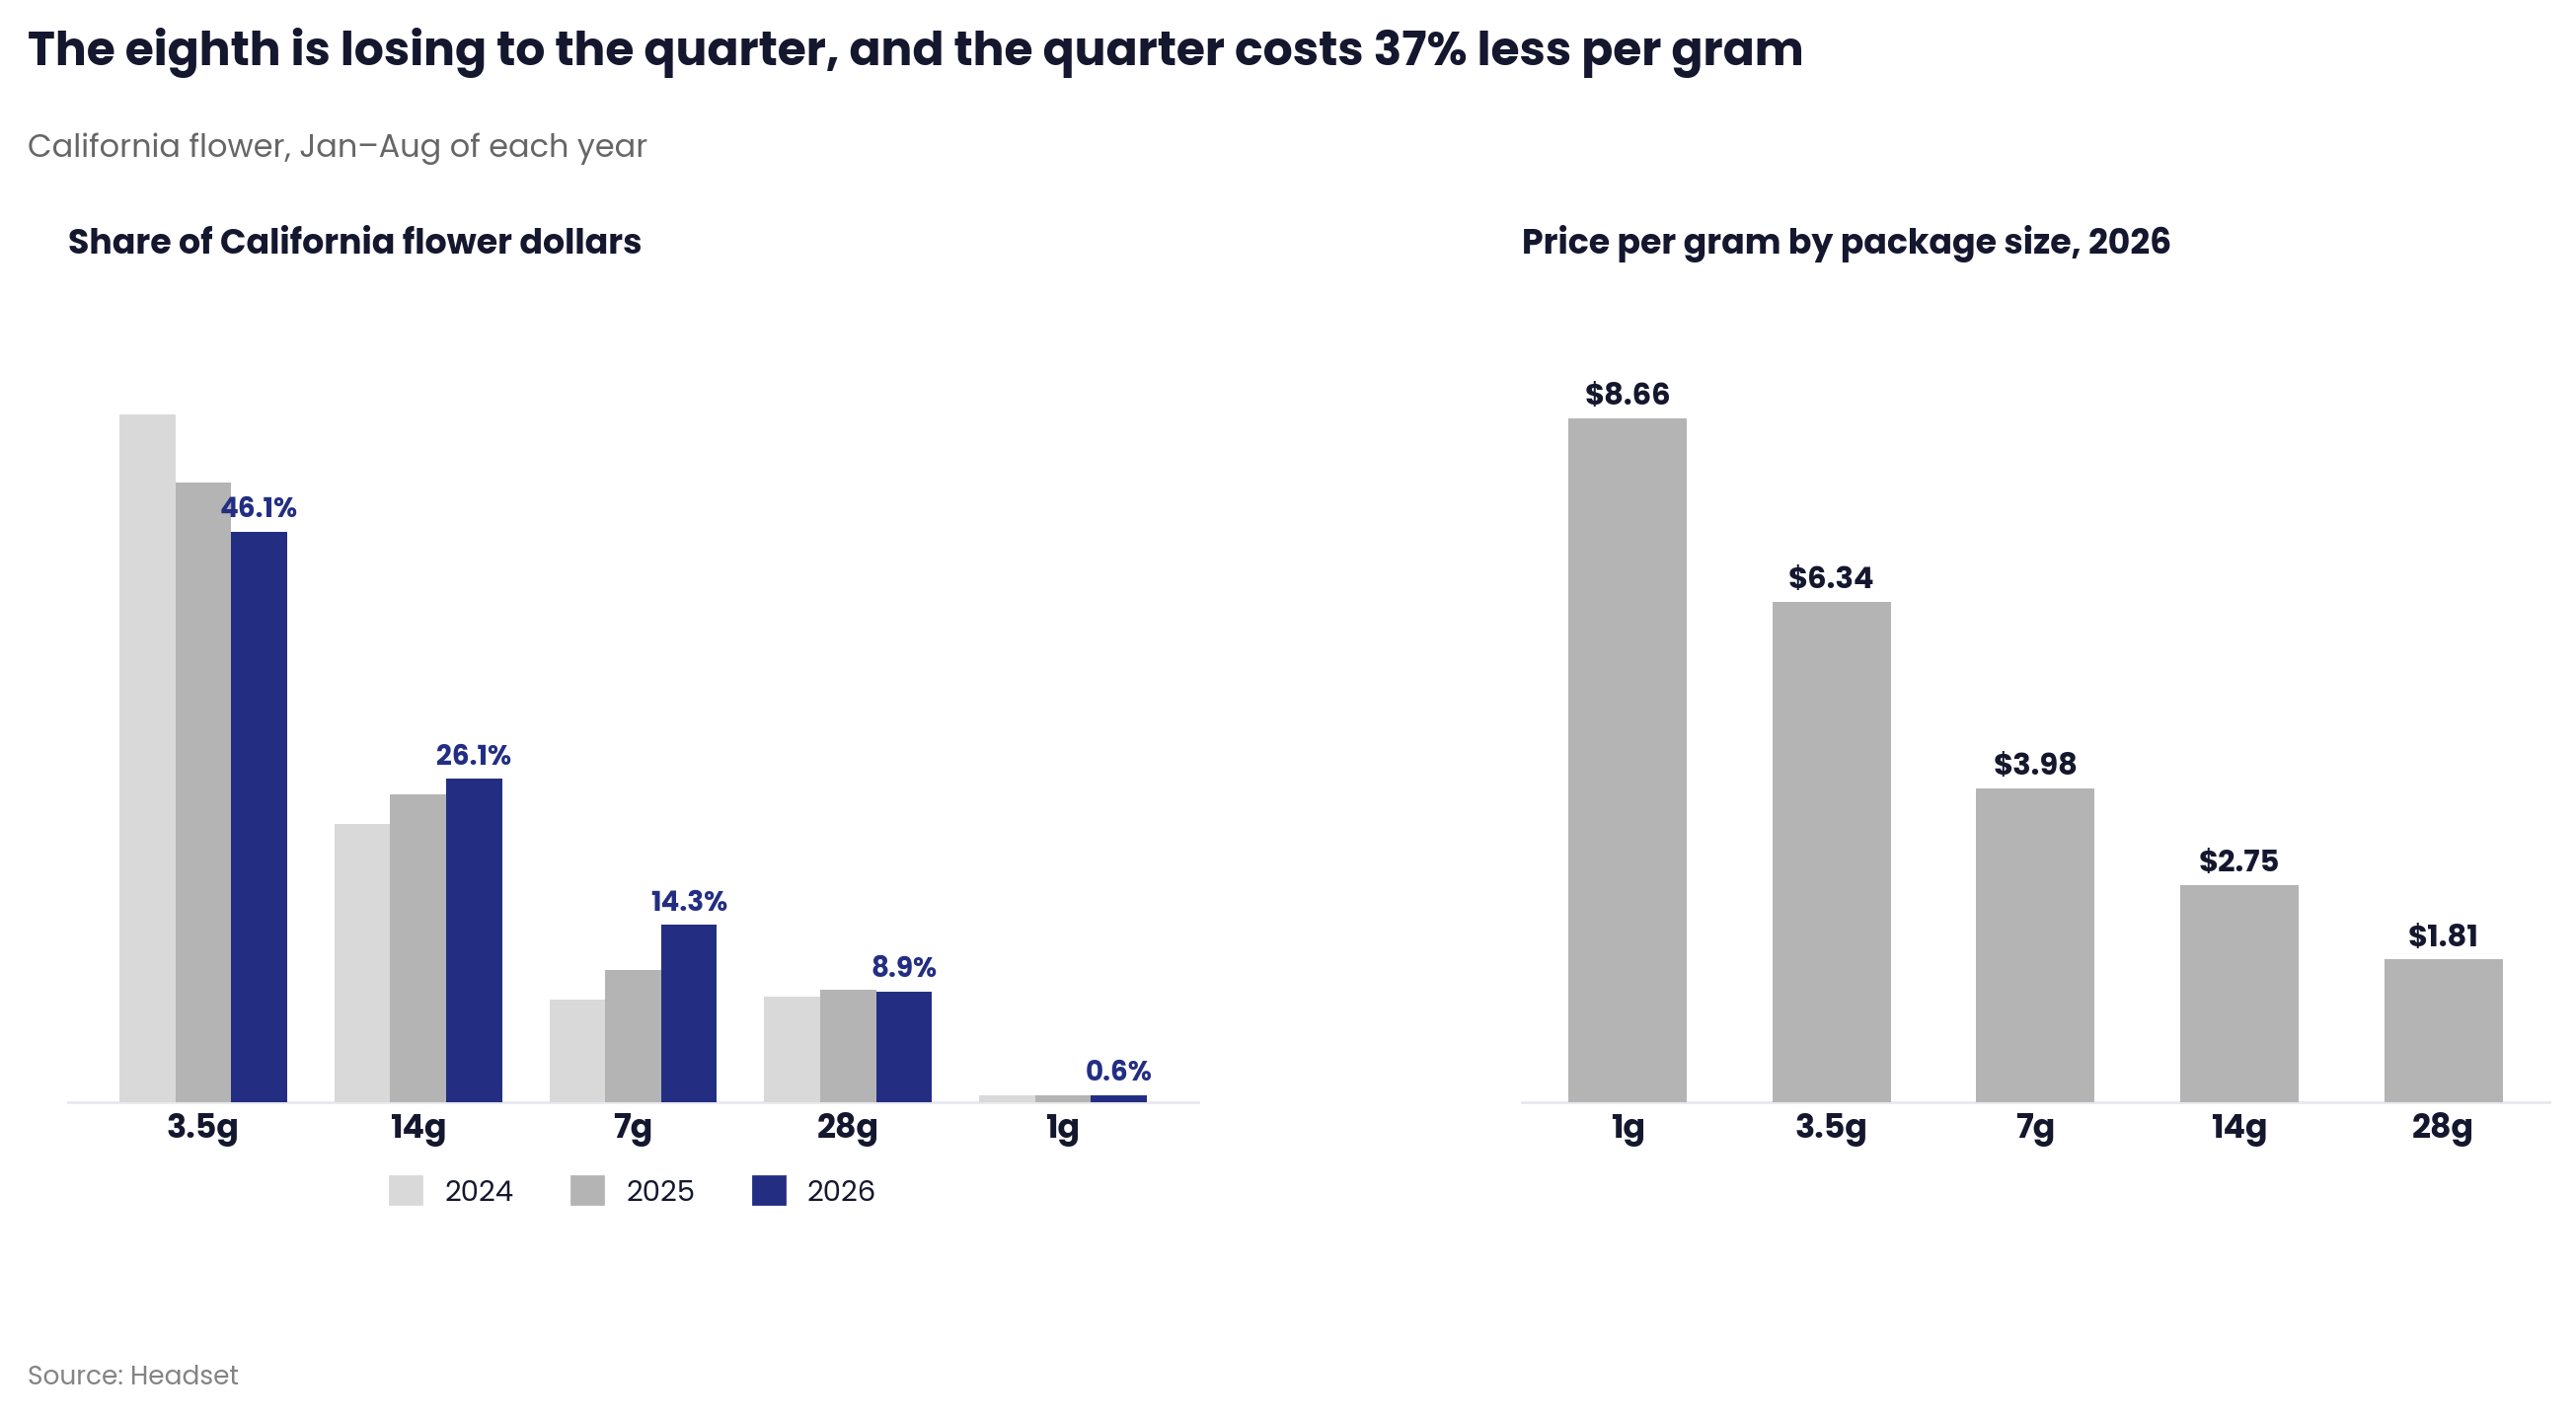
California flower fell from $4.62 per gram in 2024 to $3.79 in 2026, a decline of 18%. That is real, and it is the single largest drag on the state's dollar performance.
It is also, in large part, a format effect rather than a collapse in what flower is worth.
The eighth is losing. Its share of flower dollars fell from 55.5% in 2024 to 46.1% in 2026. The quarter is winning: the 7g tier went from 8.3% to 14.3% of dollars, nearly doubling in two years and adding more share than any other size. The 14g tier added another four points.
The per-gram column explains it. A California eighth sells for $6.34 per gram. A quarter sells for $3.98, 37% less. A half-ounce runs $2.75 and an ounce $1.81, which is 3.5 times cheaper than the eighth. Any price-aware consumer who can cover the larger up-front spend makes that jump, and in a market where units are growing and dollars are not, most of them are making it.
Headwinds
California's price compression has not stopped, and it is not evenly distributed. Flower is falling at roughly 9.5% per gram in each of the last two years, and pre-roll deflation accelerated from 5.5% to 9% both categories where 2026's unit growth is still absorbing a shrinking price rather than adding to the top line.
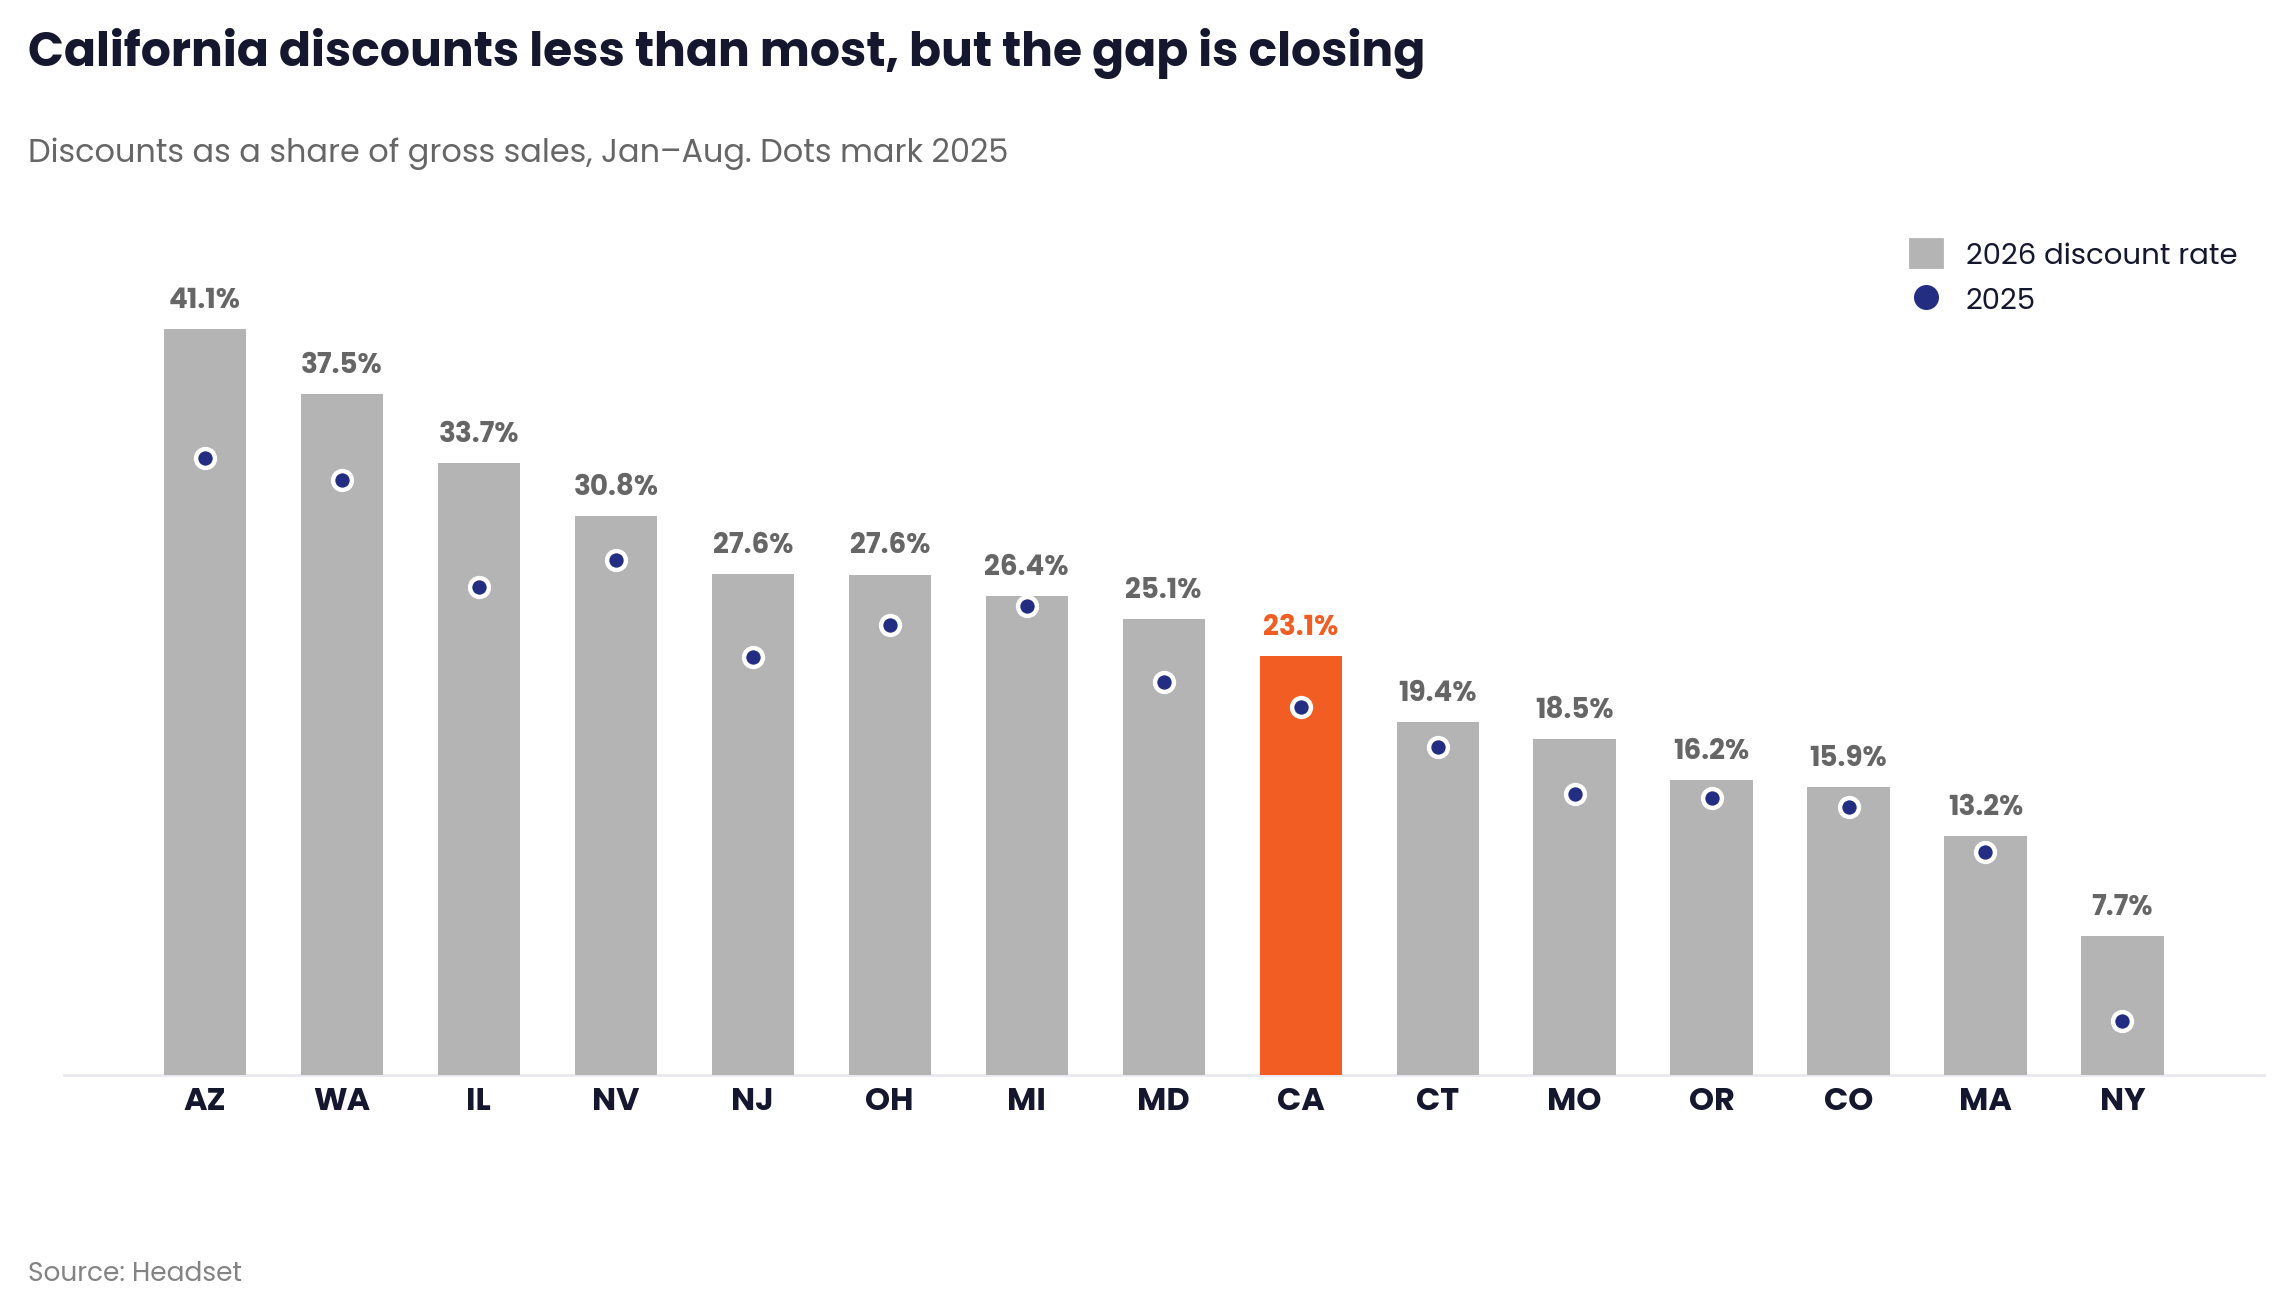
California discounts less than most, 23.1% of gross in the first eight months, leaner than Washington, Illinois, Nevada, and Michigan, heavier than Colorado, Oregon, and Massachusetts. But the rate rose 2.8 points this year, faster than most peers, and that matters more than the level: some of California's volume recovery is being bought, not earned, and the runway before promotion starts eating margin is shorter than it was a year ago.
Basket size is the other constraint. California averages 2.2 items and $40.67 per trip, among the lowest in the country and well behind Colorado's 3.0 and Michigan's 5.3 which make attachment one of the most underused lever operators have.
Competitive Landscape
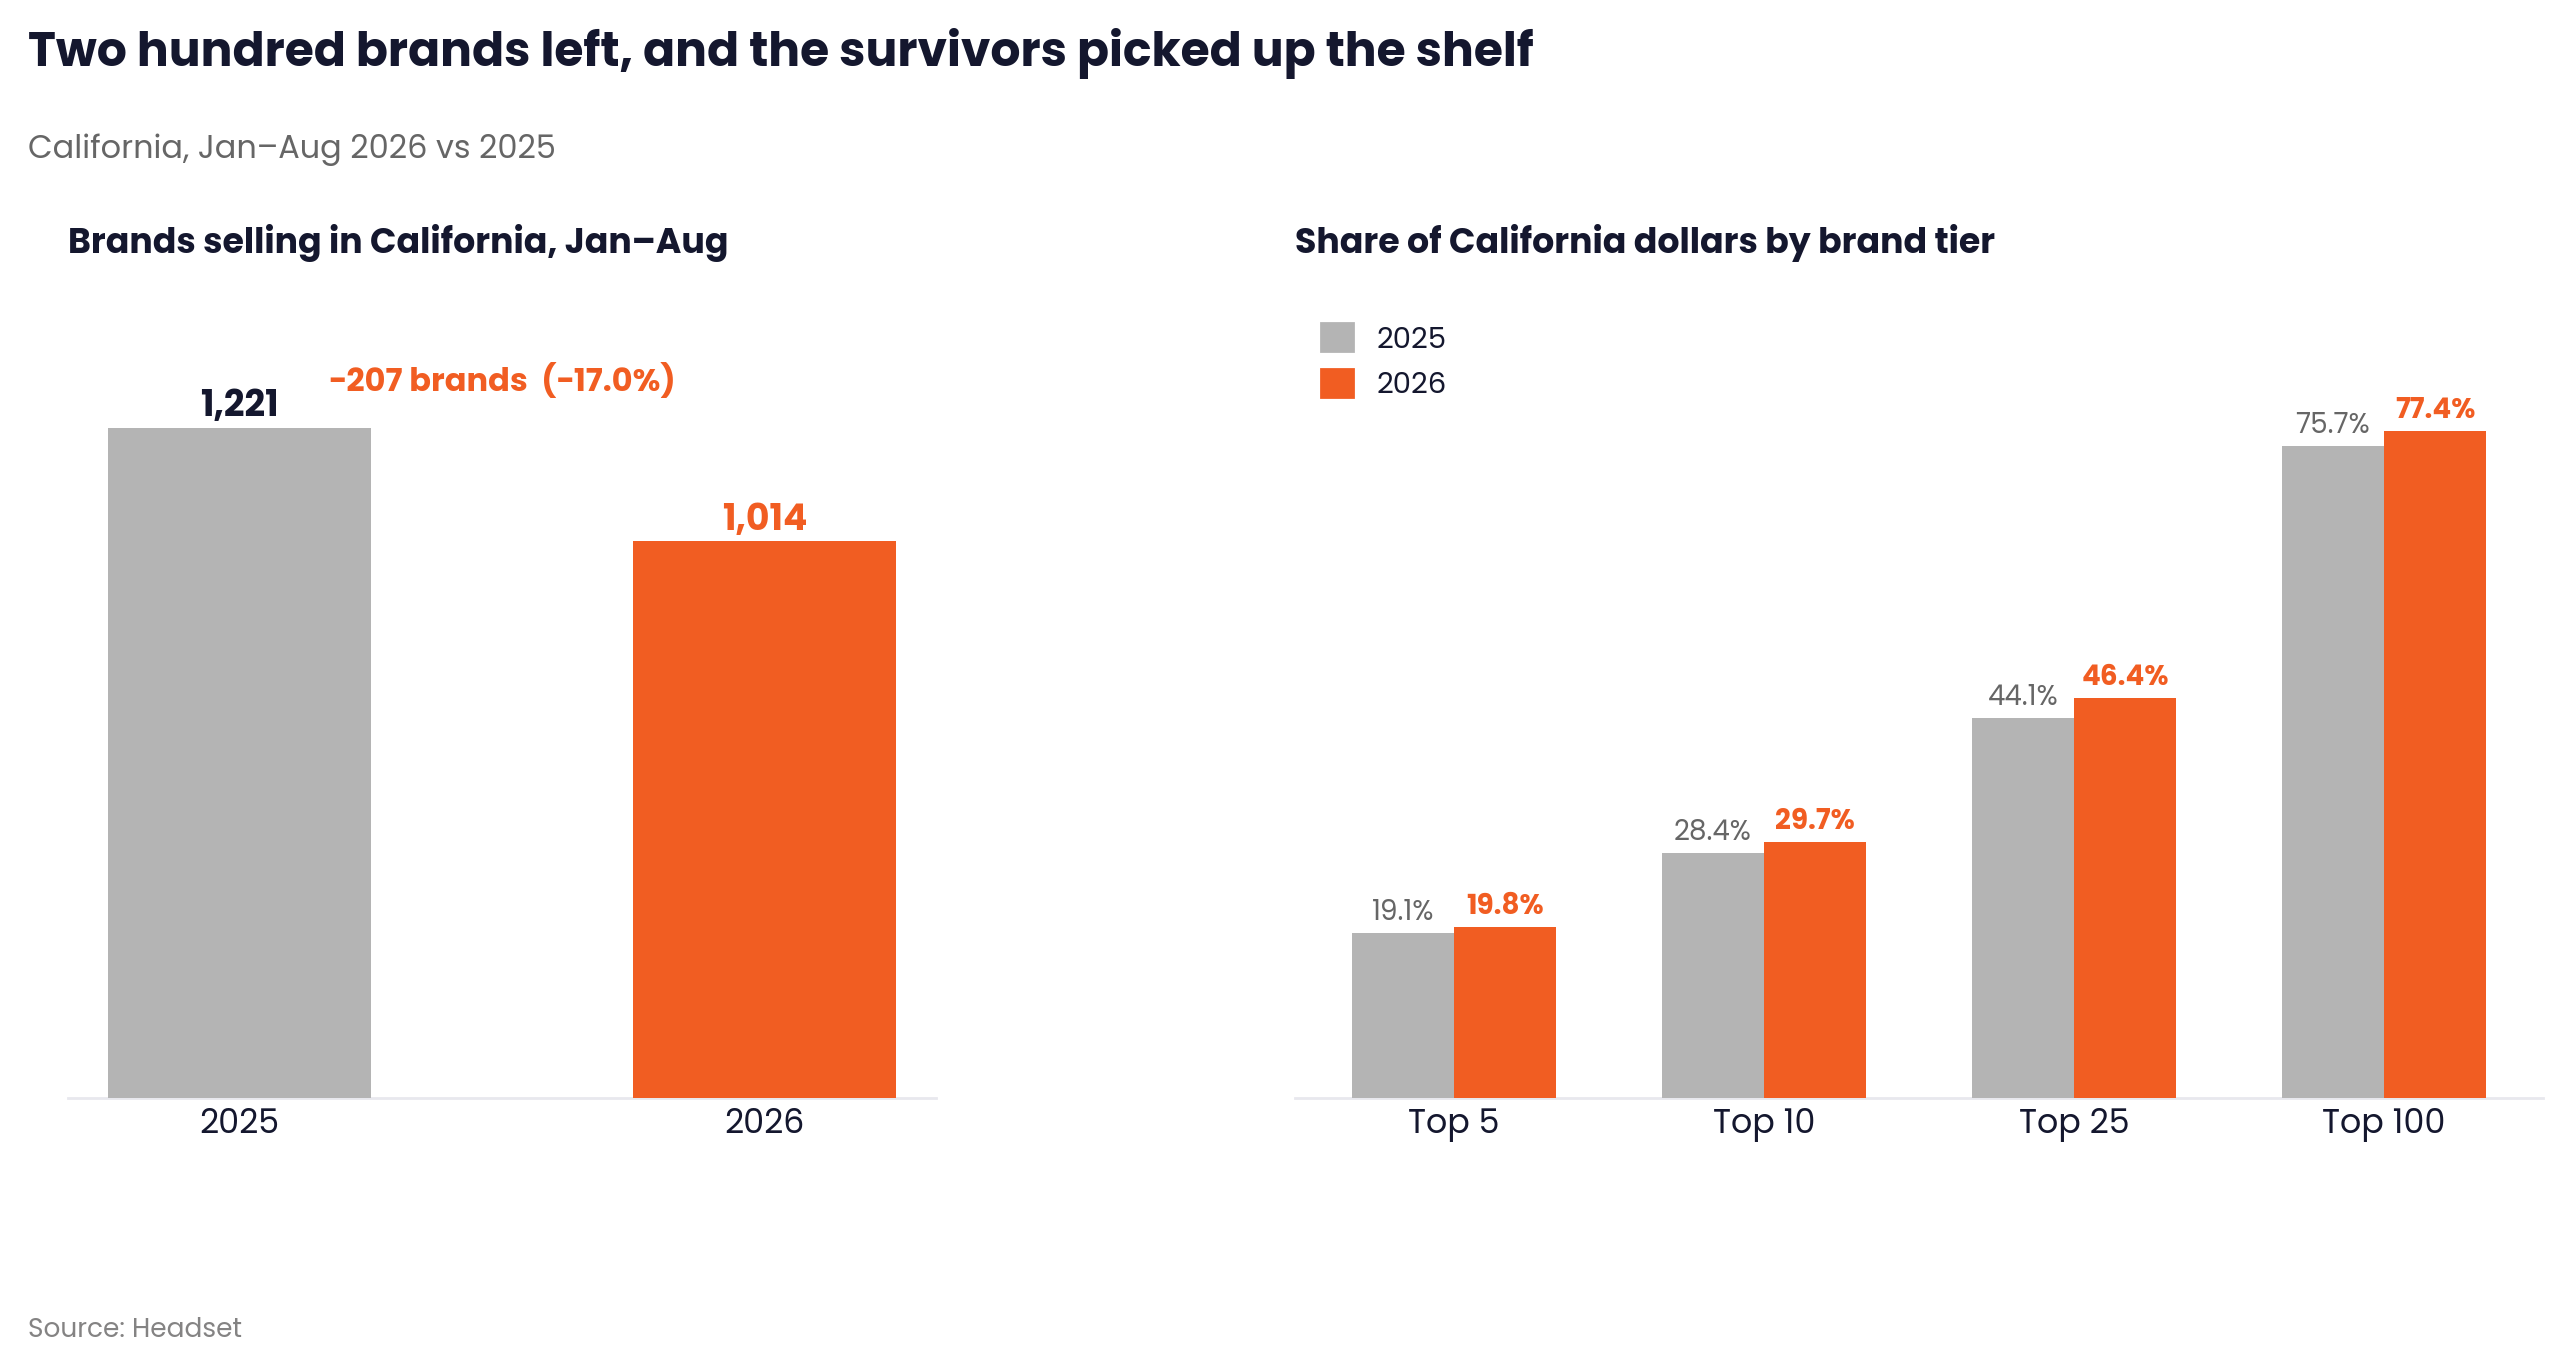
California supported 1,221 brands in the first eight months of 2025 and 1,014 in the same period of 2026. Two hundred and seven brands stopped selling, a 17% reduction, in a year when total market dollars did not move.
That thinning isn't reaching the top. STIIIZY still holds 8.4% of the state, more than two and a half times the next brand, and its own growth is relatively flat while its internal mix keeps rotating away from vapor pens toward flower. The share freed up by exiting brands is landing on the tier below it instead, where Jetty Extracts, CAM, Raw Garden, and Kingpen are all growing 15% to 56% on meaningful bases. For operators, that's the signal worth acting on: the incumbent isn't consolidating the market, and it isn't defending share aggressively enough to stop it from moving. California remains the market where a well-positioned product beats a big brand name, and the space just opened wider.
Conclusion
A market where sales struggle to grow is not an easy one to expand in, and prices falling, discounts rising, and the shelf consolidating don't make it easier. But the opportunity is real. As the largest cannabis market in the world, being early to a consumer shift pays off here at a scale most states can't match.
Four straight months of sales growth, on stabilizing prices, give operators room to work with, and that room is opening fastest in beverage, pre-roll, and vapor pens, the same categories a growing Gen Z cohort is pulling dollars into while every other generation pulls back. The risk sits in the same data: discounting is still climbing, and if it keeps outpacing volume growth, the recovery gets bought rather than earned. California's opportunity favors operators who act on that now, not the ones waiting for the market to settle.
