

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Hi5 Seltzer is stocked at 160 licensed dispensaries across Massachusetts, Maine, and 4 other states, 101 of them in Massachusetts, with the deepest coverage in Boston, Worcester, Abington, Newton, and Quincy. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
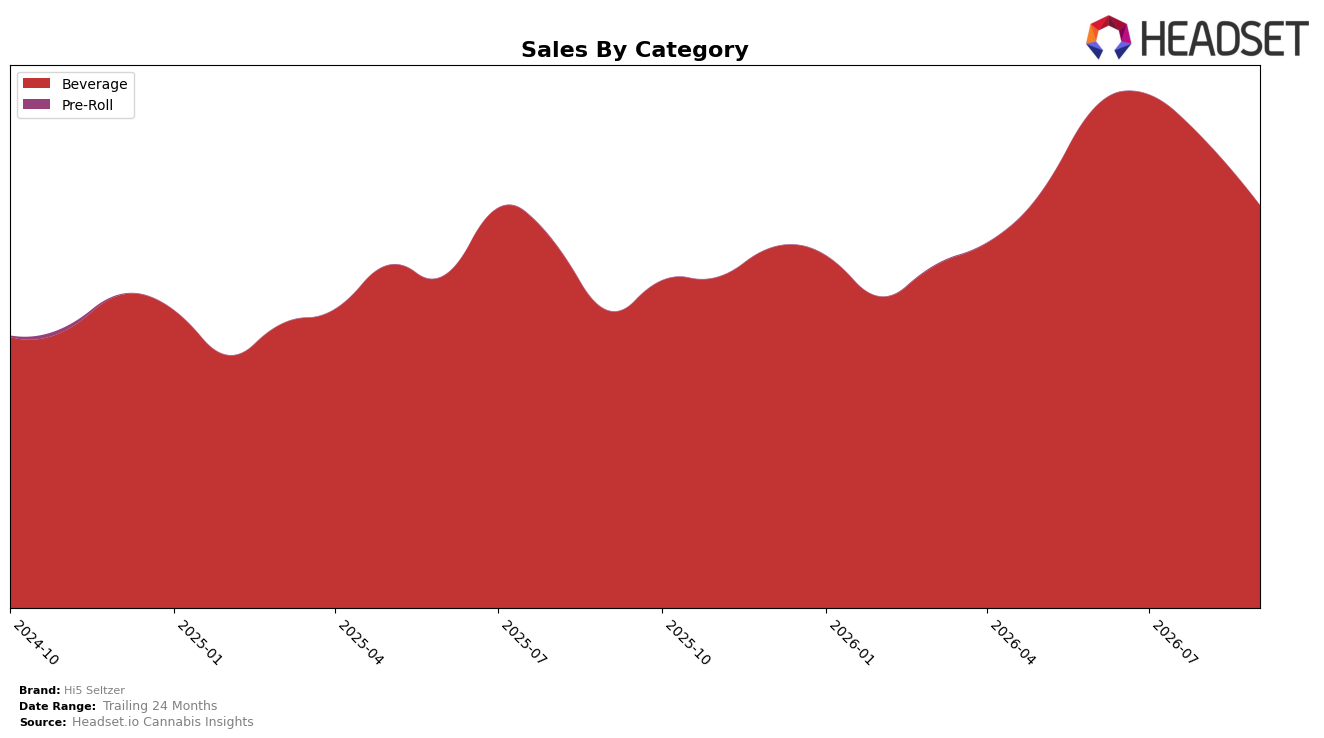
In September 2026, Hi5 Seltzer operated entirely within Beverage, with category share at 100.0% and average price at $11.09; year over year, Beverage sales grew 35.5%, while month over month they declined 13.9%. Despite the -4.0% YoY shift in average price, the 35.5% YoY sales increase indicates volume gains, whereas the 13.9% MoM drop suggests a pullback after prior months’ sell-in; together, these moves imply a single-category concentration that amplified YoY momentum but heightened MoM volatility.
Positioning-wise, the brand’s rank at #2 in Beverage in Massachusetts alongside a 35.5% YoY sales lift and a 13.9% MoM decline signals price elasticity working in favor of share capture over longer periods, but with short-term sensitivity to resets or promotions. With a 100.0% category concentration and a -4.0% YoY average price change, the pattern implies Hi5 Seltzer is trading price for sustained volume gains while relying on a single category for competitive standing, which can support rank defense at #2 yet exposes the brand to sharper MoM swings if Beverage demand softens.
Competitive Landscape
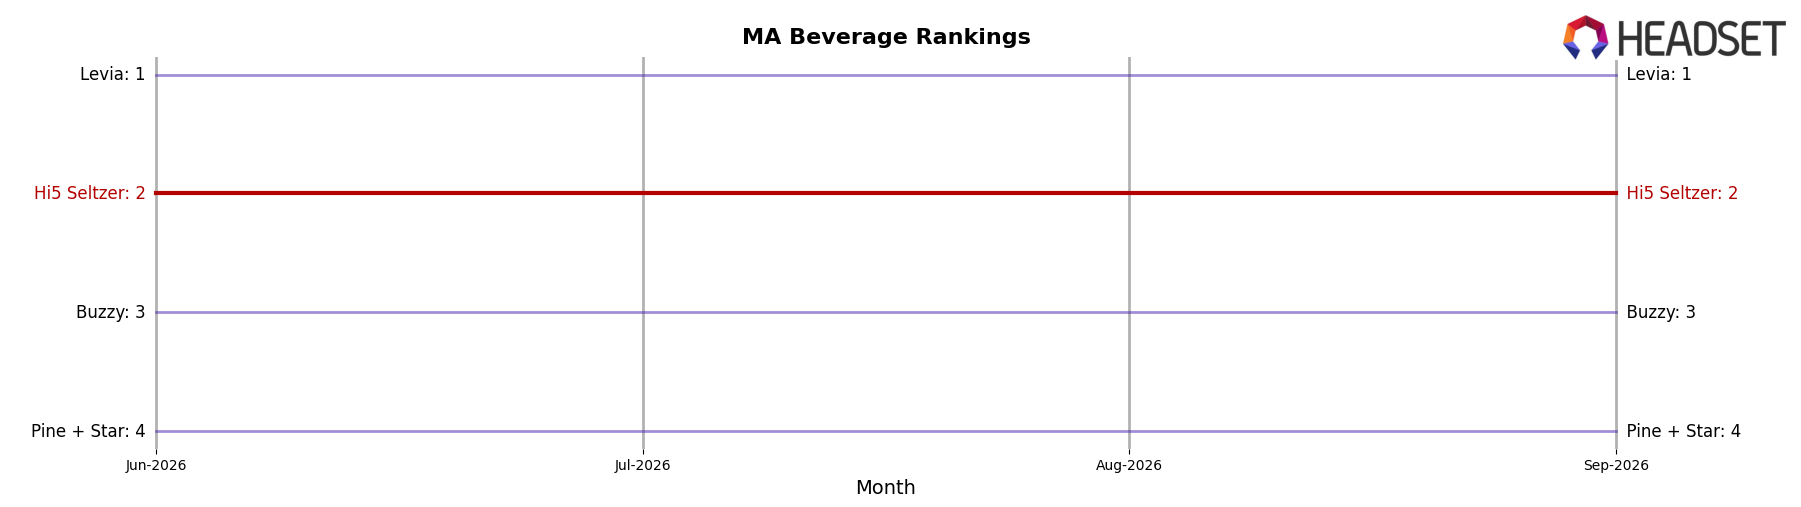
Hi5 Seltzer is ranked #2 in MA Beverage in September 2026, unchanged from #2 year over year, after peaking at #1 in March 2026 and holding #2 across the last three months, while category momentum around rivals widened: Levia held #1 year over year with an 18.6% YoY sales increase, and Pine + Star improved from #5 to #4 with a 9.8% YoY lift, whereas Chill Medicated slipped from #4 to #5 with a -22.2% decline; the flat #2 rank and prior #1 peak imply Hi5 Seltzer is defending a top-tier position but ceding incremental share to a faster-growing #1 and an advancing mid-pack competitor.
Notable Products
Cranberry Lime Infused Seltzer 4-Pack (20mg THC, 355ml) posted the steepest decline in September 2026 at -21.6% and slid to rank 3, while Black Cherry Infused Seltzer 4-Pack (20mg) fell -18.2% at rank 1, signaling share pressure at the top of the lineup. Blueberry Lemonade Seltzer 4-Pack (20mg, 12oz, 355ml) was the lone climber at +8.8% in rank 2, contrasted by Pomegranate Seltzer 4-Pack (20mg, 12oz, 355ml) down -19.8% at rank 10, and five of the top ten are 20mg 4-Pack SKUs, concentrating volume in higher-dose multi-packs. America Seltzer 4-Pack (20mg THC, 12oz) also contracted -11.1% at rank 9 while Watermelon Seltzer 4-Pack (20mg, 12oz, 355ml) declined -11.9% at rank 5, with the lower-dose singles clustered at ranks 6–8 and two of those lacking month-over-month reads, implying newer or less-repeat segments.
With seven Beverage entries in the top ten and one 20mg 4-Pack likely still clearing around $24,000 despite decline, the pattern points to reliance on a few flagship multi-packs whose negative momentum in September 2026 suggests a need to defend core flavors while testing 5mg formats for incremental reach.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

