

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
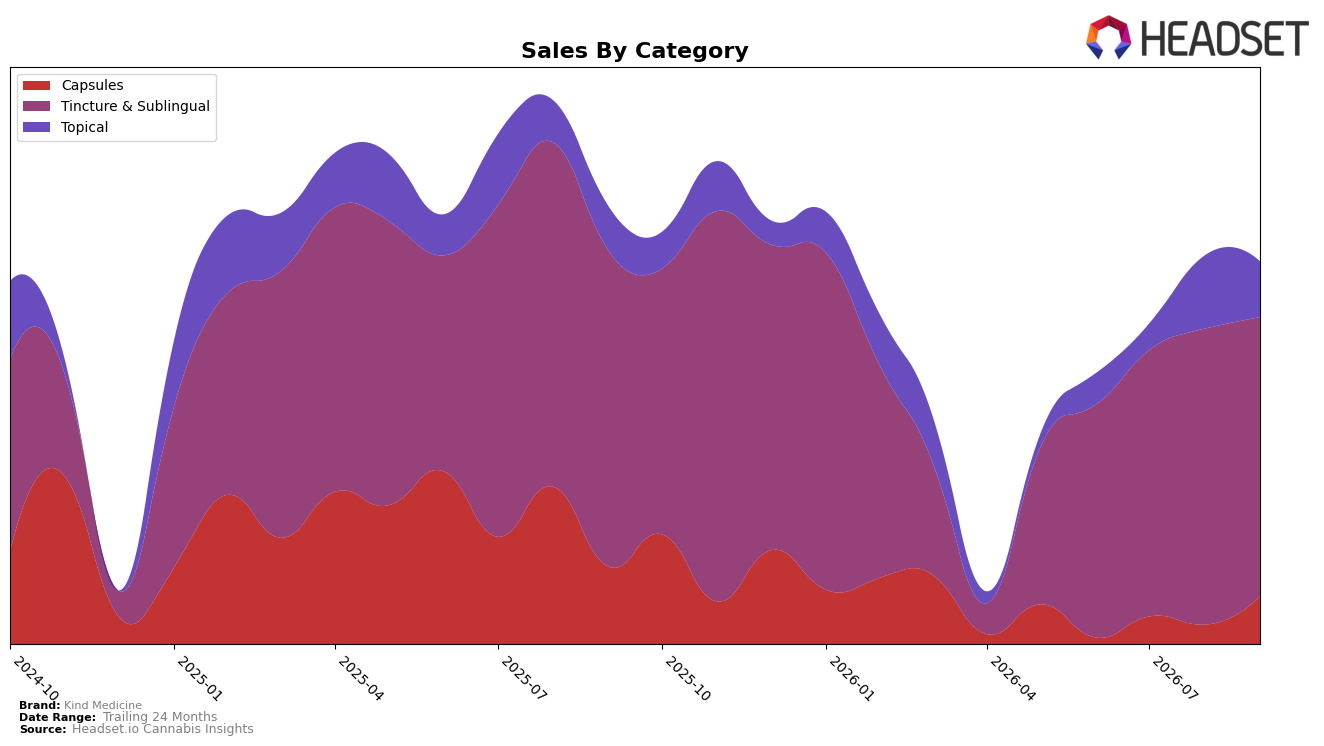
In September 2026, Kind Medicine concentrated 72.19% of sales in Tincture & Sublingual, where category sales fell 11.60% year over year and 5.56% month over month, while the brand’s overall sales were down 12.45% year over year and average price rose 12.30%. Topical held 14.94% share with a 24.41% year-over-year increase but a 22.88% month-over-month decline, and Capsules captured 12.87% share with a 37.38% year-over-year drop but a 126.60% month-over-month surge; together these swings indicate a portfolio leaning on a contracting core while short-term momentum is rotating into Capsules despite higher average prices at $35.10.
The mix shift implies Kind Medicine is trading depth for breadth: reliance on Tincture & Sublingual keeps the brand anchored at rank 19 in California, but the 126.60% month-over-month rebound in Capsules alongside a 22.88% month-over-month pullback in Topical suggests demand is consolidating into faster-replenish formats even as Tincture & Sublingual contracts 5.56% month over month. With average prices up 12.30% year over year and Capsules priced 18.5% above the brand average, maintaining share gains will likely require balancing premium price points against the 11.60% year-over-year decline in the core category to avoid further erosion of the 72.19% sales base.
Competitive Landscape
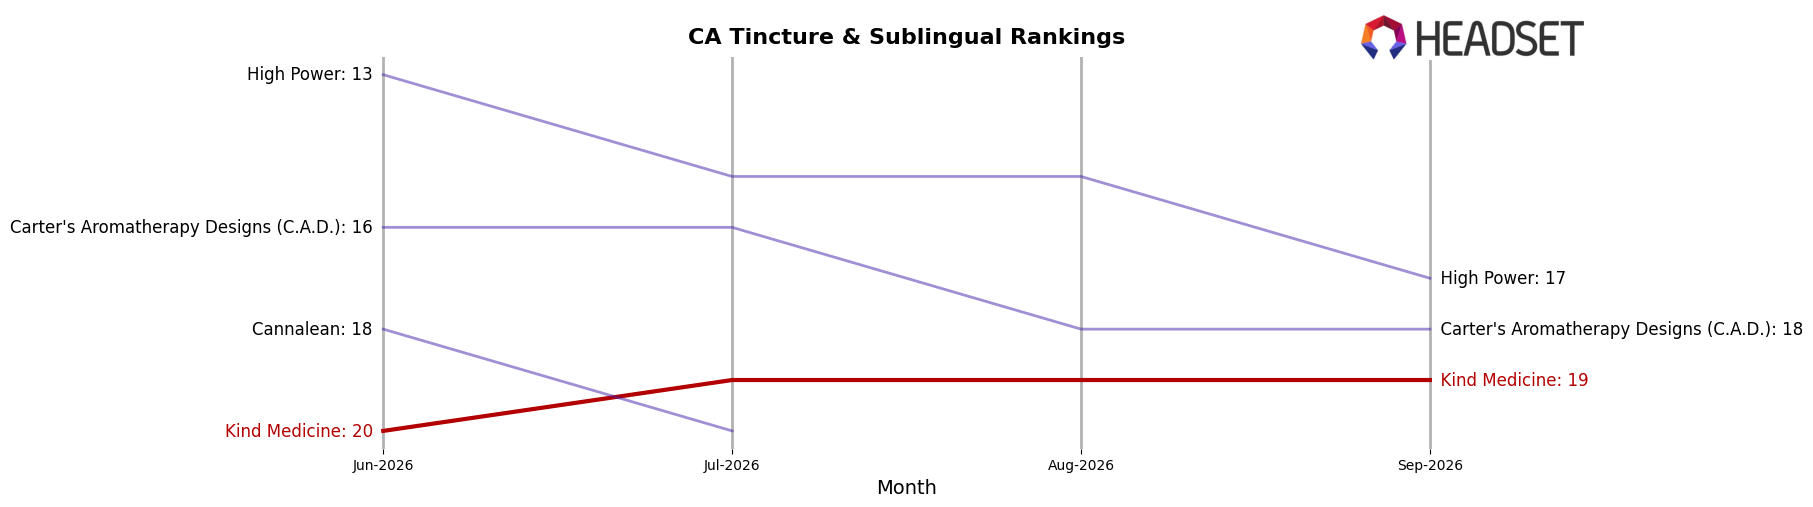
Kind Medicine sits at rank #19 in California Tincture & Sublingual for September 2026, unchanged year over year from #19, and up 1 place from June 2026 when it held #20; this stability contrasts with Mary's Medicinals climbing from #7 to #5 alongside a 22.27% YoY sales gain, while Care By Design held at #3 despite a 23.86% YoY sales decline. The brand remains two positions below its peak of #17 from April 2025 and one position behind its three-month mark of #20, whereas Papa & Barkley stayed #1 with an 8.39% YoY sales contraction and Yummi Karma remained #2 with a 7.82% YoY increase; this pattern implies Kind Medicine’s flat ranking masks mixed momentum above it, suggesting that modest share gains will require outpacing incumbents that are either retaining rank through scale or advancing despite volatility.
Notable Products
CBD/THC 25:1 Pet Tincture (500mg CBD, 20mg THC, 30ml) posted the largest month-over-month surge at 219.8% and climbed to rank 2, while Menthol Formula Rub (150mg THC, 50ml) fell 71.0% and slid to rank 5. Sativa Tincture (800mg THC, 30ml) in rank 1 grew 12.0% even as Indica Tincture (800mg THC,30ml) contracted 46.2% from a shared rank 3 position, indicating diverging consumer momentum within core THC tinctures. Four of the top ten are Tincture & Sublingual SKUs, and Indica Capsules 32-Pack (960mg) advanced 58.2% into rank 7 with $1,691 in September 2026 sales, signaling that pet use and dose-convenient formats are expanding the addressable base faster than legacy indica tinctures.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

