

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Select is stocked at 958 licensed dispensaries across New York, Illinois, and 19 other states, 191 of them in New York, with the deepest coverage in New York, Brooklyn, Queens, Staten Island, and The Bronx. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
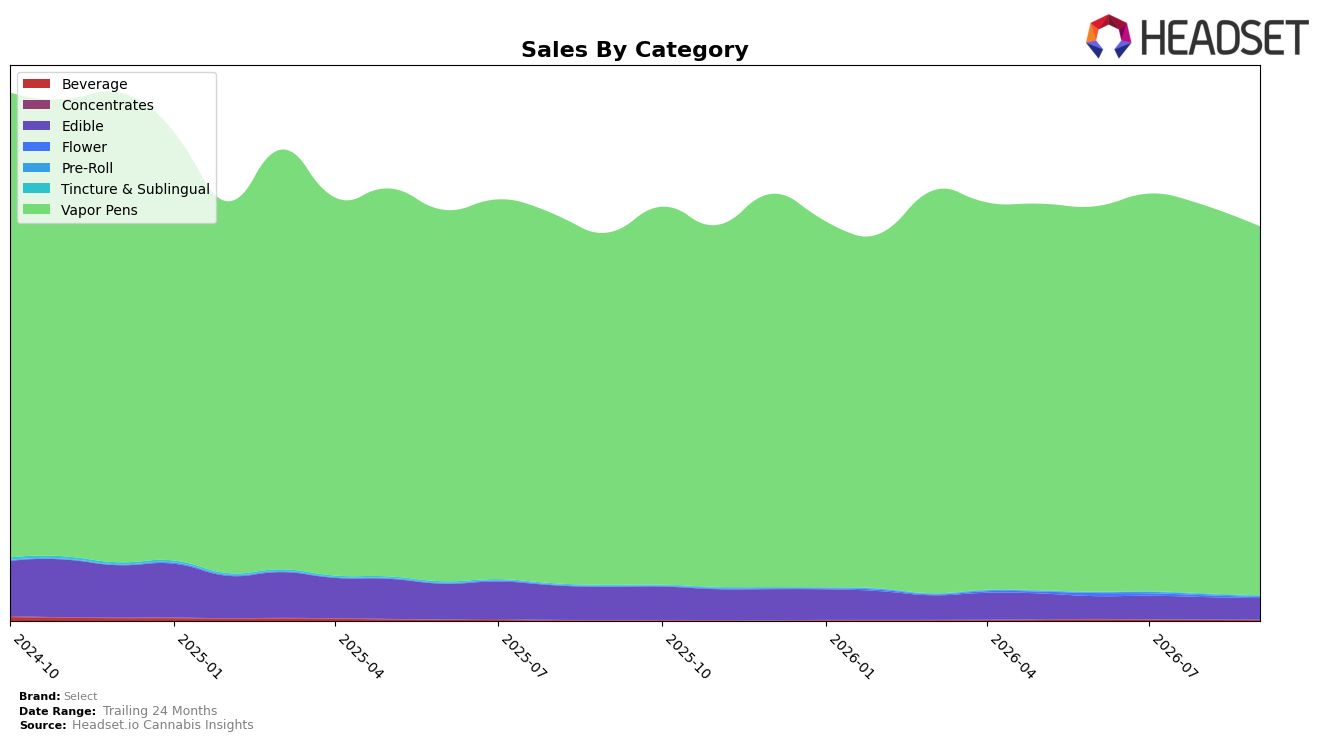
In September 2026, Select’s mix remained concentrated in Vapor Pens at 94.07% share with a 4.73% year-over-year increase but a 4.92% month-over-month decline, while Edible held 5.41% share with a 34.95% year-over-year drop and a 3.62% month-over-month decline. Smaller lines were volatile: Flower posted a 395.12% year-over-year gain but fell 47.51% month-over-month to just 0.19% share, Beverage rose 69.51% year-over-year but slipped 26.98% month-over-month to 0.17% share, and Pre-Roll spiked 3,498.47% year-over-year yet contracted 43.14% month-over-month at 0.10% share; Tincture & Sublingual declined 57.40% year-over-year but grew 7.13% month-over-month at 0.07% share. With overall brand sales up 1.58% year-over-year alongside a 2.09% decline in average price and a category rank of 1 in Vapor Pens in Connecticut, the pattern implies a reliance on a single engine where modest price compression supports share but month-over-month softness in the core limits total growth.
The shifts imply Select is doubling down on Vapor Pens leadership—reinforced by a number 1 rank in Connecticut—while peripheral categories act as tactical tests rather than scale plays, given sub-1% shares and double-digit month-over-month pullbacks of 26.98% to 47.51% across Beverage, Flower, and Pre-Roll. The 7.13% month-over-month uptick in Tincture & Sublingual against a 57.40% year-over-year decline signals selective SKU pruning and price-positioning adjustments, consistent with a 2.09% average price decrease and a 10.57% 24-month sales contraction. This mix, paired with a 4.92% month-over-month contraction in the dominant Vapor Pens line and a 34.95% year-over-year erosion in Edible, implies the brand’s positioning is concentrated around maintaining top-tier Vapor Pens placement while using targeted, low-risk experimentation in adjacent formats to hedge without diluting focus.
Competitive Landscape
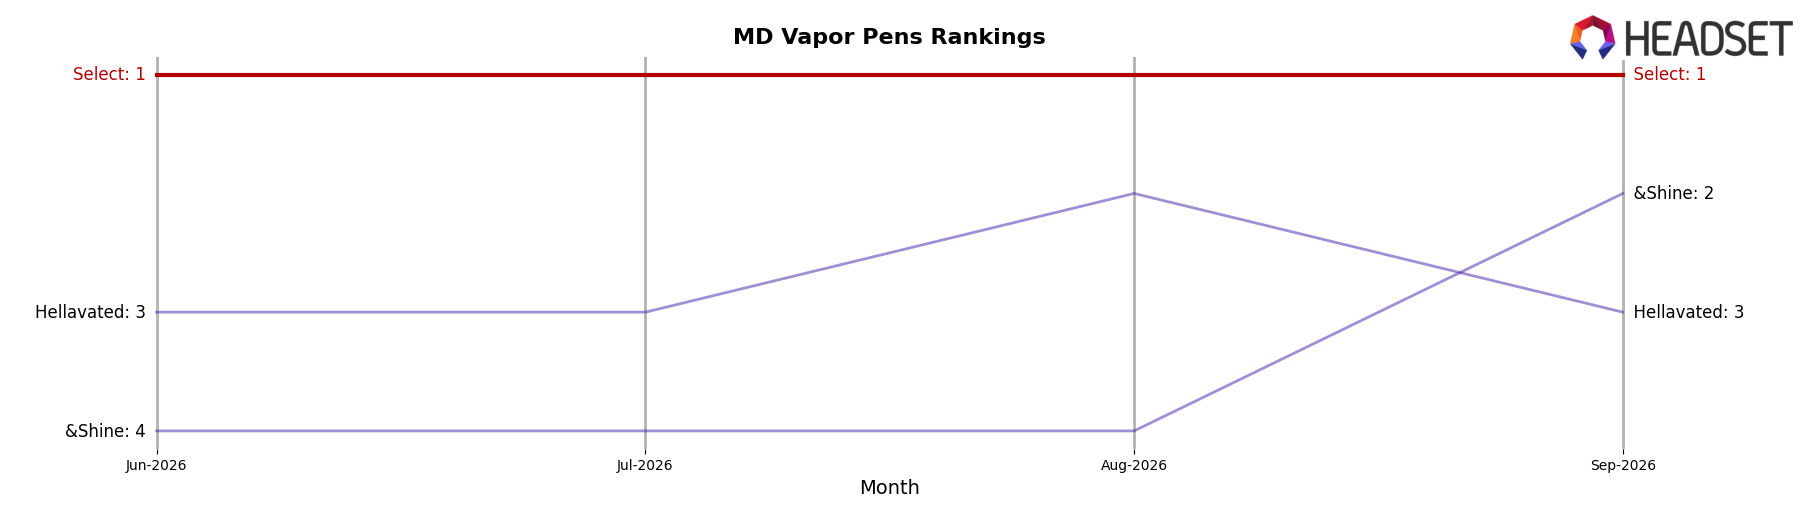
Select holds rank #1 in MD Vapor Pens in September 2026, unchanged from rank #1 in September 2025, and it also stayed #1 over the last three months, which indicates stable category control while the field churned beneath it. Competitively, Hellavated climbed from #4 to #3 with a 13.6% YoY sales increase while RYTHM slipped from #3 to #4 despite a 0.5% YoY gain, and Rove jumped from #8 to #5 on 121.3% YoY growth, contrasting with &Shine holding #2 with 5.1% YoY growth; this mix of upward mobility and rank stability implies Select’s unchanged #1 is being preserved more by consistent lead maintenance than by category-wide softness, and that continued pressure is most likely from fast risers like Rove rather than steady #2 incumbents like &Shine.
Notable Products
Classic Bites - Blueberry Gummies 10-Pack (100mg) posted the steepest decline at -13.9% and slid to rank 5, while Essentials Briq - Baja Smash BDT Distillate Disposable (2g) rose 7.2% to hold rank 3. The category skew is clear with eight of the top ten in Vapor Pens, led by Legacy Series Briq 2 - Blue Dream Distillate Disposable (2g) at rank 1 despite a -1.6% MoM dip and Essentials Briq - Pineapple Express BDT Distillate Disposable (2g) at rank 2 with -6.2%. Guava Melon Infused Pre-Roll (1g) fell -47.8% at rank 7, reinforcing that non-pen formats are losing share against stable pen SKUs that posted small positive moves of 1.2% to 7.2%. The pattern implies Select is consolidating around 2g Vapor Pens as the commercial core, with edibles and pre-rolls requiring repositioning to avoid further rank erosion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

