
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Super Wow is stocked at 15 licensed dispensaries across California, with the deepest coverage in Santa Rosa, Adelanto, Arnold, Berkeley, and Cotati. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
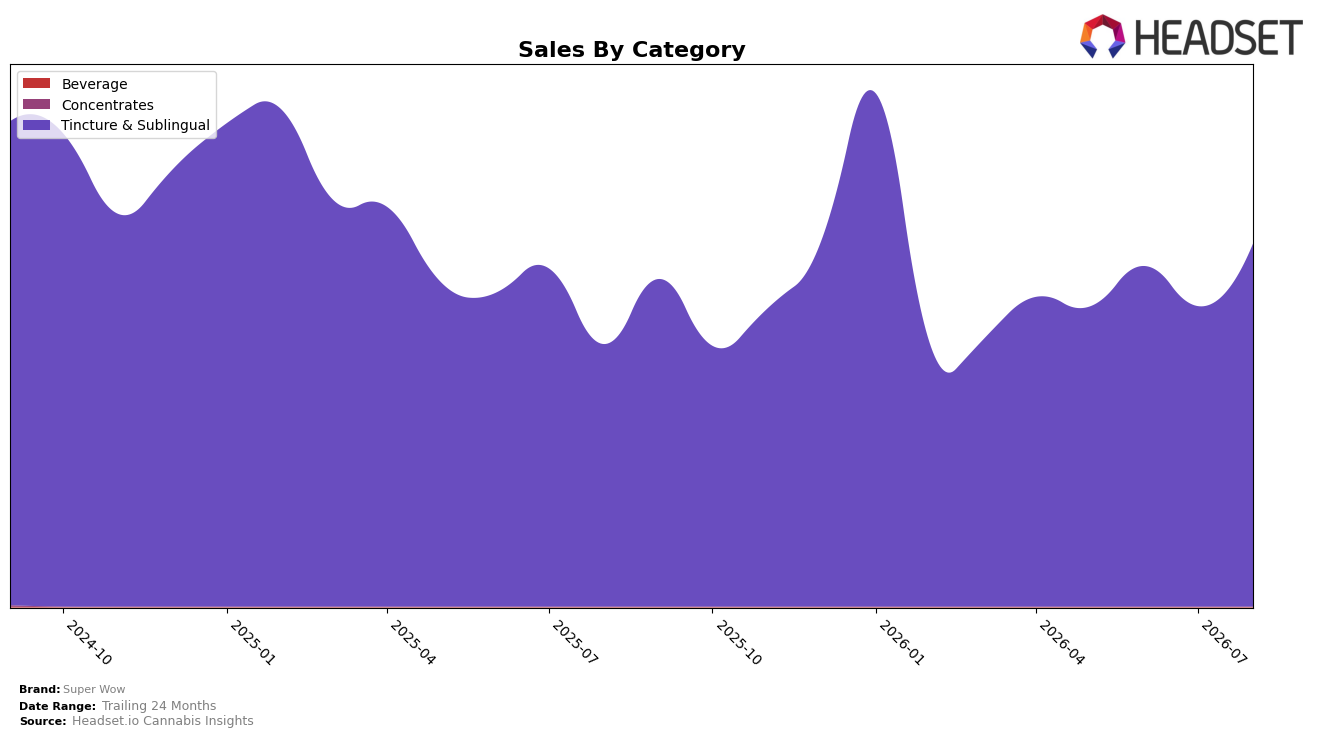
In August 2026, Super Wow concentrated entirely in Tincture & Sublingual with a 100.0% category share, pairing a 38.4% year-over-year sales increase with a 20.9% month-over-month lift. Average price declined 2.8% year over year while the category rank in California held at 13, indicating unit-led momentum despite price compression. The combination of a full-category focus and double-digit MoM and YoY gains implies the brand is leaning into depth over breadth, using price elasticity within Tincture & Sublingual to convert demand without expanding into adjacent categories.
Sustained single-category exposure at rank 13 in California alongside 38.4% YoY growth and a 20.9% MoM rise suggests Super Wow is winning share locally through velocity rather than assortment expansion. With an average price down 2.8% YoY and 100.0% of sales tied to Tincture & Sublingual, the pattern implies a scale-through-specialization strategy where tactical price trims fuel unit growth while the current rank position leaves room for incremental gains from distribution or targeted premium SKUs.
Competitive Landscape
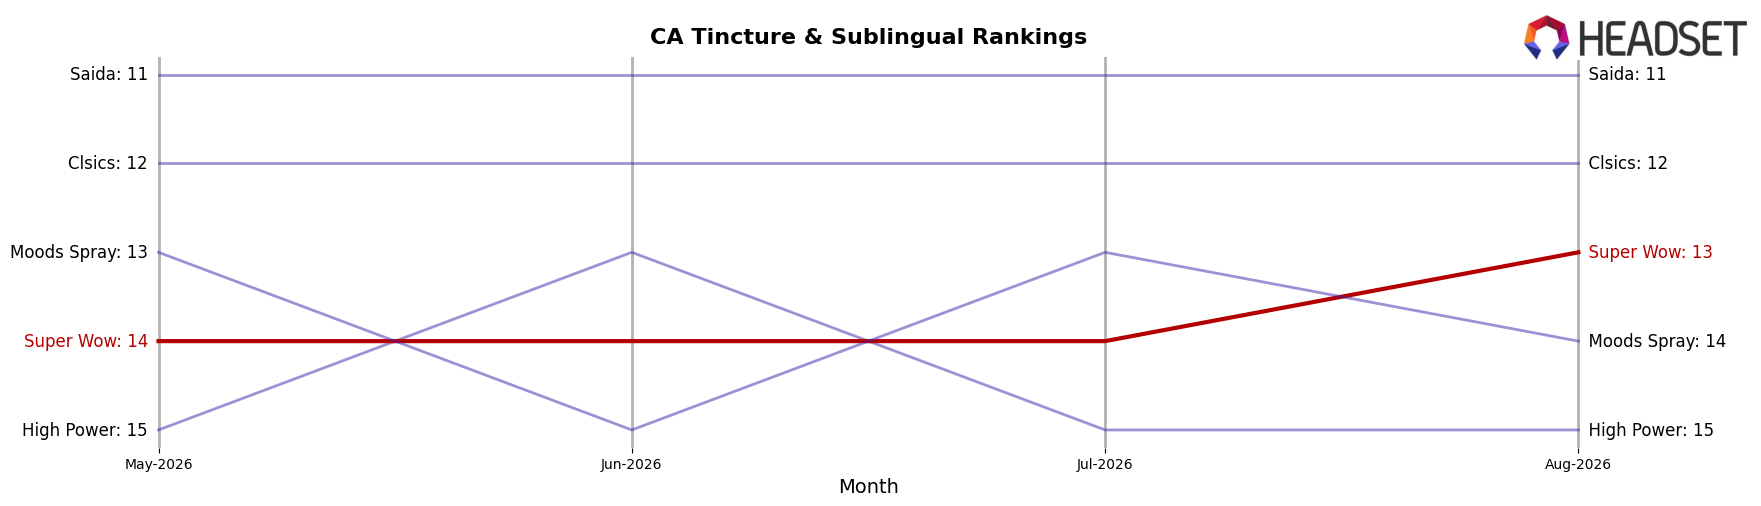
Super Wow sits at rank 13 in CA Tincture & Sublingual for August 2026, improving 1 position from rank 14 year over year, and it also moved up 1 spot versus three months ago from 14 to 13; however, this is still 2 places below its historical peak of rank 11 set in February 2025, indicating a recovery that has not yet matched prior highs. In contrast, Papa & Barkley held rank 1 both this year and last (0-position change) even as its sales fell 1.36% year over year, while Yummi Karma remained at rank 2 (0-position change) with a 15.09% sales increase year over year. This pattern implies that Super Wow’s marginal rank gain amid top-tier stability suggests incremental share capture is coming from mid-tier churn rather than displacement of entrenched leaders, pointing to a slow-momentum path that will require sharper differentiation to break into the top 10.
Notable Products
Pina Colada Drops Tincture (1000mg THC, 30ml) posted the largest movement in August 2026 with a 161.7% month-over-month gain to rank 6, while Watermelon Tincture (1000mg THC, 30ml) fell 36.5% to rank 5, indicating sharp divergence within the same lineup. Pink Lemonade Tincture (1000mg THC, 30ml) rose 83.5% to rank 1 and THC/CBN Sleepy Wow Tincture (1000mg THC, 30mg CBN, 30ml) climbed 89.4% to rank 2, whereas Blue Raspberry Drops Tincture (1000mg THC, 30ml) declined 23.9% at rank 4, with four of the top five SKUs in August 2026 coming from Tincture & Sublingual. With three SKUs surging more than 80% while two fell more than 20%, the pattern implies Super Wow is concentrating demand into a few winning tincture flavors and effects, signaling a pivot toward flavor-effect leaders rather than broad flavor parity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

