

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
ABX / AbsoluteXtracts is stocked at 344 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Francisco, Sacramento, San Jose, and San Diego. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
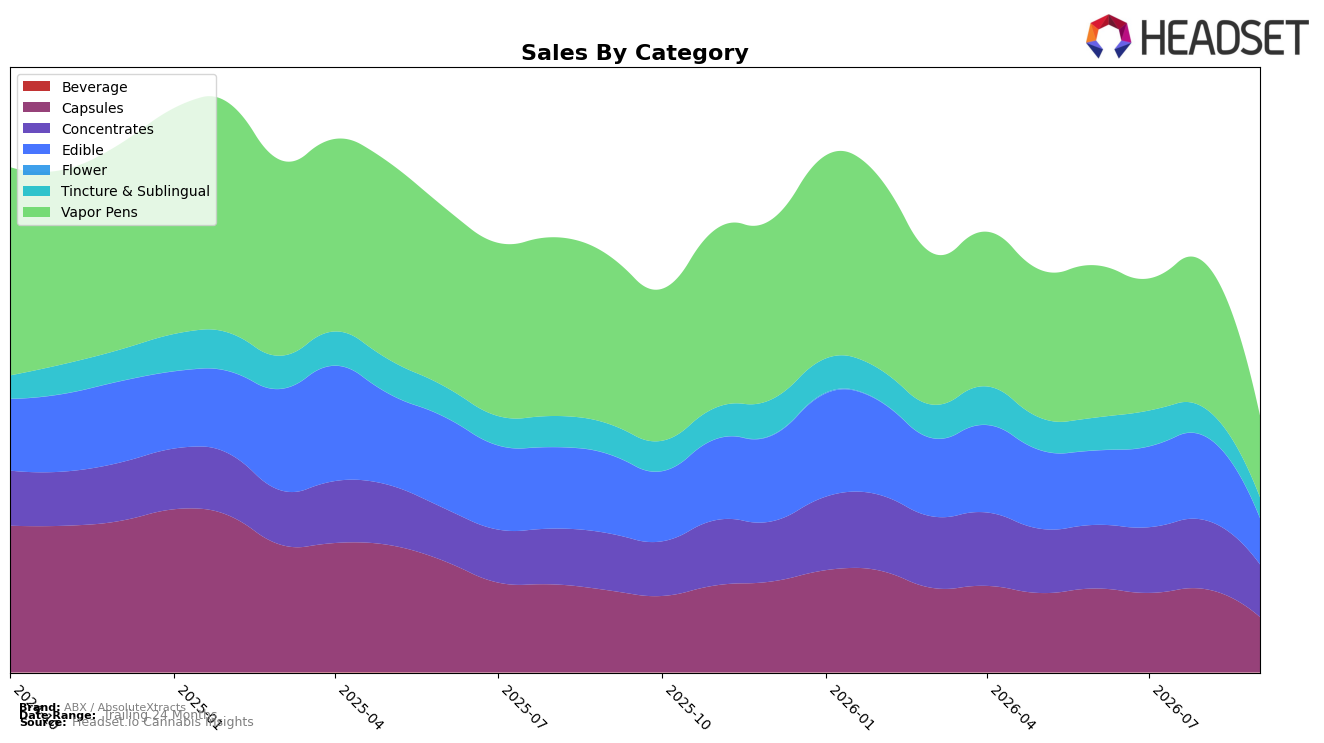
In September 2026, ABX / AbsoluteXtracts shifted toward a three-way split anchored by Vapor Pens at 31.85% share (year over year -51.68%, month over month -43.90%), Capsules at 21.58% share (year over year -32.67%, month over month -33.72%), and Concentrates at 20.53% share (year over year -7.74%, month over month -23.74%), while Edible held 18.03% share (year over year -41.62%, month over month -44.93%) and Tincture & Sublingual accounted for 8.01% share (year over year -31.76%, month over month -26.06%). With overall brand sales down 38.59% year over year and average price up 3.95%, the mix is moving away from historically larger, faster-declining segments toward the comparatively less-contracted Concentrates, implying intentional or market-driven rebalancing toward categories with smaller year-over-year erosion.
The mix and price moves reposition ABX / AbsoluteXtracts toward value-accessible potency and therapeutic formats: Concentrates’ smaller year-over-year decline of 7.74% versus Vapor Pens’ 51.68% and Edible’s 41.62% suggests demand resilience that can anchor share stability even as month-over-month declines remain broad. At a 43 rank in Vapor Pens within California and with an average price of $19.55 alongside category-level average prices of $25.83 for Vapor Pens and $16.09 for Concentrates, the pricing ladder indicates room to lean into Concentrates for velocity while using price-pack architecture in Vapor Pens to arrest share loss, implying that near-term positioning should prioritize Concentrates-led retention and targeted Vapor Pen price architecture to improve rank.
Competitive Landscape
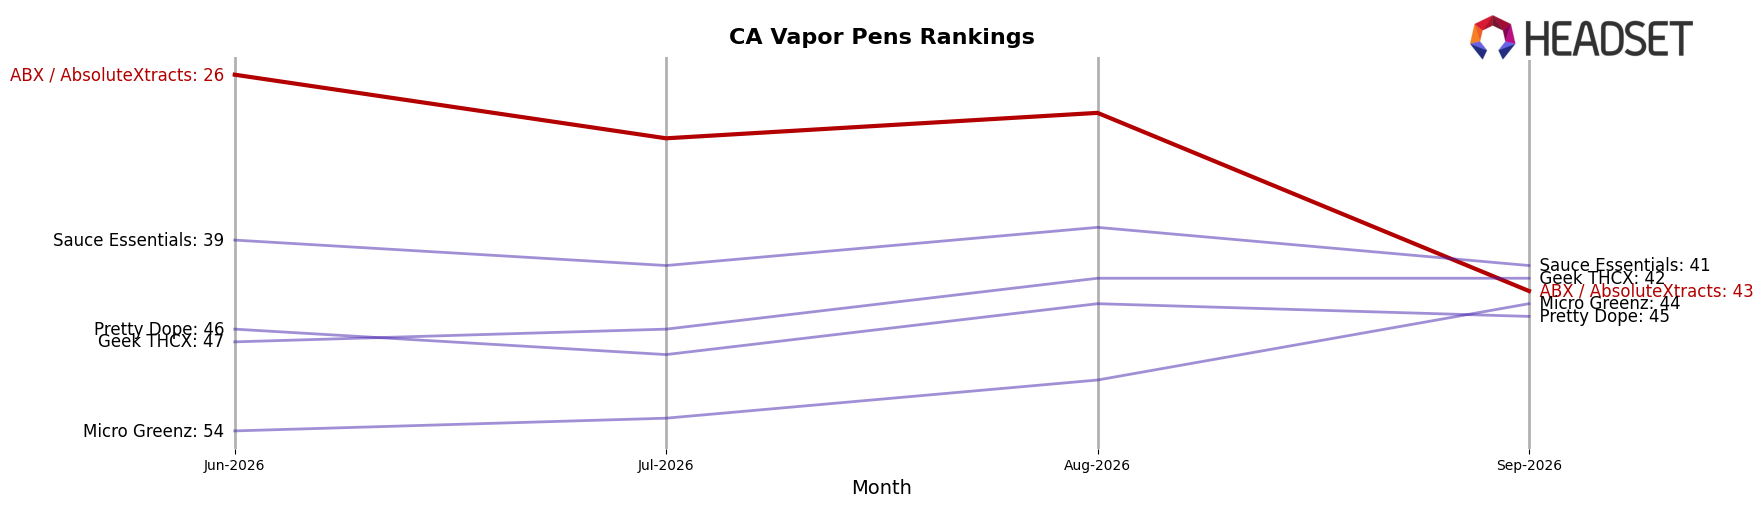
ABX / AbsoluteXtracts sits at rank #43 in California Vapor Pens in September 2026, down 21 positions from rank #22 year over year, and 17 spots below its June 2026 level at #26, indicating a multi-quarter slide from a peak of #18 reached in March 2025; meanwhile, STIIIZY held #1 both this year and last as its sales declined 16.7% year over year, and Jetty Extracts climbed from #4 to #3 with 45.2% YoY sales growth, widening the gap versus ABX / AbsoluteXtracts. The pattern implies ABX / AbsoluteXtracts is losing share to faster-rising incumbents at the top while also ceding mid-tier ground, making a return to the March 2025 peak unlikely without a mix or distribution reset.
Notable Products
Tangie Terp Chew 20-Pack (100mg) posted the steepest month-over-month drop at -62.3% while sliding to rank 7, and Forbidden Fruit Terp Chews 20-Pack (100mg) fell -56.2% at rank 6, signaling sharp compression in fruit-flavored Edibles. Sleepytime - THC/CBN 2:1 Elderberry Gummies 20-Pack (100mg THC, 50mg CBN) still held rank 1 despite a -33.6% decline, and CBN/THC 2:5 Blueberry Lavender Sleepy Time Gummies 20-Pack (40mg CBN, 100mg THC) at rank 2 dropped -22.6%, with six of the top ten being Edibles. The THC/CBN 2:1 Sleepy Time Tincture (500mg THC, 250mg CBN, 15ml) sat at rank 4 with a -26.3% MoM change while THC Hybrid Refresh Capsules 30-Pack (750mg) at rank 9 contracted -50.4%, indicating sleep-positioned formats are retrenching across both ingestible and sublingual forms. The pattern implies ABX / AbsoluteXtracts is overexposed to sleep and edible formats that are cycling down, pointing to a near-term need to rebalance toward fewer SKUs and higher-velocity form factors such as vapor pens, where rank 8 launched without a reported MoM decline.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

