
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
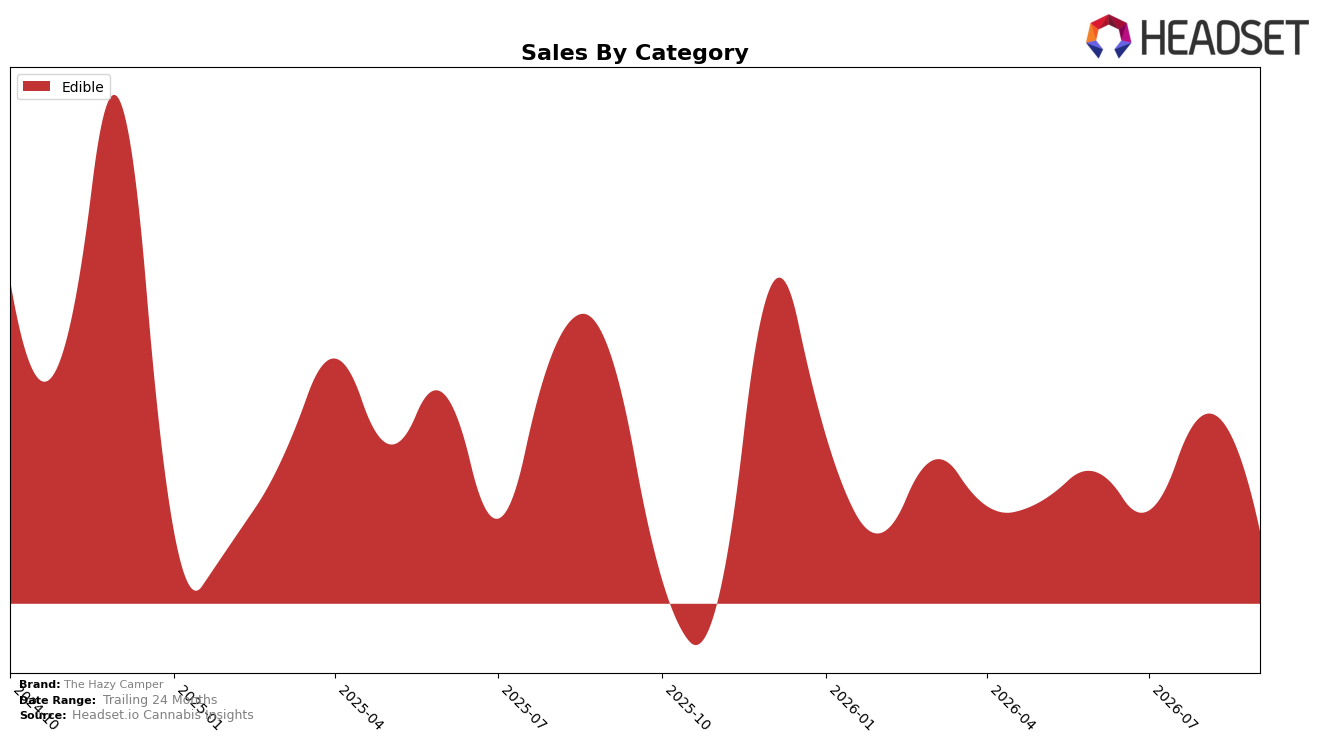
In September 2026, The Hazy Camper concentrated 100.0% of sales in Edible, with year-over-year sales down 37.37% and month-over-month down 27.51%. Average item price rose 54.66% YoY to $8.10, while overall brand sales fell 37.37% YoY, indicating a sharper price uptick than unit demand can absorb. With no rank reported for Edible in British Columbia, the mix’s single-category exposure and the simultaneous MoM and YoY declines point to assortment and price architecture as the core pressure points rather than channel expansion or cross-category gains; the pattern implies overreliance on Edible is amplifying volume sensitivity as prices rise.
The full shift into Edible paired with a 27.51% MoM slide and a 54.66% YoY price increase suggests The Hazy Camper’s positioning has migrated toward higher price tiers without a corresponding value signal in British Columbia. With 100.0% category share inside the brand’s own mix and a 37.37% YoY sales contraction, the data imply that depth (more SKUs or formats within Edible) is not offsetting the trade-down and elastic demand responses; the thesis is that the brand’s current price-pack architecture in Edible is misaligned with prevailing buyer thresholds, and diversification or pack-size recalibration is required to stabilize rank trajectory once it is reported.
Competitive Landscape
The Hazy Camper is ranked #25 in BC Edible for September 2026, down 5 positions from #20 in September 2025, and 2 spots below its June 2026 mark of #23; this sits 7 places off its peak of #18 from December 2024, indicating a multi-quarter slide rather than a single-month dip. Competitively, Spinach climbed from #2 to #1 while growing sales by 31.6%, and Wyld advanced from #5 to #4 with 120.3% YoY growth, outpacing The Hazy Camper’s downward rank move and widening the gap from the top 5. This pattern implies The Hazy Camper is losing share of mind within the aisle as faster-rising leaders concentrate velocity at the top, making a return from #25 toward its #18 peak increasingly costly without a change in mix or activation cadence.

Notable Products
Simply Milk Chocolate Medallion 5-Pack (50mg) posted the steepest pullback at -74.2% MoM while sliding to rank 8, even as Mary's Chocolate Orange Milk Chocolate Bite (10mg) surged +118.6% MoM to rank 2; the split between a top-10 collapse and a triple-digit riser suggests the portfolio is redistributing demand toward single-serve novelties over multi-pack formats. Cherry Bomb Milk Chocolate Bite (10mg) held rank 1 despite a -43.9% MoM drop, while CBD/THC 1:1 Mochaccino Milk Chocolate (10mg CBD, 10mg THC) jumped +116.2% MoM to rank 9; with nine of the top ten in the Edible category and two SKUs posting 100%+ gains, September 2026 points to momentum clustering in flavor-led and function-led bites rather than larger pack sizes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

