

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
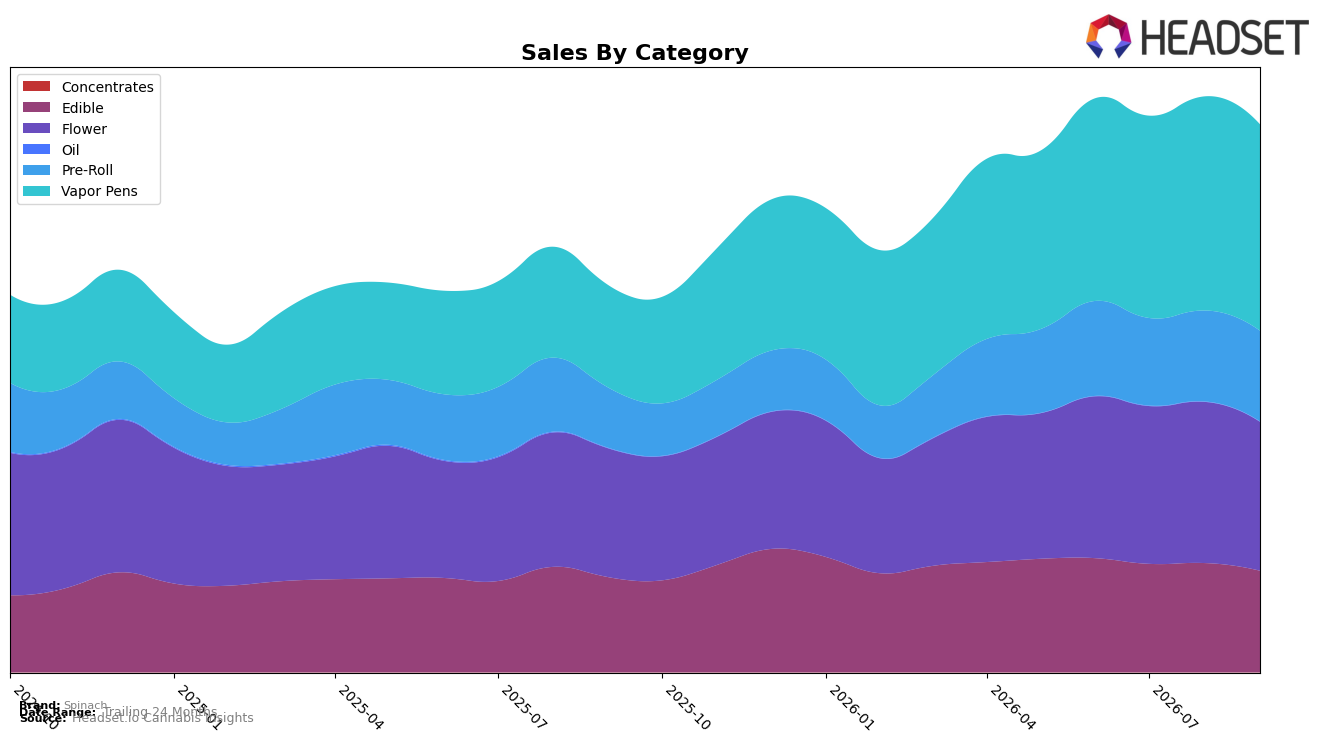
In September 2026, Spinach’s category mix tilted toward Vapor Pens at 37.7% share with year-over-year growth of 101.6% but a month-over-month dip of 3.6%, while Flower held 27.2% share with 15.6% YoY growth and a 7.6% MoM decline. Edible contributed 18.6% share growing 6.7% YoY but falling 7.0% MoM, and Pre-Roll captured 16.5% share with 50.7% YoY growth and a marginal 0.3% MoM slip; Oil remained negligible at 0.04% share with a 32.8% YoY decline but a 15.0% MoM uptick. With overall brand sales up 41.6% YoY alongside a 31.7% YoY increase in average price to $18.12, the mix pattern implies margin-seeking through higher-priced formats even as short-term pullbacks in Vapor Pens and Flower temper near-term volume.
The YoY surge in Vapor Pens (up 101.6%) and Pre-Roll (up 50.7%) against Flower’s more moderate 15.6% YoY rise, combined with a September 2026 Flower rank of 1 in Ontario, suggests a positioning that anchors credibility in Flower while reallocating demand toward faster-growing inhalables. The parallel MoM softness in Vapor Pens (down 3.6%) and Flower (down 7.6%), contrasted with stability in Pre-Roll (down 0.3%), indicates portfolio hedging across inhalable subsegments to balance momentum and volatility; this mix supports sustaining top-tier visibility in Flower while expanding wallet share via Vapor Pens and Pre-Roll where price elasticity appears more favorable.
Competitive Landscape
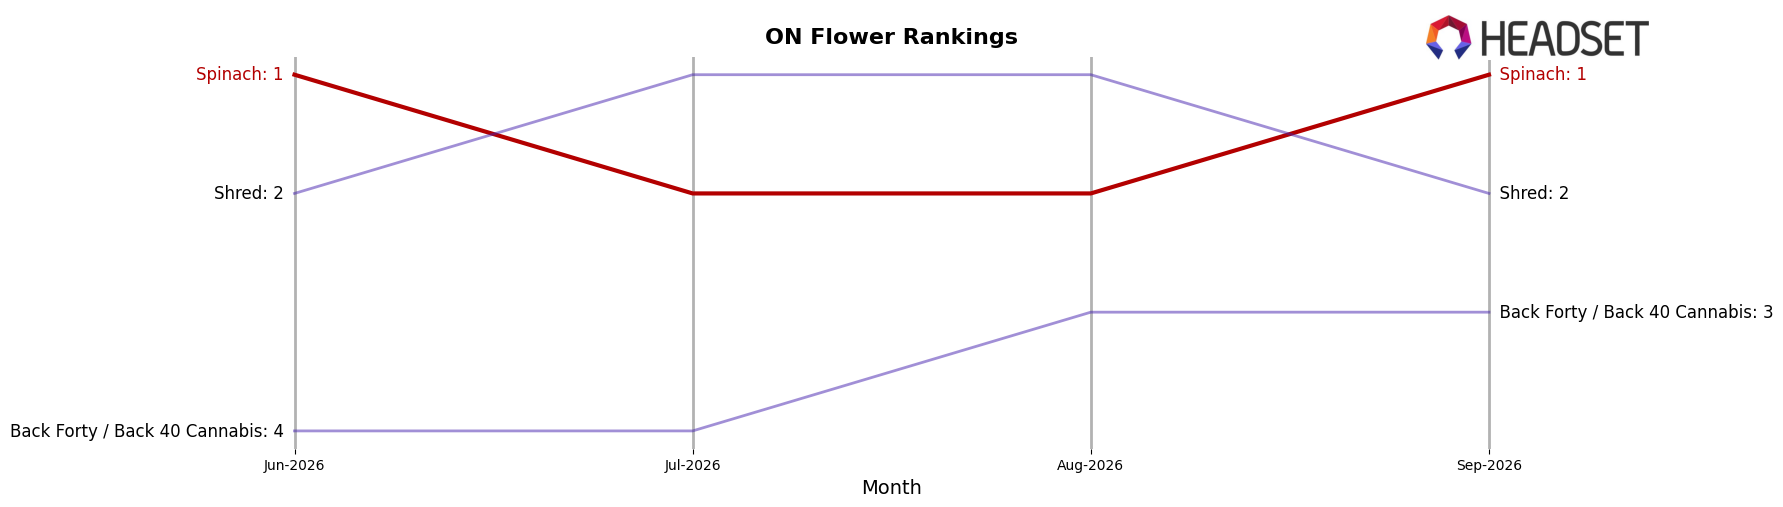
Spinach sits at rank #1 in ON Flower in September 2026, up 2 positions year over year from #3, and unchanged from rank #1 three months ago, signaling stable top placement while moving ahead of peers that either held or lost ground; for example, Shred is at #2 with no YoY rank change from #2 despite a 13.4% YoY sales lift, whereas Back Forty / Back 40 Cannabis slid from #1 to #3 on a -7.4% YoY decline, and FIGR climbed from #14 to #5 with a 51.7% YoY increase, indicating Spinach’s rank lead persists even as challenger momentum concentrates below the top two; the pattern implies Spinach’s trajectory toward sustained leadership relies on defending against fast-rising mid-pack brands while converting rank stability at #1 into durable share before September 2026 gains diffuse.
Notable Products
Sourz - Fully Blasted Pink Lemonade Gummy (10mg) posted the steepest decline in September 2026 at -19.2% MoM while holding rank 3, contrasting with Sourz - Blue Raspberry Watermelon Gummies 5-Pack (10mg) at rank 2 down -8.3% and Sourz - Fully Blasted Blue Raspberry Watermelon Gummy (10mg) at rank 1 down -7.5%. Eight of the top ten SKUs are Edibles, concentrating share at ranks 1 through 4 and 6, 8 through 10, while Pre-Rolls occupy ranks 5 and 7 with one SKU growing +4.2% MoM, implying diversification is occurring mostly at the format rather than flavor level. The highest single-month sales among these were $793,829 for the Sourz - Fully Blasted Blue Raspberry Watermelon Gummies 10-Pack (100mg) at rank 6 despite a -4.5% MoM dip, alongside the CBD/THC 1:1 Peach Orange 5-Pack at rank 10 falling -11.0% MoM, signaling that dosage-size and cannabinoid-ratio extensions are softening even as they anchor volume. Overall, the product mix indicates Spinach is leaning into a Sourz-led edible core while cautiously testing Pre-Rolls, suggesting near-term focus on stabilizing flagship gummy velocity and selectively scaling inhalable trial.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

