

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Amber is stocked at 83 licensed dispensaries across Ohio, Colorado, and 7 other states, 30 of them in Ohio, with the deepest coverage in Columbus, Marietta, Aberdeen, Beavercreek, and Bridgeport. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
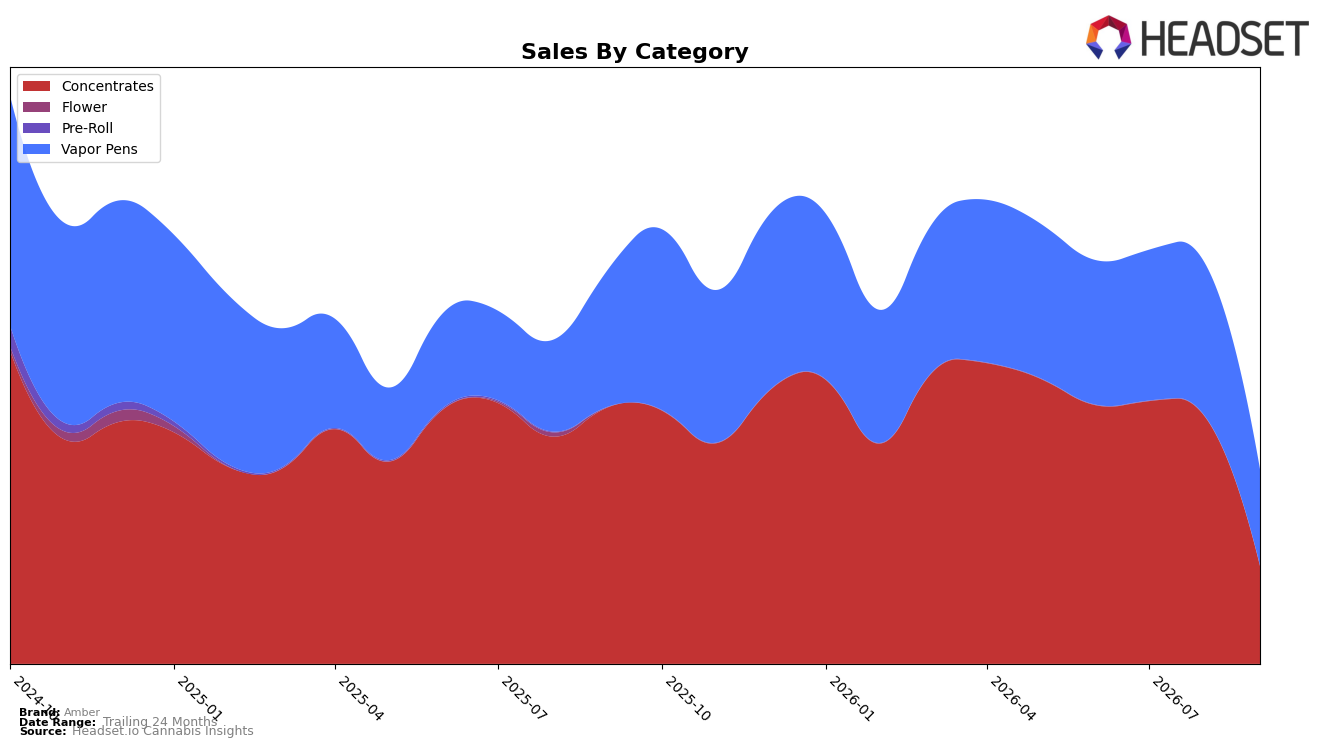
Amber’s mix in September 2026 split almost evenly between Concentrates at 50.37% share and Vapor Pens at 49.63% share, but both categories contracted sharply with Concentrates down 61.97% year over year and 60.56% month over month while Vapor Pens fell 29.97% year over year and 37.14% month over month. Despite an average price rising 42.15% year over year to $21.72, category sell-through eroded, and within Concentrates Amber held rank 11 in Colorado, indicating volume loss outpaced any price-led offset; the pattern implies Amber’s category footprint is overexposed to Concentrates volatility and is not being buffered by Vapor Pens.
The shift leaves Amber positioned as a mid-pack Concentrates player at rank 11 while carrying near-parity reliance on Vapor Pens, yet the steeper 60.56% month-over-month drop in Concentrates versus a 37.14% month-over-month decline in Vapor Pens suggests current demand elasticity is harsher in the Concentrates-heavy half of the mix. With total brand sales down 50.82% year over year against a 24‑month decline of 67.45%, the comparatively smaller recent contraction indicates stabilization potential only if mix tilts toward the less-negative Vapor Pens trajectory; the implication is that defending or modestly growing Vapor Pens share could mitigate downside while Concentrates requires selective SKU pruning rather than scale.
Competitive Landscape
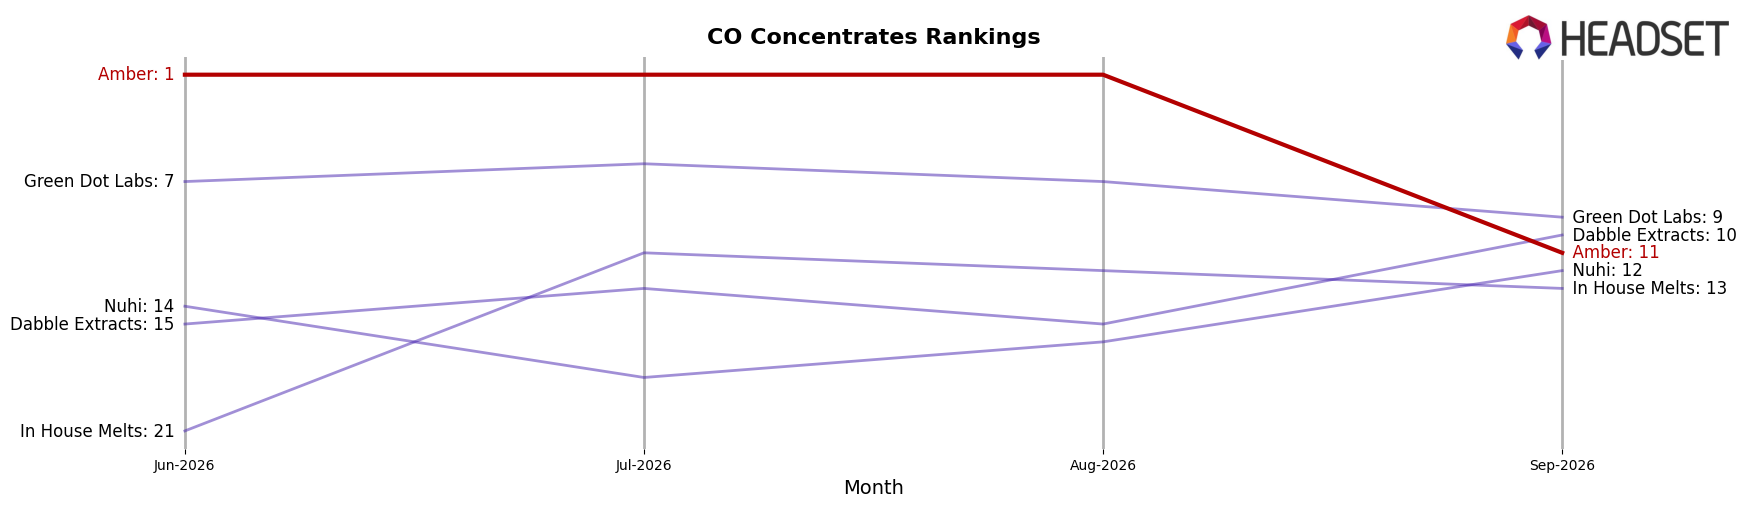
Amber sits at rank #11 in Colorado Concentrates in September 2026 after a year-over-year slide from #1, a 10-position drop that contrasts with its peak at #1 in August 2026 and a three-month decline from #1 to #11. In the same period, 710 Labs holds #1 despite a -18.6% year-over-year sales change, while Sunshine Extracts climbed from #6 to #2 with +49.9% YoY growth; this divergence suggests Amber’s shift is driven less by category contraction and more by share reallocation toward faster-growing rivals, implying sustained pressure on Amber’s placement unless it reverses the multi-rank slide visible between August 2026 and September 2026.
Notable Products
Ky Jealous Wax (4g) led the movement with a -88.4% month-over-month drop while holding rank 1 in September 2026, a sharper decline than Sumo Grande Wax (1g) at -69.1% in rank 6 and MAC Wax (1g) at -78.8% in rank 8. Concentrates account for eight of the top ten SKUs, dominating ranks 1 through 9 aside from two Vapor Pens placements at ranks 3 and 10, which indicates a portfolio still concentrated in extracts even as key wax formats reset. The absence of any >+50% month-over-month gain among top products and the clustering of declines in wax point to demand or inventory pullback in higher-gram concentrates while single‑gram live resin and cartridges stabilize share. This pattern implies Amber is shifting toward mix management in Concentrates and selectively sustaining Vapor Pens to balance volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

