

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
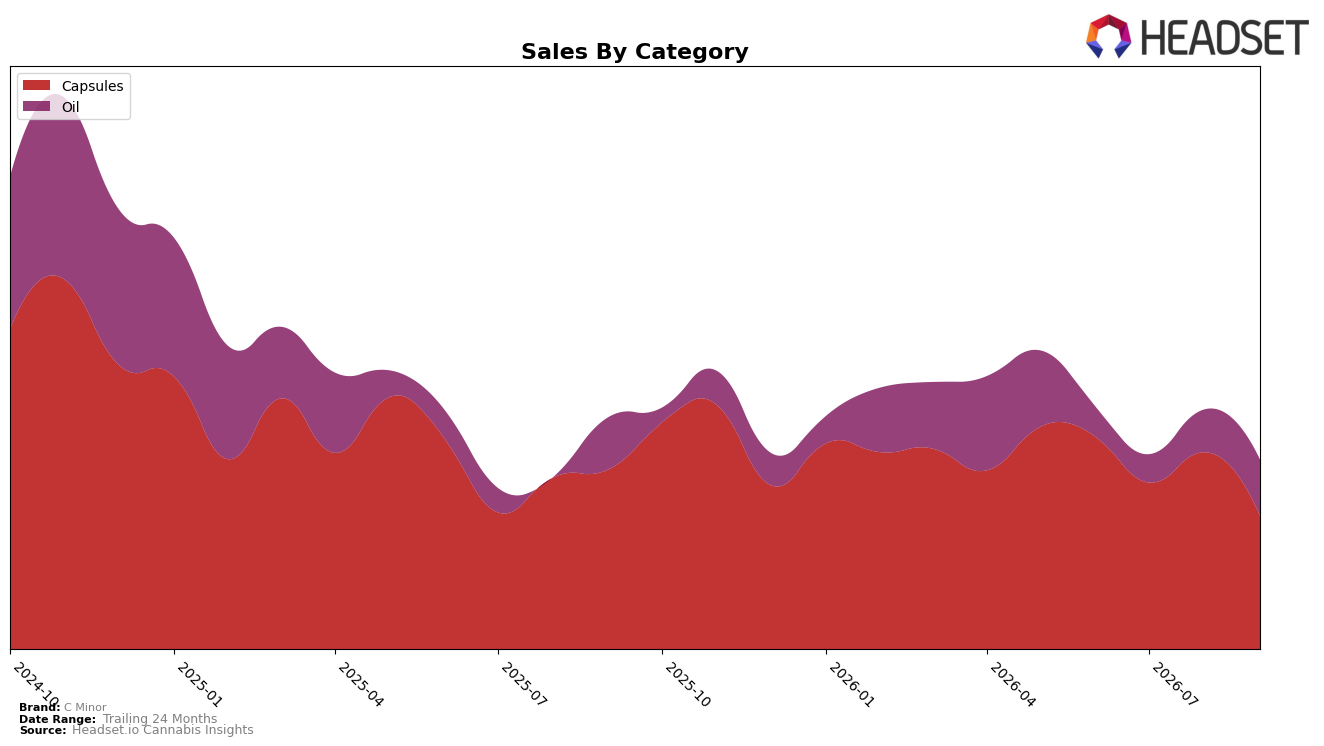
C Minor concentrated 65.27% of September 2026 sales in Capsules with a year-over-year decline of 22.02% and a month-over-month drop of 27.93%, while Oil held 34.73% with a 4.97% YoY increase and an 18.25% MoM gain; the brand’s average price fell 11.21% YoY to $34.50, with Capsules priced at $33.79 and Oil at $35.91. Despite Capsules remaining the top category by share, overall brand sales were down 14.37% YoY as Oil expanded, implying that the category mix is pivoting toward Oil momentum while the Capsules core contracts.
Within Ontario Capsules, C Minor ranked 15th in September 2026 and carried 65.27% of its mix in that category alongside a 27.93% MoM Capsules decline, versus an 18.25% MoM rise in Oil; this divergence suggests price-sensitive or format-shifting consumers are eroding Capsules volume while Oil captures incremental demand. With a 64.96% sales decline over 24 months and a 4.97% YoY Oil uptick, the implication is that maintaining Capsules-led positioning at rank 15 limits headroom, and rebalancing toward Oil where price is higher and growth is positive could stabilize share without fully abandoning Capsules where the brand still commands the larger base.
Competitive Landscape
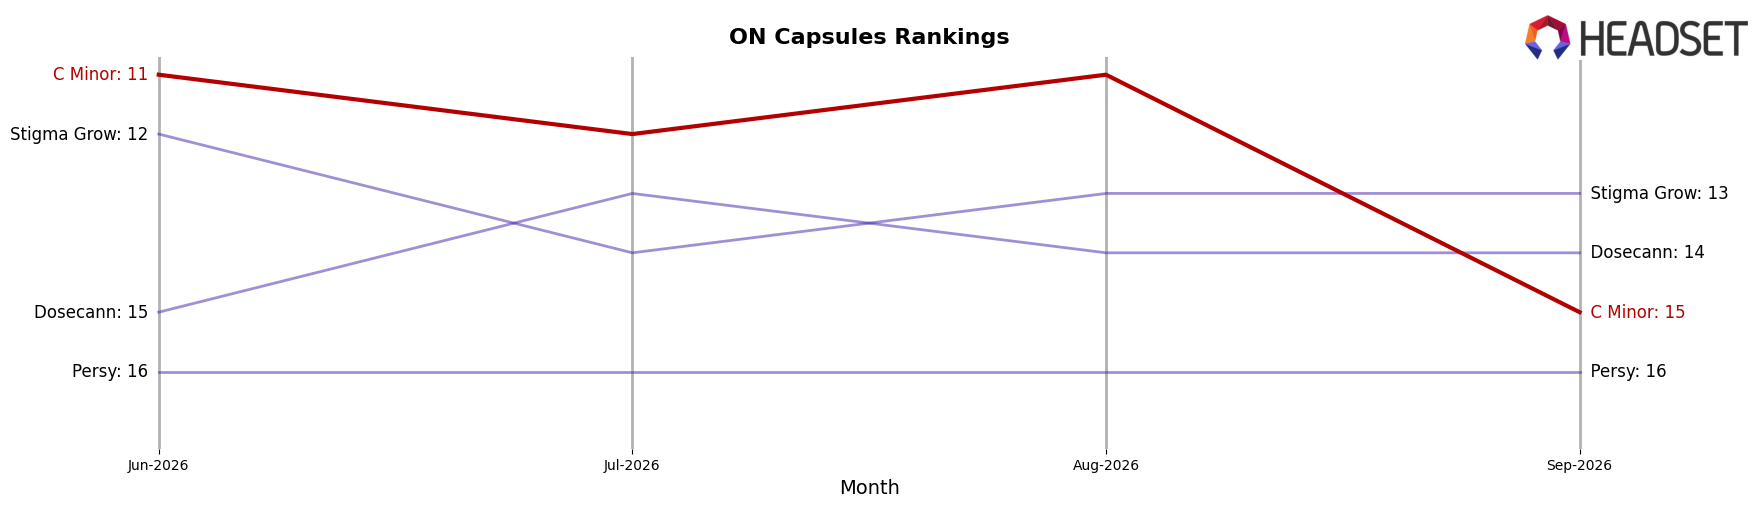
C Minor sits at #15 in ON Capsules in September 2026, sliding 2 ranks year over year from #13, and dropping 4 spots since June 2026 when it was #11; relative to its category peak at #9 in September 2024, the current position is 6 ranks lower, while category leaders shifted as Glacial Gold advanced from #4 to #2 and Tweed fell from #2 to #4. Competitor trajectories amplify the pressure: Emprise Canada climbed from #5 to #3 alongside a 43.3% YoY sales increase, whereas Redecan declined from #3 to #5 with a 26.1% YoY sales contraction; in contrast, C Minor’s 2-rank YoY decline and 4-rank 3-month drop signal share reallocation toward faster-moving rivals. The pattern implies C Minor’s rank trajectory is drifting away from its September 2024 peak toward a mid-teen band unless it counters competitors’ momentum with either mix or distribution gains, given simultaneous upward mobility at the top and downward shifts among legacy players.
Notable Products
CBD 50 Max 3000 Oil Drops (60ml) posted the largest month-over-month surge at 56.6% and advanced to rank 2, while CBD Fast Acting 50 Max Softgels 30-Pack (1500mg CBD) fell 27.9% yet held rank 1. Three of the top four SKUs are Oil products (ranks 2–4), and CBD Isolate 100 Max 3000 Oil (30ml) slipped 2.0% at rank 3, indicating Oil momentum despite the Capsules leader’s contraction. With the Softgels pack concentrating the only large dollar volume at $17,585 and Oils gaining rank and growth, the mix implies a pivot toward tincture-based formats as the engine of near-term share maintenance.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

