

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
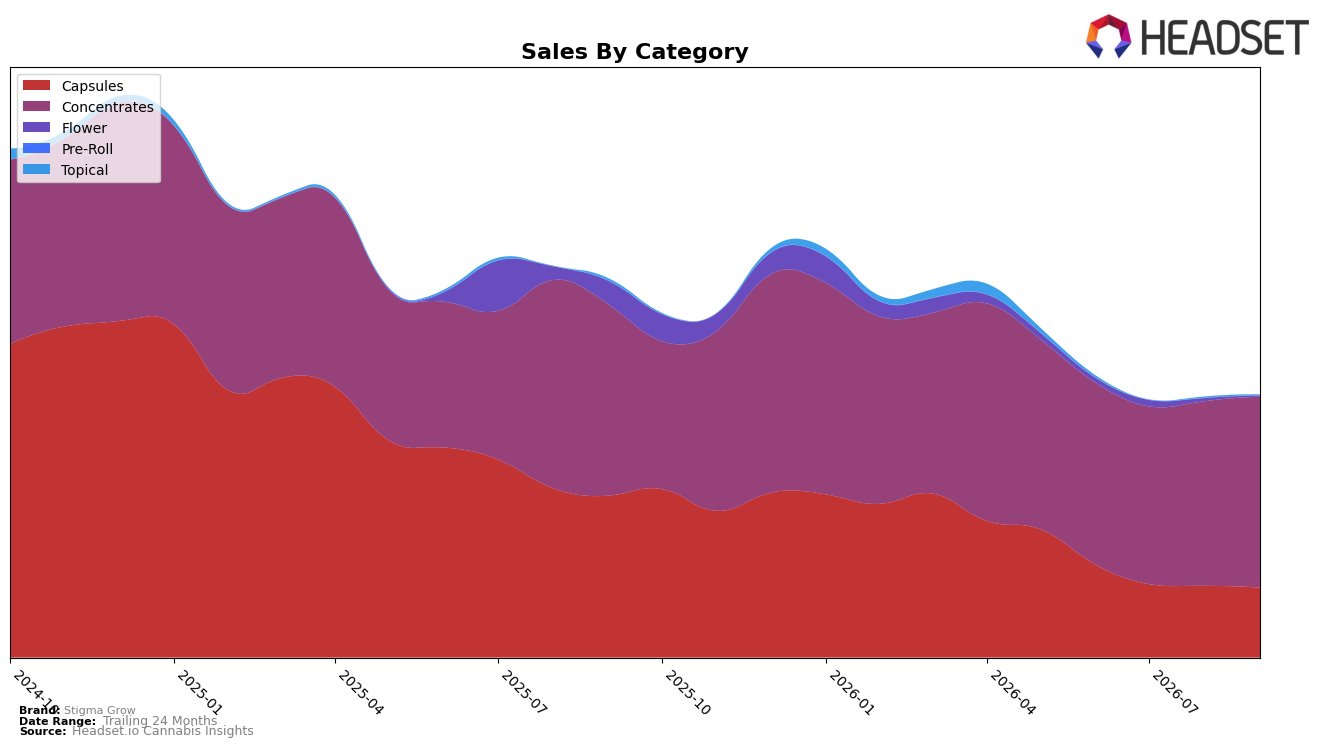
In September 2026, Stigma Grow concentrated its sales in Concentrates at 72.81% share with month-over-month growth of 3.38% and a near-flat year-over-year change of -0.31%, while Capsules held 26.64% share with -2.43% MoM and -56.88% YoY declines. Minor lines contracted sharply: Flower fell -68.82% MoM and -96.09% YoY to 0.35% share, and Topical slipped -39.94% MoM and -73.64% YoY to 0.21% share. With an average price down 4.66% YoY and overall brand sales down 30.77% YoY, the mix indicates reliance on Concentrates as the stabilizer, while steep Capsule and long-tail pullbacks compress breadth and raise concentration risk.
Given an 11th rank in Concentrates in Alberta and a 72.81% category share of brand sales, the portfolio is effectively positioned as a Concentrates-led specialist, but the -56.88% YoY collapse in Capsules and sub-1% shares in Flower and Topical curtail cross-category discovery and limit shelf leverage. The 3.38% MoM lift in Concentrates alongside a 4.66% YoY price decrease suggests price-sensitive defensibility within the core, yet the -30.77% YoY brand sales decline implies that improving rank or expanding into adjacencies will be necessary to offset erosion from Capsules and ultra-small categories.
Competitive Landscape
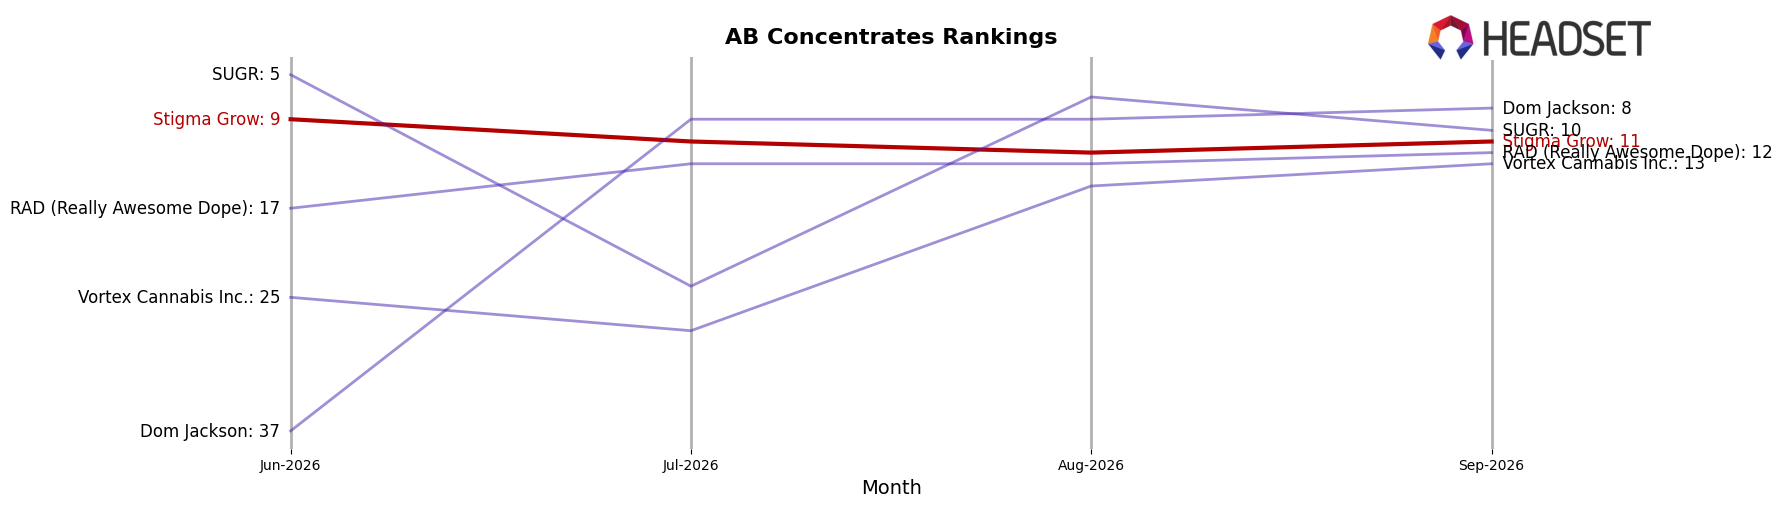
Stigma Grow sits at rank #11 in AB Concentrates in September 2026, improving 3 positions from #14 year over year but slipping 2 spots from #9 in June 2026, indicating mid-year giveback after earlier gains toward its peak of #8 in April 2026. Competitively, BoxHot holds at #1 year over year with a 5.8% YoY sales increase while Endgame remains #2 despite a -3.1% YoY sales decline, and Sticky Greens surged from #61 to #5 with a 2,757.0% YoY increase, creating upward pressure on mid-tier ranks. The pattern implies Stigma Grow’s modest YoY climb is being offset by sharper ascents from fast-rising rivals, so holding double‑digit rank will likely require recapturing momentum seen in April 2026 and reversing the 2-rank slide since June 2026.
Notable Products
Phoenix Tears Honey Oil (1g) posted the steepest decline in September 2026 at -88.9% MoM, sliding to rank 6, while Phoenix Tears Resin (1g) fell -75.4% MoM to rank 5. Phoenix Tears RSO (1g) moved in the opposite direction with +14.8% MoM at rank 1 and accounted for $117,962, creating a widening performance gap inside the Phoenix Tears line. Rippin Razz 2.0 Shatter (4g) dropped -42.2% MoM at rank 4, and with four of the top ten sitting in Concentrates, the category’s volatility is concentrated in a few Phoenix-branded SKUs. The pattern implies Stigma Grow is consolidating demand around a flagship RSO while de-emphasizing slower-moving Phoenix derivatives, pointing to a tighter Concentrates portfolio and reduced long-tail exposure.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

