

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Choice is stocked at 521 licensed dispensaries across Michigan, Massachusetts, and Washington, 413 of them in Michigan, with the deepest coverage in New Buffalo, Detroit, Grand Rapids, Monroe, and Ann Arbor. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
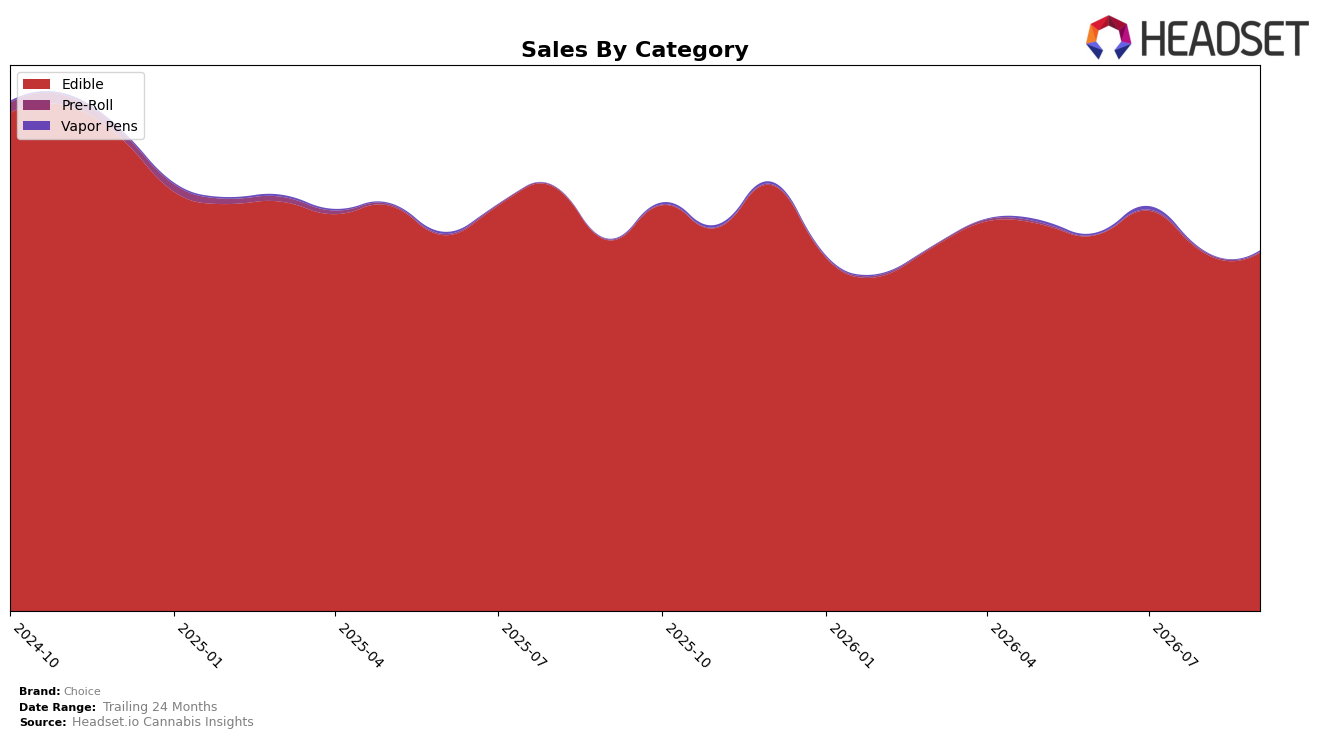
Choice’s mix in September 2026 was concentrated in Edible at 99.26% share, where year-over-year sales were down 3.36% even as month-over-month edged up 0.17%, while brand-level sales were down 3.10% YoY and down 25.99% over 24 months. Vapor Pens, though only 0.48% share, surged 115.28% YoY and 63.06% MoM, contrasted with Pre-Roll at 0.26% share falling 1.14% YoY and 38.62% MoM; average price rose 4.24% YoY to $3.92. With an Edible rank of 2 in Michigan, the pattern implies dependence on a single category for scale with nascent diversification pressure emerging from Vapor Pens.
The small but rapidly expanding Vapor Pens slice growing 115.28% YoY and 63.06% MoM, alongside Pre-Roll’s 38.62% MoM contraction and Edible’s 0.17% MoM lift, implies a portfolio pivot opportunity: defend Edible’s scale while selectively reallocating toward Vapor Pens where price points are 51.2% higher than brand average. Holding rank 2 in Edible yet managing a brand-level 3.10% YoY sales decline suggests that maintaining share requires incremental category breadth; the thesis is that modest share rebalancing toward Vapor Pens can offset Edible’s negative 3.36% YoY trend without diluting the Edible-led position.
Competitive Landscape
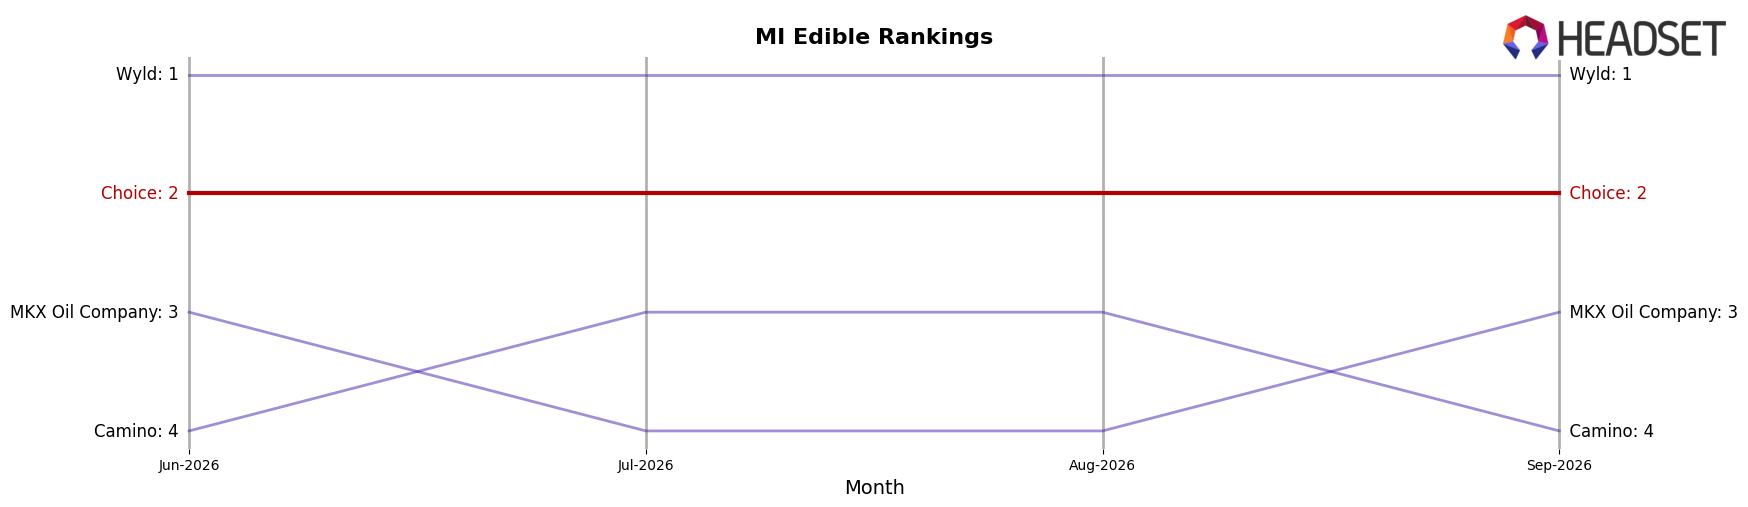
Choice holds rank #2 in MI Edible in September 2026, unchanged from #2 year over year, while its prior peak of #1 in January 2025 contrasts with a flat three-month rank at #2, indicating stability rather than ascent; in comparison, Wyld stayed at #1 year over year despite a -18.3% YoY sales change, and Rocket (MI) advanced from #14 to #5 with 65.2% YoY sales growth, suggesting pressure from below even as the top spot remains defended. With MKX Oil Company fixed at #3 despite a -3.3% YoY sales change and Choice parked at #2 for both the current and three-month views, the pattern implies Choice is locked in a holding pattern where small share shifts could either re-open a path back to #1 or allow a faster-rising follower to compress the gap.
Notable Products
Sativa Red Raz Haze Gummies 10-Pack (200mg) posted the steepest decline in September 2026 at -11.2% while slipping to rank 3, as Chronic Cherry Berry Soft Chews 10-Pack (200mg) held rank 1 with a -5.5% dip. Sunset Orange Soft Chews 10-Pack (200mg) delivered the largest gain in the top ten at +12.3% and climbed to rank 8, and Sativa Blue Razz Dream Gummies 10-Pack (200mg) rose +8.3% to cement rank 2 with about $112.9K in sales. Eight of the top ten are Edible SKUs concentrated in gummies and soft chews, with Watermelon Kush Gummies 10-Pack (200mg) adding +8.7% at rank 6 while Strawnana Smoothie Soft Chews 10-Pack (200mg) eased -1.9% at rank 7. The mix points to Choice leaning into flavored gummies as the commercial core, prioritizing breadth within Edibles to buffer single-SKU volatility while nudging mid-pack risers up the ranking ladder.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

