

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Camino is stocked at 2,095 licensed dispensaries across California, Michigan, and 14 other states, 547 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Francisco, San Diego, and Santa Ana. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
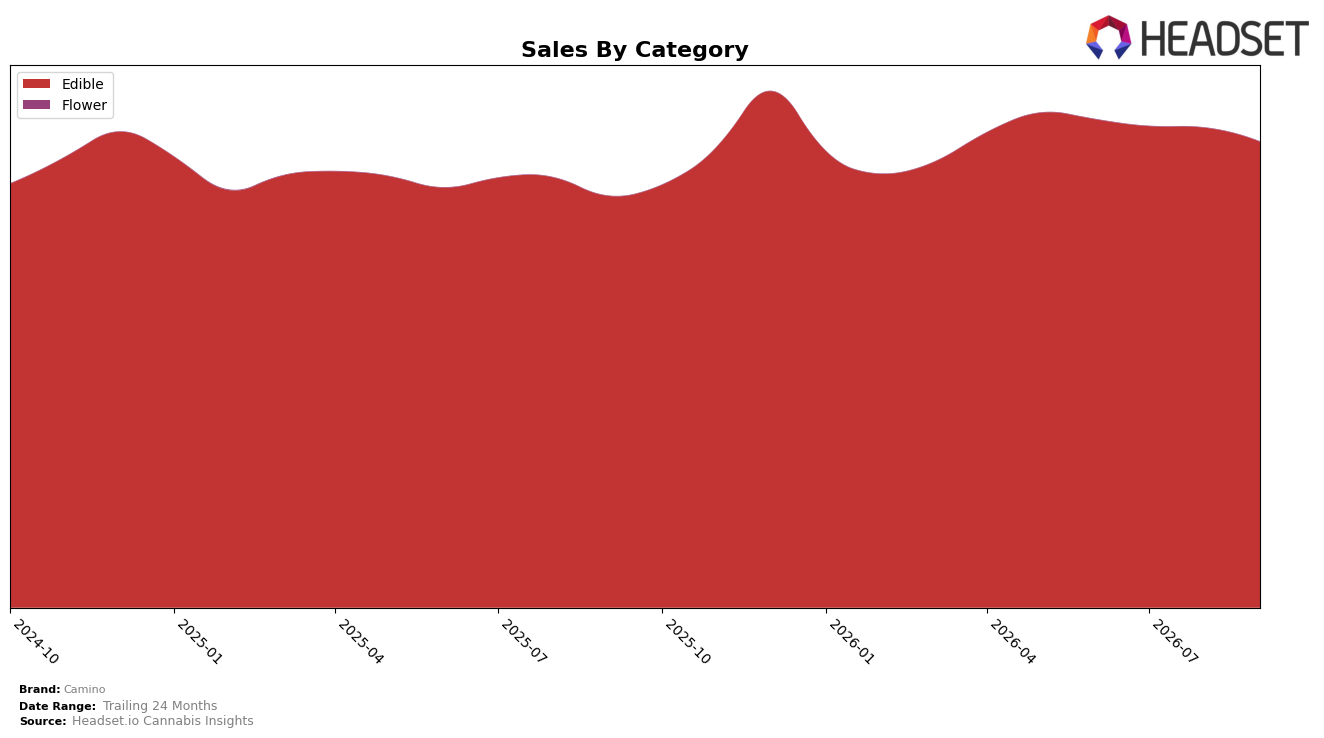
Edible accounted for 100.0% of Camino’s mix in September 2026, with year-over-year sales up 13.2% while month-over-month slipped 2.9%. Average price fell 2.1% YoY alongside a fully concentrated category footprint at rank 1 in Edible in Massachusetts, implying that growth is coming from volume rather than pricing and that the single-category focus is amplifying sensitivity to monthly demand swings.
With 100.0% reliance on Edible and a 2.9% MoM dip against a 13.2% YoY gain, Camino’s positioning hinges on maintaining category leadership and mitigating short-cycle volatility through pricing and pack architecture rather than assortment shifts. Holding rank 1 in Edible in Massachusetts while average price is down 2.1% YoY signals a value-led stance that can defend share in Massachusetts but may require margin management as volume-driven gains meet periodic pullbacks.
Competitive Landscape
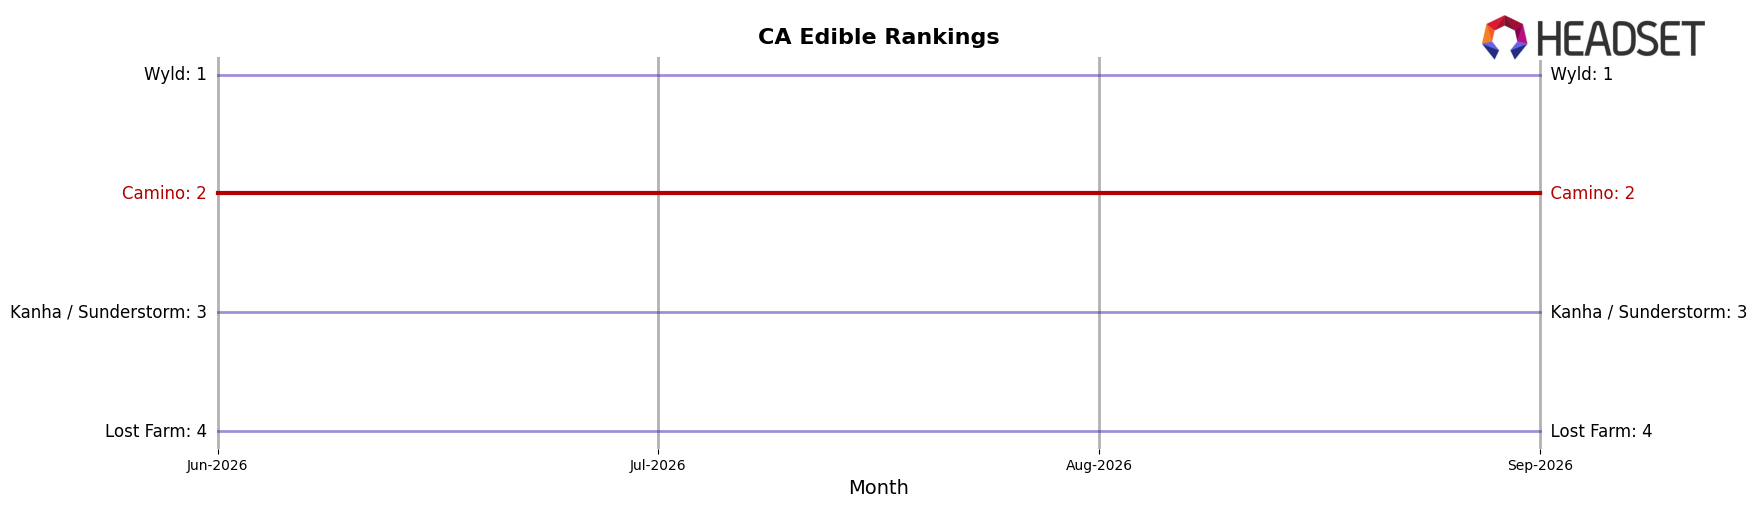
Camino sits at rank #2 in CA Edible in September 2026, unchanged from #2 in September 2025, and has also held #2 for three consecutive months, while peaking at #2 in September 2026; this stability contrasts with Wyld at #1 despite a -21.97% year-over-year sales change and with Kanha / Sunderstorm at #3 on +11.45% year-over-year sales, indicating Camino’s flat rank against diverging momentum above and below. With Wyld declining and Kanha / Sunderstorm growing, Camino’s unchanged #2 suggests retention of share against a weakening leader and a closing gap from the #3 contender, implying the next movement is more likely a push upward or increased pressure from below than continued stasis.
Notable Products
Bliss - Sour Watermelon Lemonade Gummies 20-Pack (100mg) posted the steepest decline at -5.32% MoM while holding rank 3, contrasted with rank 1 THC/CBN 5:1 Midnight Blueberry Sleep Gummies 20-Pack (100mg THC, 20mg CBN) up 2.06% MoM, and rank 2 CBD/THC/CBN 1:1:1 Deep Sleep Sour Blackberry Dream Gummies 10-Pack (100mg CBD, 100mg THC, 100mg CBN) up 3.43% MoM. Eight of the top ten are Edible sleep or mood SKUs concentrated in multi-cannabinoid formulas, with rank positions 1-2 in sleep-focused gummies and rank 8 THC/THCV 2:1 Sour Tropical Burst Gummies 20-Pack (100mg THC, 50mg THCV) sliding -8.69% MoM. The pattern implies Camino is tilting assortment and demand toward sleep-centric, ratio-led Edibles, using incremental gains at ranks 1-2 to offset softness in flavor-led SKUs at ranks 3 and 8, supporting a strategy that prioritizes functional effects over novelty flavors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

