

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
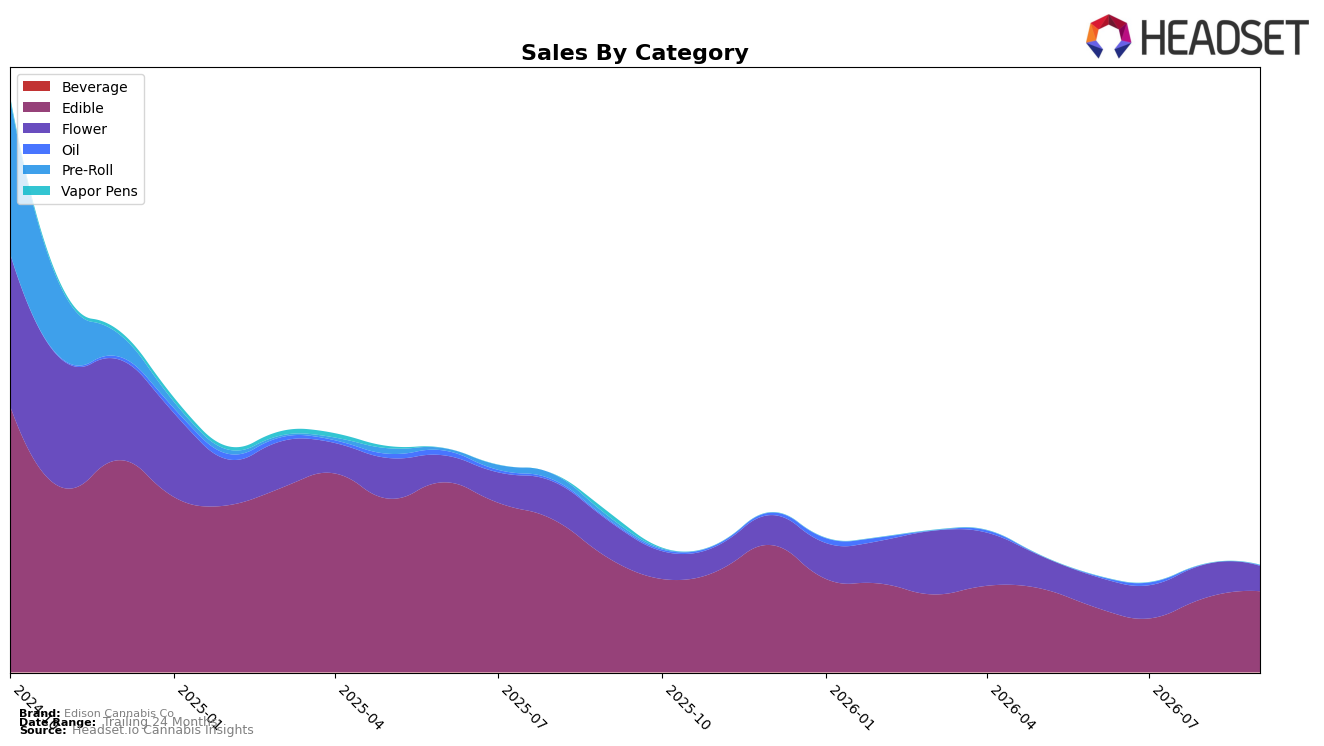
Edison Cannabis Co concentrated 75.9% share in Edible during September 2026, with Edible sales up 9.3% MoM but down 29.2% YoY, while Flower held 23.7% share with a 24.7% MoM decline and a 32.4% YoY drop. Oil is now marginal at 0.4% share with a 59.1% YoY contraction and no observed MoM data. Average price across the brand rose 154.2% YoY to $15.47, contrasting with Edible’s lower average price of 12.28 and Flower’s high 91.72, implying mix and pack-size changes rather than uniform pricing shifts. In Alberta Edibles, the brand sits at rank 13, paired with a 33.2% YoY decline in total brand sales and an 86.5% 24‑month contraction, which indicates the portfolio has pivoted toward Edibles while retreating from Flower to stabilize share within a mid‑tier rank.
The mix shift toward Edibles (up 9.3% MoM with 75.9% share) alongside a steep Flower pullback (down 24.7% MoM with 23.7% share) and a 13th rank in Alberta Edibles suggests Edison Cannabis Co is prioritizing velocity in lower-priced, higher-penetration formats over premium Flower volume. The 154.2% YoY increase in average price against a 33.2% YoY sales decline and a 32.4% YoY drop in Flower points to fewer, higher-priced units or larger packs in select SKUs, while the 59.1% YoY contraction in Oil at 0.4% share signals deliberate pruning of fringe formats; together these patterns imply a defensive positioning centered on Edibles to preserve distribution and visibility despite overall scale compression.
Competitive Landscape
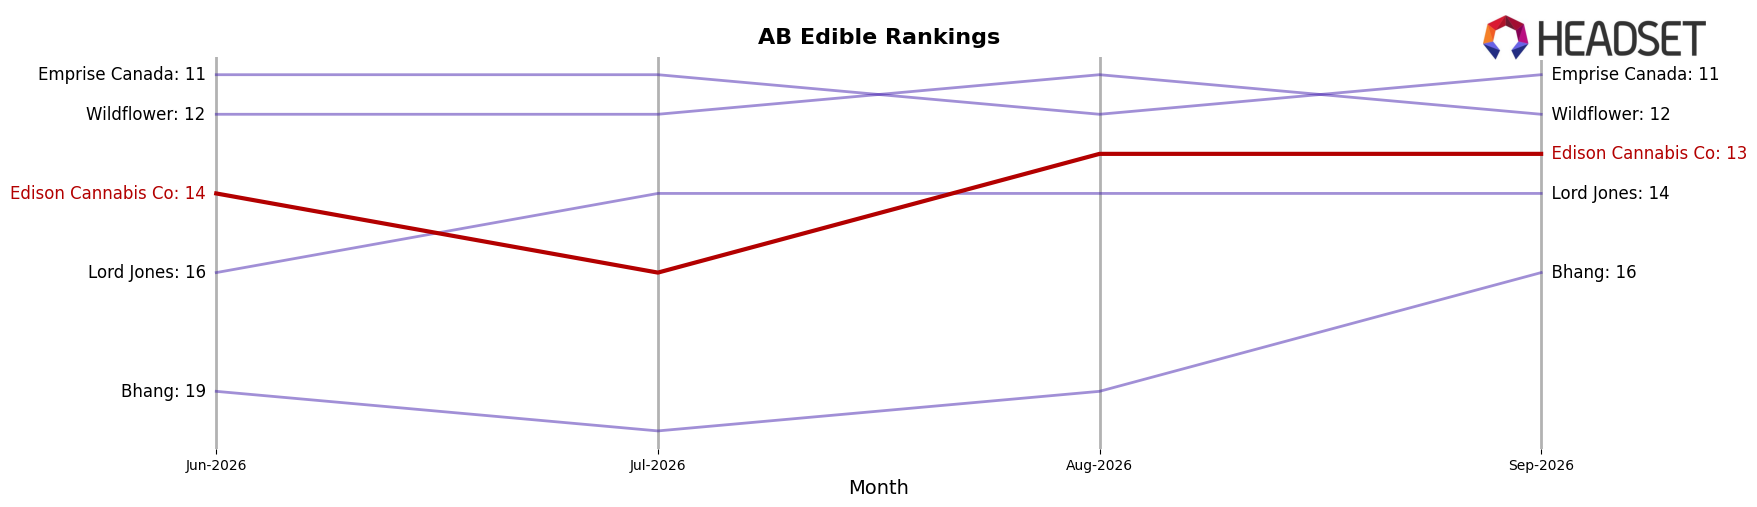
Edison Cannabis Co sits at rank #13 in AB Edible in September 2026 after improving 4 positions year over year from #17, but it slipped 1 spot versus June 2026 when it was #14. The brand remains below its peak rank of #6 from September 2024 while category leaders are moving in divergent directions: Spinach holds #1 despite a -5.4% YoY sales change, whereas Wyld is steady at #2 with +32.2% YoY sales growth, and No Future climbed from #5 to #3 with +62.7% YoY growth. With Olli advancing from #7 to #4 on +88.2% YoY growth while Gron / Grön eased from #3 to #5 despite +14.5% YoY, the mix signals that Edison’s modest rank recovery amid faster-moving rivals points to a stabilization phase where holding share requires sharper differentiation.
Notable Products
Jolts - Sativa Arctic Cherry Lozenge (10mg) posted the standout move in September 2026 with a 1361% month-over-month surge, vaulting into rank 6, while Sonics - CBD/THC 1:1 Red Razz Chiller Gummies 2-Pack (10mg CBD, 10mg THC) climbed 51% to rank 3. In contrast, Sonics - CBD/THC 1:1 Kiwi Berry Burst Gummies 5-Pack (50mg CBD, 50mg THC) fell 38% to rank 4, and Blueberry Dream (28g) dropped 30% to rank 5 despite remaining a top-five Flower SKU. With five of the top seven ranked items in September 2026 coming from Edibles led by Jolts - Limelight Live Resin Lozenges 10-Pack (100mg) at rank 1 and up 11%, the mix points to Edison Cannabis Co tilting assortment and velocity toward fast-turn Edibles while large-format Flower recedes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

