


Where to Buy
Flamer is stocked at 78 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, Rochester, and Buffalo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
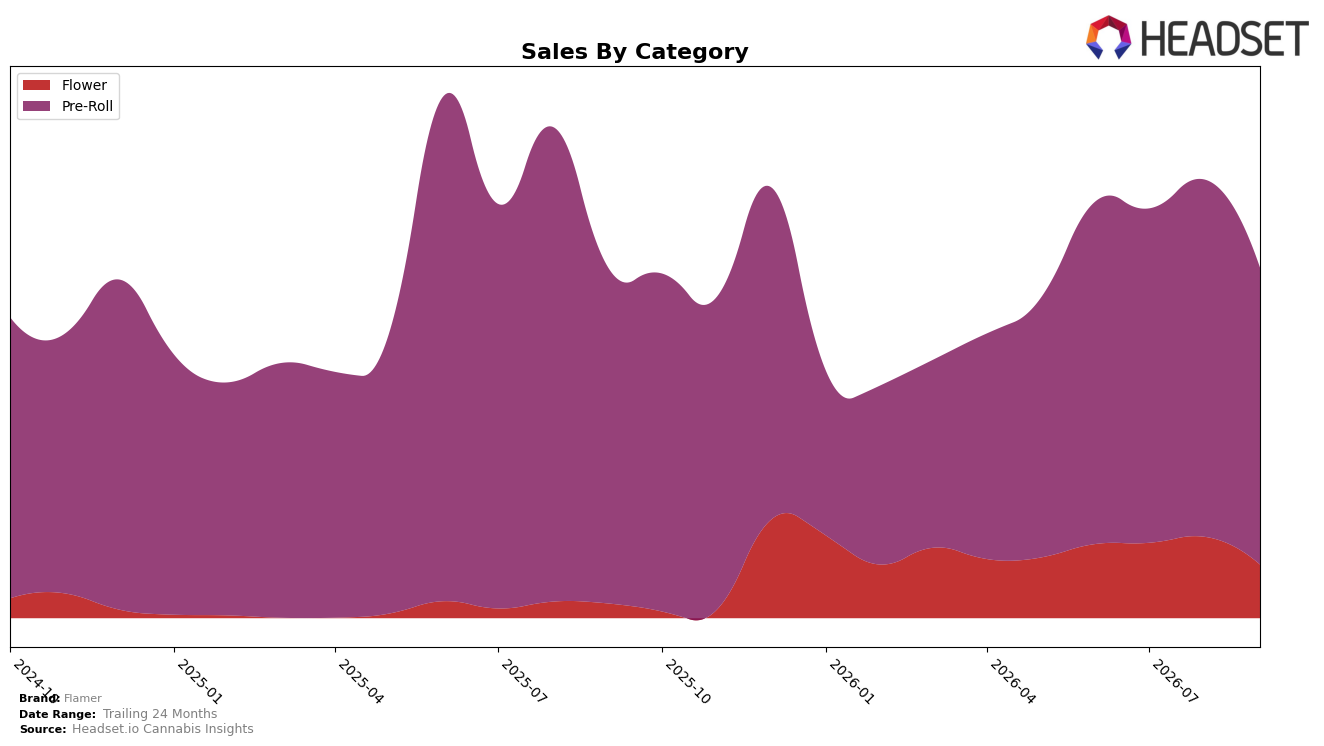
In September 2026, Flamer concentrated 84.79% of sales in Pre-Roll while Flower accounted for 15.21%, with Pre-Roll down 11.59% year over year and 16.90% month over month, and Flower up 272.63% year over year but down 34.28% month over month. The brand’s average price fell 8.61% year over year to $29.55 as Pre-Roll pricing sat at $28.00 and Flower at $42.72, and overall brand sales rose 1.04% year over year alongside a 13.52% gain versus 24 months. The pattern implies a reliance on Pre-Roll as the volume anchor despite negative momentum, while Flower acts as the volatile growth lever with outsized YoY expansion but MoM contraction.
Flamer ranked 43 in Pre-Roll in New York, pairing an 84.79% Pre-Roll mix with a double-digit MoM decline of 16.90% that outpaced the brand’s 34.28% MoM pullback in the smaller Flower segment. With Flower’s 272.63% YoY surge reshaping only 15.21% of mix and average price down 8.61% YoY, the configuration signals price-led defense in the core Pre-Roll position while mix-driven upside requires stabilizing Flower’s month-to-month swings to lift rank and share.
Competitive Landscape
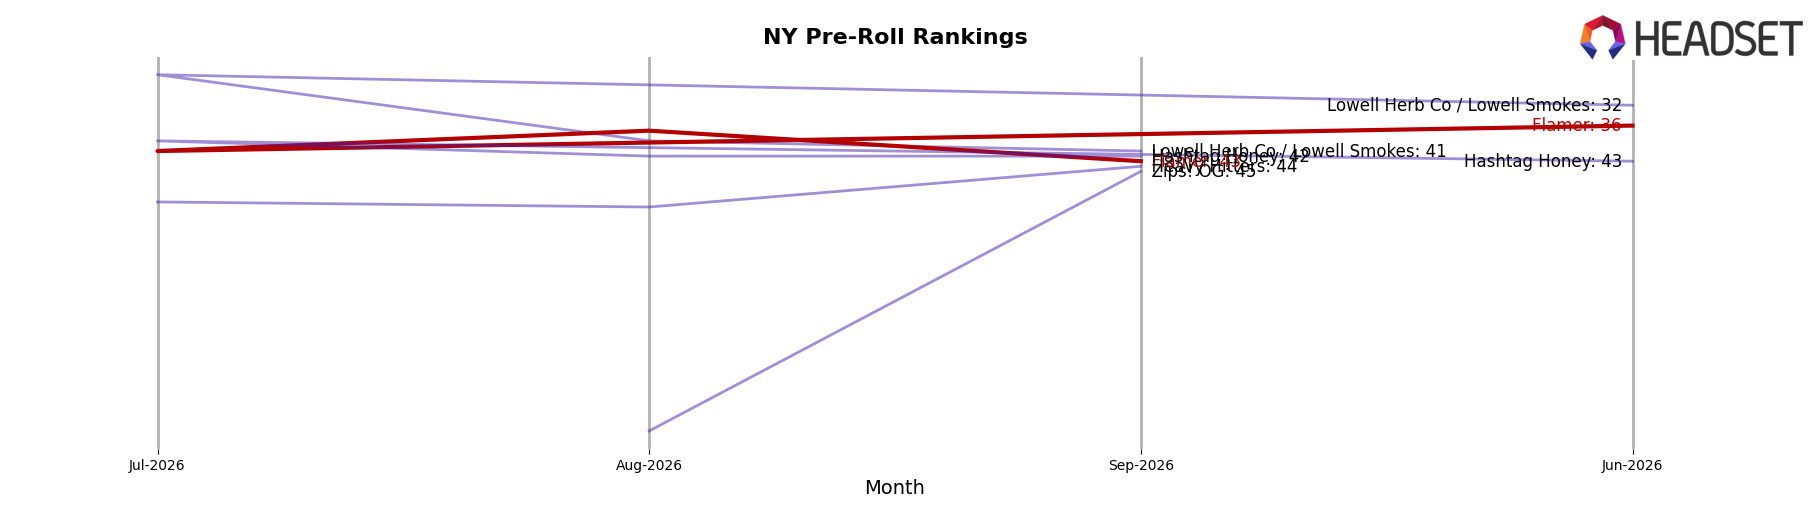
Flamer sits at rank #43 in NY Pre-Roll for September 2026, down 9 places year over year from #34 and slipping 7 places versus June–August’s #36; against this, peers moved in the opposite direction as Jeeter climbed from #6 to #2 and PICC Platform surged from #54 to #5 with 919.6% YoY sales growth, while Ruby Farms held #1 with a 14.4% YoY sales increase. Flamer’s current #43 also trails its peak #20 from June 2025 by 23 positions, and the 3-month slide from #36 to #43 contrasts with Anthem rising from #22 to #3 alongside 381.5% YoY sales growth; the pattern implies Flamer is ceding share to faster-accelerating incumbents and challengers and will need to reverse multi-quarter rank erosion to re-enter the top 30.
Notable Products
He He/Ha Ha (3.5g) posted the steepest decline in September 2026 at -51.1% and slid to rank 9, while Silly Goofy Pre-Roll (0.75g) contracted -35.1% yet held rank 1. Silly Goofy Pre-Roll 5-Pack (2.5g) also fell -31.6% at rank 2, and Revelation (3.5g) dropped -29.6% at rank 8. With eight of the top ten SKUs in Pre-Roll, this mix points to reliance on value and format breadth even as Flower volatility drags the tail.
P.N.C Pre-Roll 5-Pack (2.5g) rose +24.4% to rank 3, offsetting part of the single-pack pullback, and P.N.C Pre-Roll (0.75g) gained +14.3% at rank 6. Lobotomy Pre-Roll (0.75g) added +11.0% at rank 4, while Lobotomy Pre-Roll 5-Pack (2.5g) eased -4.3% at rank 5 and Pillow Princess (3.5g) declined -19.3% at rank 7. The pattern implies multi-pack Pre-Rolls are absorbing demand at mid-ranks, signaling pricing-pack architecture as the near-term commercial lever despite softness in single Pre-Rolls and Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

