

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
CRU Cannabis is stocked at 76 licensed dispensaries across New York, Washington, and 2 other states, 68 of them in New York, with the deepest coverage in New York, Brooklyn, Queens, Staten Island, and The Bronx. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
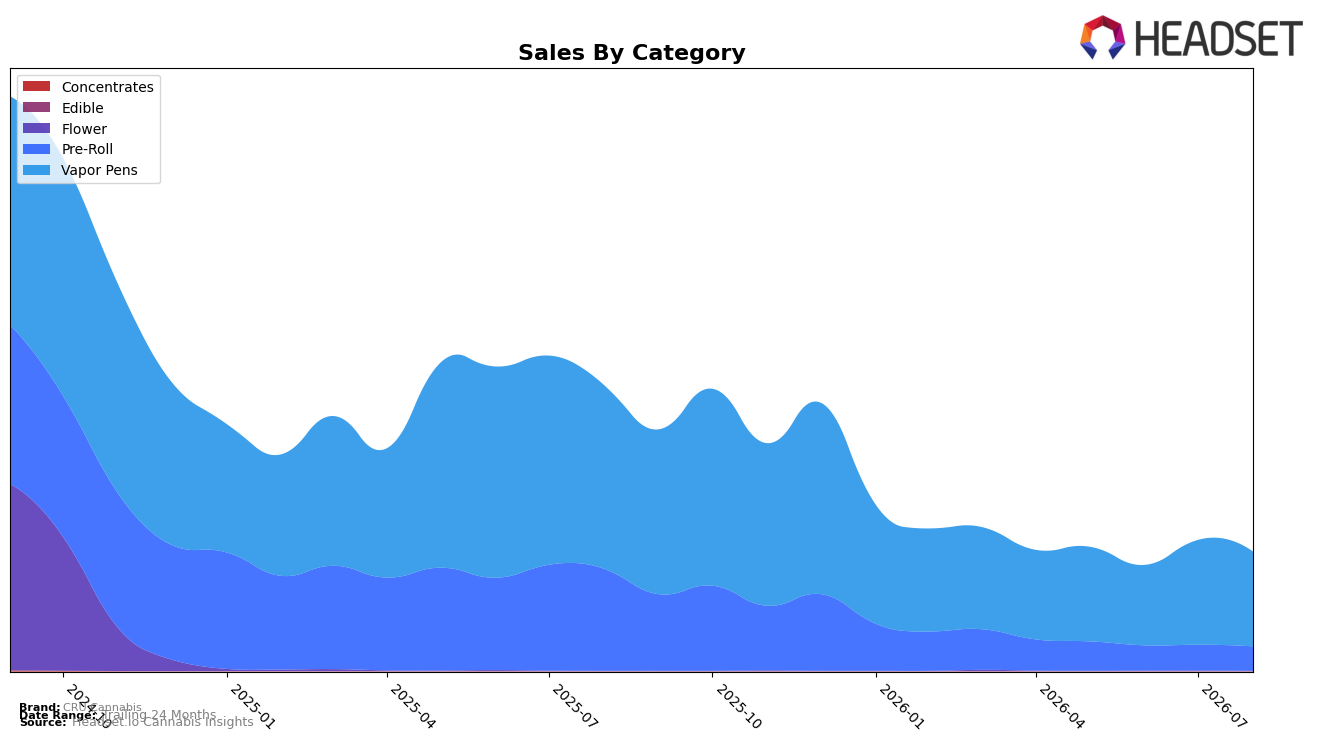
CRU Cannabis concentrated 79.53% of August 2026 sales in Vapor Pens, down 9.60% month over month and 48.49% year over year, while Pre-Roll held 20.47% share with a 4.56% MoM decline and a 76.08% YoY drop; combined, this mix contributed to a brand-level YoY contraction of 58.34% alongside a modest 1.92% YoY increase in average price. With Vapor Pens ranked 44 in New York for the category and Pre-Roll prices averaging $10.83 versus $41.82 in Vapor Pens, the category tilt is toward higher ticket items even as both segments retrench; the pattern implies the brand is leaning into a premium-priced Vapor Pens core that is shrinking faster MoM than the smaller Pre-Roll base, concentrating risk in a weakening anchor.
The mix shift’s implication is that maintaining a 79.53% reliance on Vapor Pens while the segment falls 9.60% MoM and 48.49% YoY will likely drag overall visibility where the category rank sits at 44, and the 4.56% MoM slide in Pre-Roll limits diversification upside. Given a 1.92% YoY rise in average price alongside an 80.16% 24‑month sales decline and a 76.08% YoY contraction in Pre-Roll, the brand’s pricing posture supports revenue per unit but not unit velocity; this implies near-term positioning will hinge on stabilizing Vapor Pens share while selectively rebalancing toward Pre-Roll to mitigate exposure to further rank erosion in Vapor Pens.
Competitive Landscape
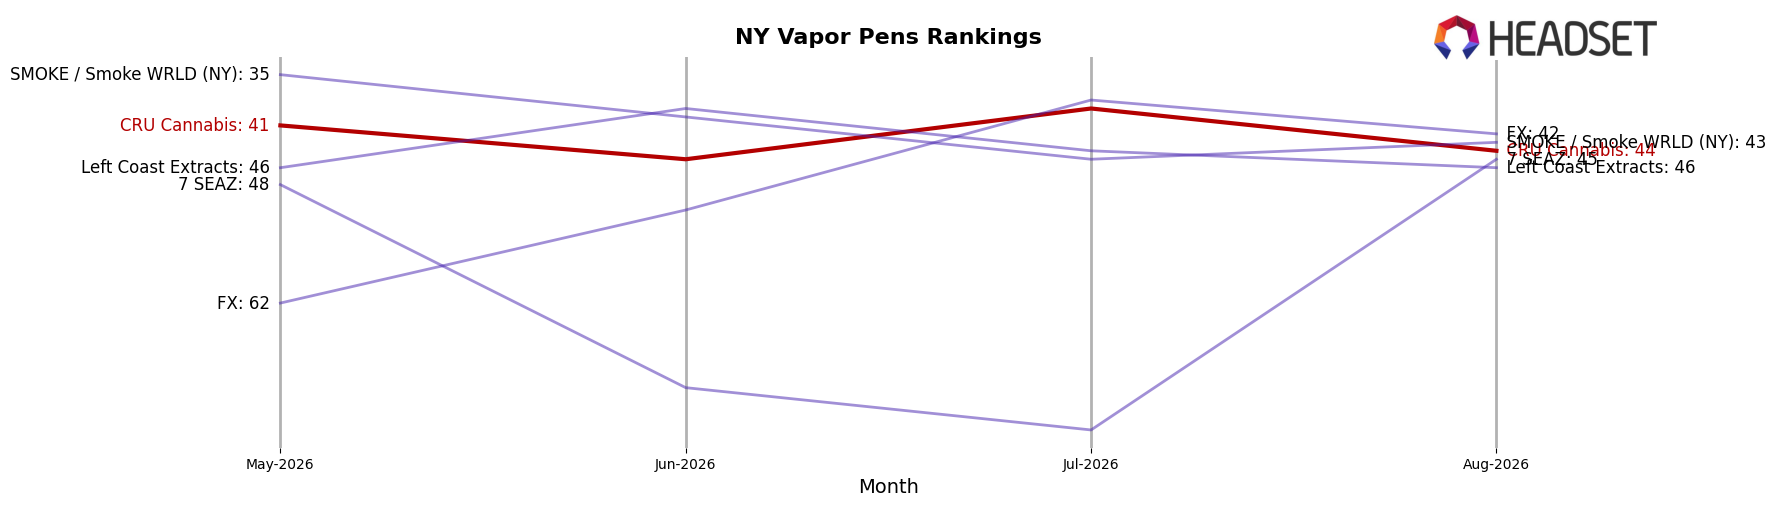
CRU Cannabis is ranked #44 in NY Vapor Pens in August 2026, down 13 positions year over year from #31, and 3 positions lower than May 2026 when it was #41; compared to its peak of #18 in August 2024, the two-year slide totals 26 ranks and indicates erosion in competitive standing. Meanwhile, Fernway moved from #3 to #1 with a 36.25% year-over-year sales increase, while Jetty Extracts climbed from #26 to #5 on 230.11% year-over-year growth, outpacing CRU Cannabis’s rank trajectory by widening the gap at the top and mid-tier. The pattern implies that CRU Cannabis’s downward rank momentum, combined with rivals ascending multiple tiers in a single year, points to share compression unless rank stabilization reverses in the next few months.
Notable Products
Pink Guava Infused Pre-Roll (0.5g) led August 2026 with a 79.6% month-over-month surge and captured rank 1, while Super Silver Haze Liquid Live Resin Diamonds Sauce Disposable (1g) fell 33.2% to rank 8. Blue Dream Infused Pre-Roll (0.5g) climbed 32.8% at rank 5, and Headband Infused Pre-Roll (0.5g) advanced 37.6% at rank 7, whereas Bubba Kush Pre-Roll (0.5g) slipped 2.2% at rank 3. With four of the top ten in the Pre-Roll category and Vapor Pens concentrated between ranks 4 and 10, the mix implies a pivot toward value-dense inhalables where rapid Pre-Roll velocity pairs with selective Vapor Pen scale.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

