

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Joos is stocked at 160 licensed dispensaries across Illinois and Missouri, 139 of them in Illinois, with the deepest coverage in Chicago, Quincy, Springfield, Champaign, and East Dubuque. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
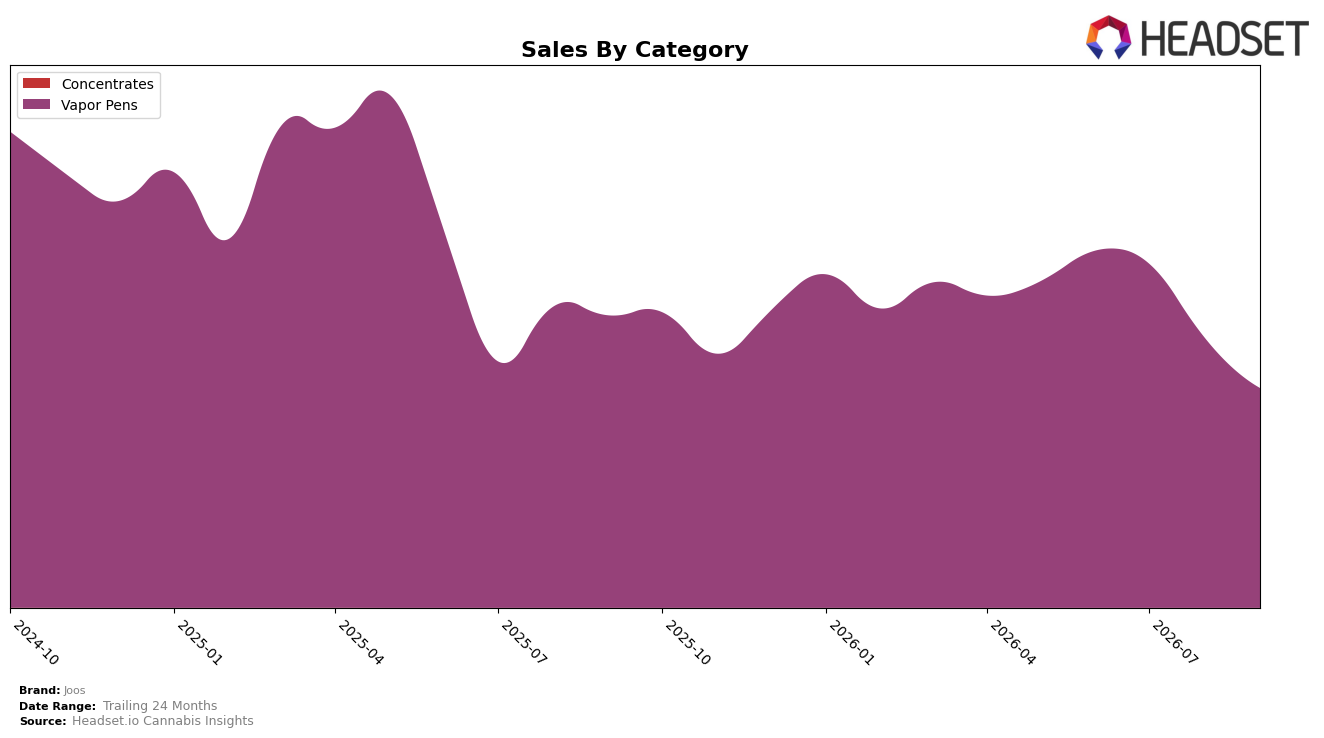
Joos operated as a single-category brand in September 2026, with Vapor Pens accounting for 100.0% of sales, while year-over-year sales declined 24.9% and month-over-month fell 18.7%. Average price rose 8.0% year-over-year even as overall brand sales contracted 24.9%, indicating mix held entirely in Vapor Pens without offset from other formats; the Vapor Pens rank in Illinois sat at 6, which juxtaposes the 18.7% monthly sales drop against a fixed category footprint. The pattern implies Joos is concentrating volume in a single lane where pricing is rising into a shrinking demand base, creating exposure to further share loss if category headwinds persist.
With 100.0% of sales in Vapor Pens and a rank of 6 in Illinois, Joos is competing from a mid-tier position while absorbing a 24.9% year-over-year decline and an 18.7% month-over-month dip, a setup that typically compresses shelf velocity faster than price can compensate. The 8.0% average price increase alongside a 44.8% two-year sales contraction signals that price-led tactics are not offsetting unit erosion within a single-category strategy; maintaining a rank of 6 under these declines implies vulnerability to displacement if neighboring ranks show even modest share capture. The implication is that Joos’s current positioning leans on price elevation within Vapor Pens rather than breadth, so defending rank will likely require either unit recovery within Vapor Pens or reintroducing secondary categories to dilute volatility.
Competitive Landscape
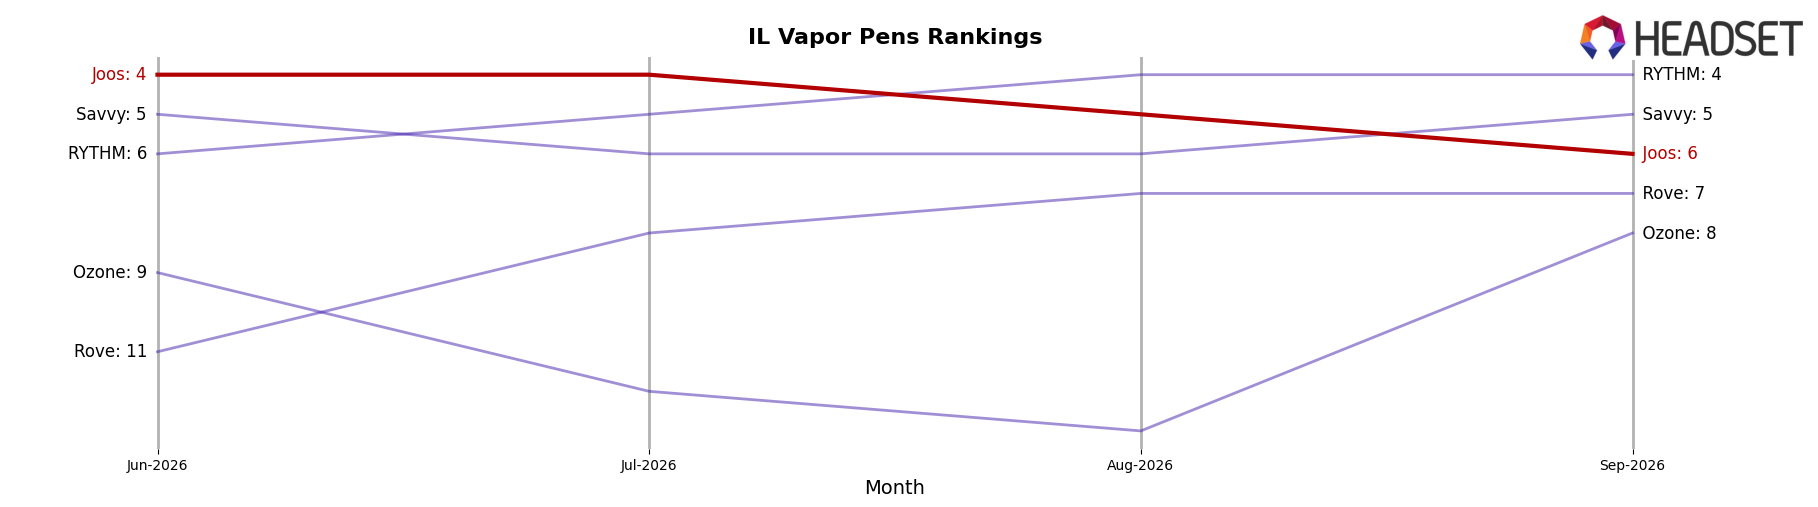
Joos sits at rank #6 in Illinois Vapor Pens in September 2026, down 2 positions year over year from #4, and down 2 positions from its June–August 2026 three-month level of #4, while still trailing its peak of #2 from May 2025; meanwhile, &Shine advanced from #2 to #1 alongside a 38.35% YoY sales lift and Fernway jumped from #13 to #3 with 308.84% YoY sales growth. In contrast, Savvy slipped from #3 to #5 with a -32.73% YoY sales change while RYTHM edged up from #5 to #4 with 44.16% YoY growth; against this mix of rapid climbers and a notable decliner, Joos’s two-rank slide since September 2025 implies erosion of relative momentum and a need to counter faster-moving entrants to avoid further share compression.
Notable Products
Northern Lights Distillate Cartridge (1g) posted the steepest movement in September 2026 with a -29.45% month-over-month drop while holding rank 3, and Green Crack Distillate Cartridge (1g) also contracted by -14.24% at rank 1. Blue Lobster Distillate Cartridge (1g) moved counter to that trend with a +23.89% month-over-month gain at rank 6, while Skywalker Distillate Cartridge (1g) fell -26.01% at rank 9. Eight of the top ten are Vapor Pens SKUs, and the top two SKUs alone accounted for $124,842, indicating a mix that is concentrated but vulnerable to sharp intra-category swings.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

