

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
&Shine is stocked at 723 licensed dispensaries across Illinois, New Jersey, and 10 other states, 154 of them in Illinois, with the deepest coverage in Chicago, Springfield, Normal, Quincy, and Schaumburg. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
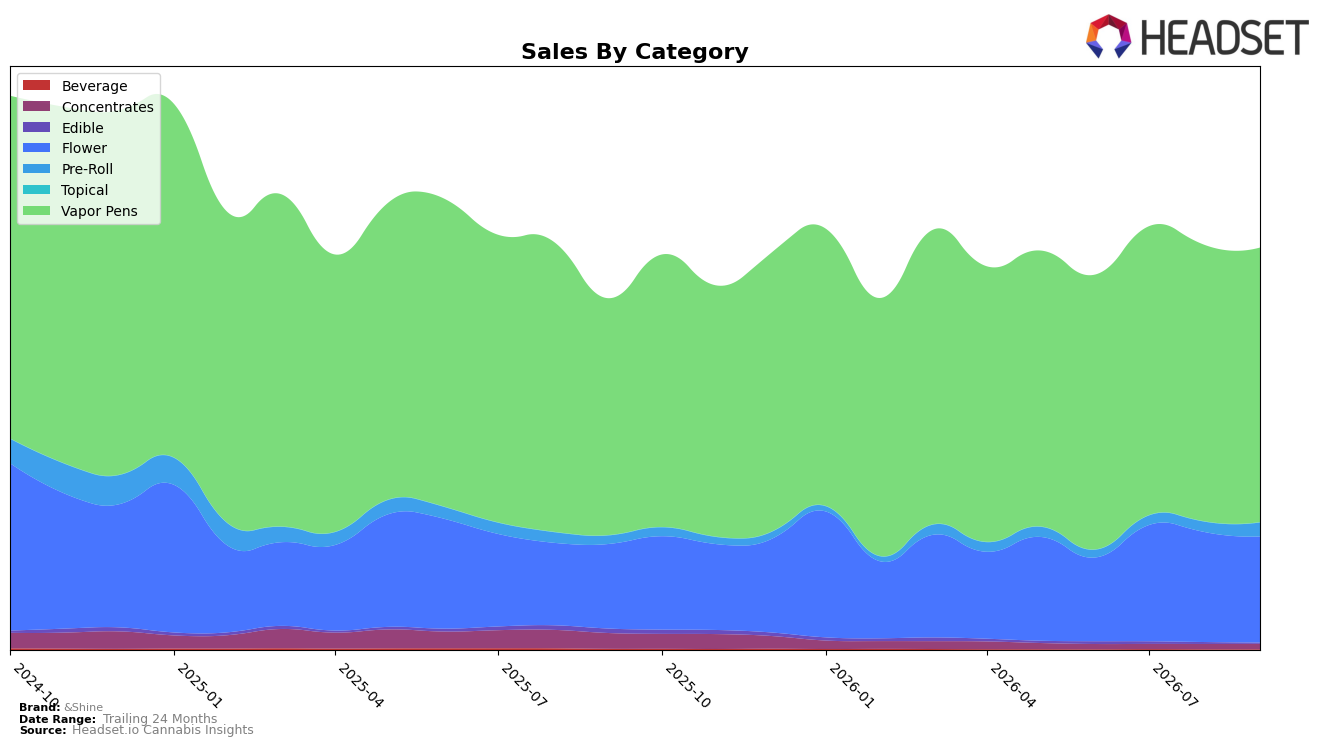
In September 2026, Vapor Pens held 68.52% share with 15.93% YoY growth and a -0.67% MoM dip, while Flower reached 26.43% share with 25.70% YoY growth and a -3.53% MoM slide; Pre-Roll, though just 3.40% share, surged 65.79% YoY and 35.90% MoM. Conversely, Concentrates fell -66.74% YoY despite a 3.23% MoM uptick, and Edible contracted -77.72% YoY with a -41.61% MoM drop; Beverage declined -49.64% YoY and -4.34% MoM. The pattern implies &Shine is consolidating around Vapor Pens and Flower while selectively expanding Pre-Roll as an on-ramp, and actively pruning or deprioritizing long-tail categories where velocity has broken, even as the brand holds a number 1 rank in Vapor Pens in Illinois.
With average price up 4.95% YoY to $32.39 alongside 14.50% YoY brand sales growth and a 24‑month decline of -23.84%, the mix tilt toward higher-ticket Flower (avg price $49.53) and premiumized Vapor Pens (avg price $33.14) suggests a margin-first posture; the simultaneous 35.90% MoM Pre-Roll lift and -3.53% MoM Flower pullback indicate a trade-down safety valve that protects unit throughput. The combination of a -0.67% MoM dip in the 68.52% Vapor Pens core and a 3.23% MoM rise in a 1.28% share Concentrates base implies controlled experimentation without jeopardizing leadership, positioning &Shine to defend price in core while using Pre-Roll momentum to rebuild the -23.84% two-year gap.
Competitive Landscape
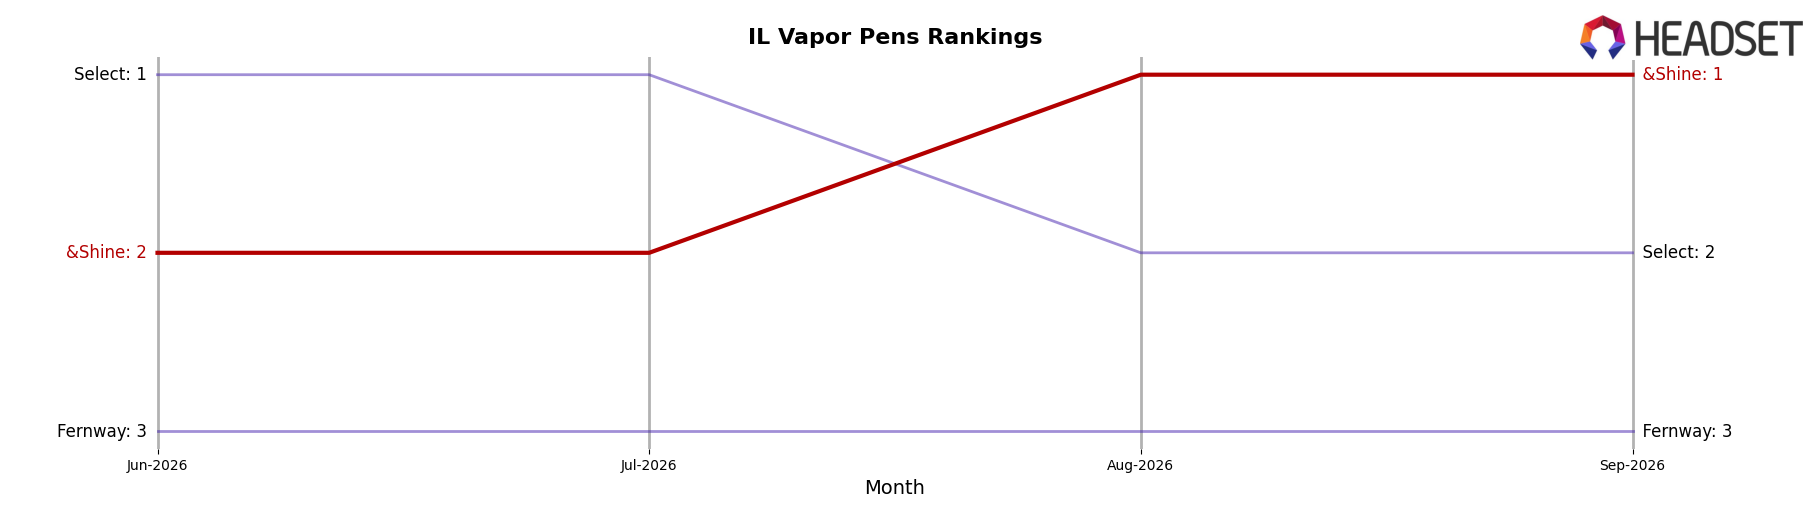
&Shine holds rank #1 in IL Vapor Pens in September 2026 after improving 1 position year over year from #2, and it moved up 1 spot versus three months ago from #2 to #1; this ascent contrasts with Select slipping from #1 to #2 despite 11.2% year-over-year sales growth and with Fernway climbing from #13 to #3 on 308.8% year-over-year sales growth, indicating &Shine’s top ranking is being defended more by relative rank stability than by outsized velocity surges from challengers.
Notable Products
Blue Dream Distillate Disposable (2g) posted the steepest decline in September 2026 at -23.0% while dropping to rank 3, and Ghost Train Haze Distillate Cartridge (1g) also contracted -12.4% at rank 10; by contrast, Northern Lights Distillate Disposable (2g) rose +30.7% to rank 1 with roughly $277,600 in sales. Eight of the top ten are Vapor Pens, and within that concentration Northern Lights Distillate Disposable (2g) outpaced Blue Dream Oil Cartridge (1g), which managed only +4.5% at rank 7; this skew toward disposables at both the top and bottom implies the mix is tilting to device-driven volatility across flavors and formats. The pattern suggests &Shine is consolidating leadership around a small set of disposable SKUs even as variability within the same strain family widens, signaling a need to prioritize winning disposable form factors while pruning underperforming cartridges.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

