
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
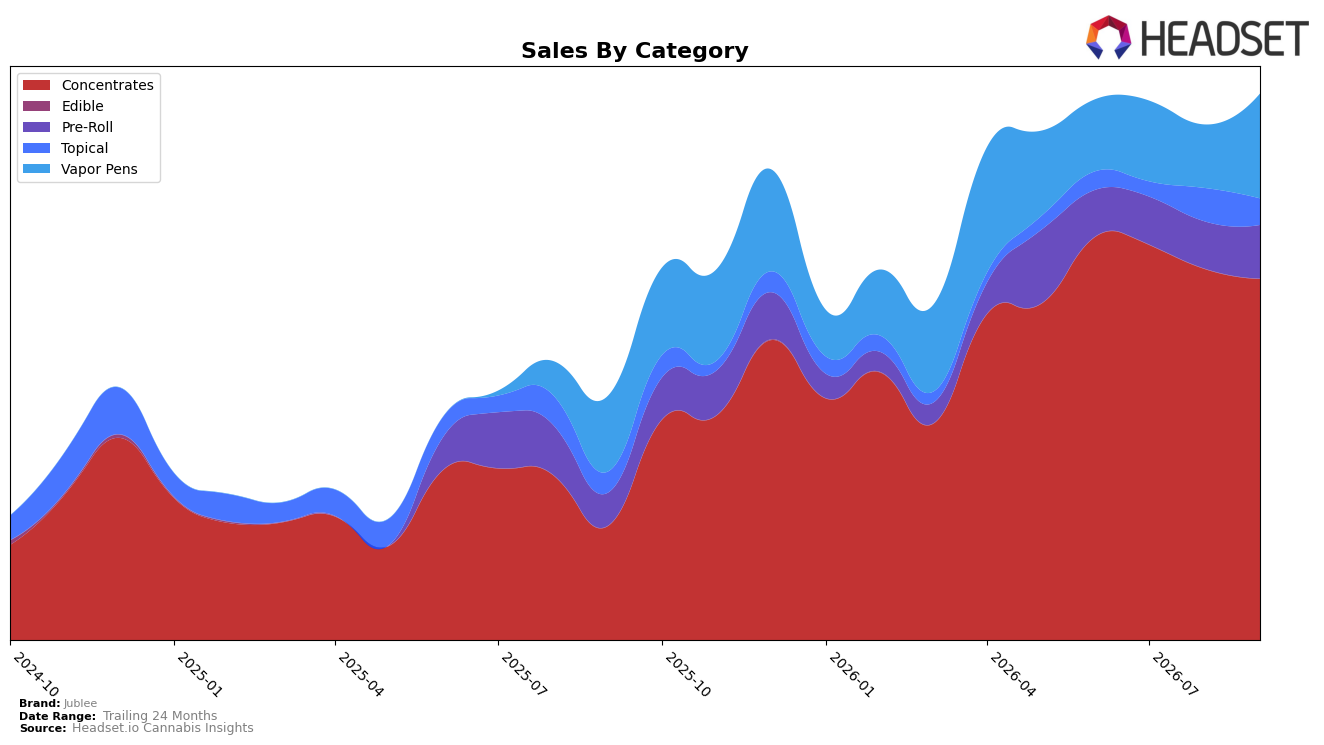
Jublee’s category mix in September 2026 tilted heavily toward Concentrates at 66.25% share with 216.57% year-over-year growth but a 2.68% month-over-month decline, while Vapor Pens held 19.17% share with 38.23% year-over-year growth and a 65.45% month-over-month surge. Pre-Roll contributed 9.77% share with 63.28% year-over-year growth and 13.52% month-over-month growth, as Topical sat at 4.81% share with 26.46% year-over-year growth but a 20.60% month-over-month drop; average price fell 6.35% year over year to $32.50, diverging from the Vapor Pens price point at $46.06. With a Concentrates rank of 28 in Ontario and brand-level year-over-year sales up 124.30%, the pattern implies a volume-led mix anchored in Concentrates but increasingly aided by a faster month-over-month contribution from Vapor Pens.
The simultaneous 2.68% month-over-month dip in Concentrates and 65.45% month-over-month lift in Vapor Pens, alongside a 13.52% month-over-month rise in Pre-Roll, suggests near-term share of growth is shifting toward inhalables with higher price points, even as the overall average price is down 6.35% year over year. Holding a 66.25% share in Concentrates while ranking 28 in Ontario indicates headroom to trade up via Vapor Pens and stabilize Topical, where a 20.60% month-over-month contraction contrasts with 26.46% year-over-year growth; this implies a positioning pivot toward balancing the high-growth base in Concentrates with premiumized Vapor Pens to sustain September 2026 momentum while reducing dependence on a single category.
Competitive Landscape
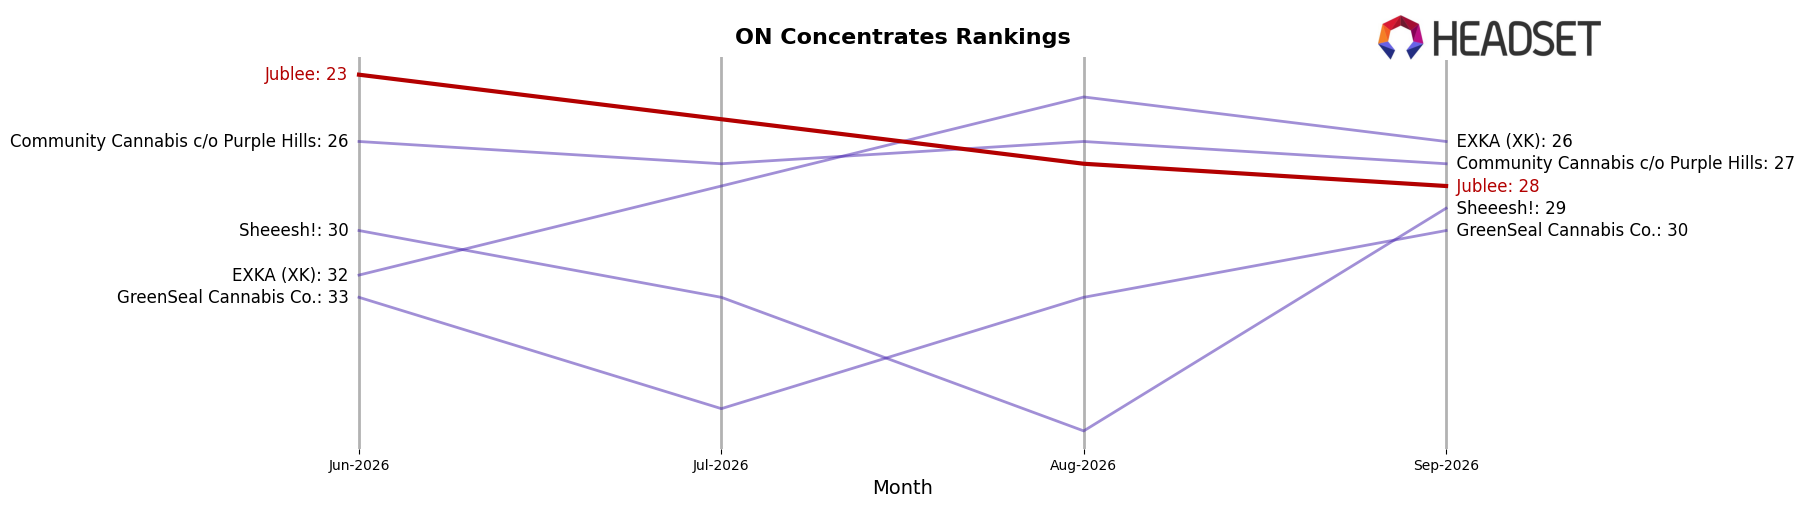
Jublee sits at rank #28 in ON Concentrates in September 2026, improving 23 positions year over year from #51 and slipping 5 spots from its three-month peak at #23 in June 2026; by contrast, Pura Vida advanced from #4 to #2 with a 37.2% YoY sales change while Nugz (Canada) dropped from #2 to #3 alongside a 30.8% YoY sales decline. With category leadership steady at Vortex Cannabis Inc. holding #1 both this year and last despite a 13.0% YoY sales contraction, and BoxHot climbing from #9 to #5 on 52.3% YoY growth, the pattern indicates Jublee’s rank recovery is real but not yet durable, implying its trajectory depends on converting the June 2026 peak into sustained gains against faster-rising incumbents.
Notable Products
CBG Bright Mind Full Spectrum Kief Infused Pre-Roll 4-Pack (2g) posted the largest swing in September 2026 with +107.9% MoM to rank 7, while CBD Sweet Citrus Extra Strength Body Butter (1000mg CBD) fell -60.1% at rank 10, indicating demand is pivoting toward infused formats over wellness topicals. Montreal Style Aged Hash (2g) held rank 1 despite a -11.0% MoM drop, and East Coast Aged Hash (2g) slid -18.7% at rank 4, so three Concentrates in the top six are losing share even as a Vapor Pens SKU, CBG Sweet Citrus Bright Mind Distillate Broad Spectrum Disposable (1.2g), jumped +65.4% at rank 3. With four of the top ten coming from Concentrates, the mix is tilting toward innovation-led inhalables where infused pre-rolls and functional vapes are gaining traction at the expense of legacy hash and body-care, pointing Jublee toward higher-velocity inhalable development over slower-turn topicals.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

