

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
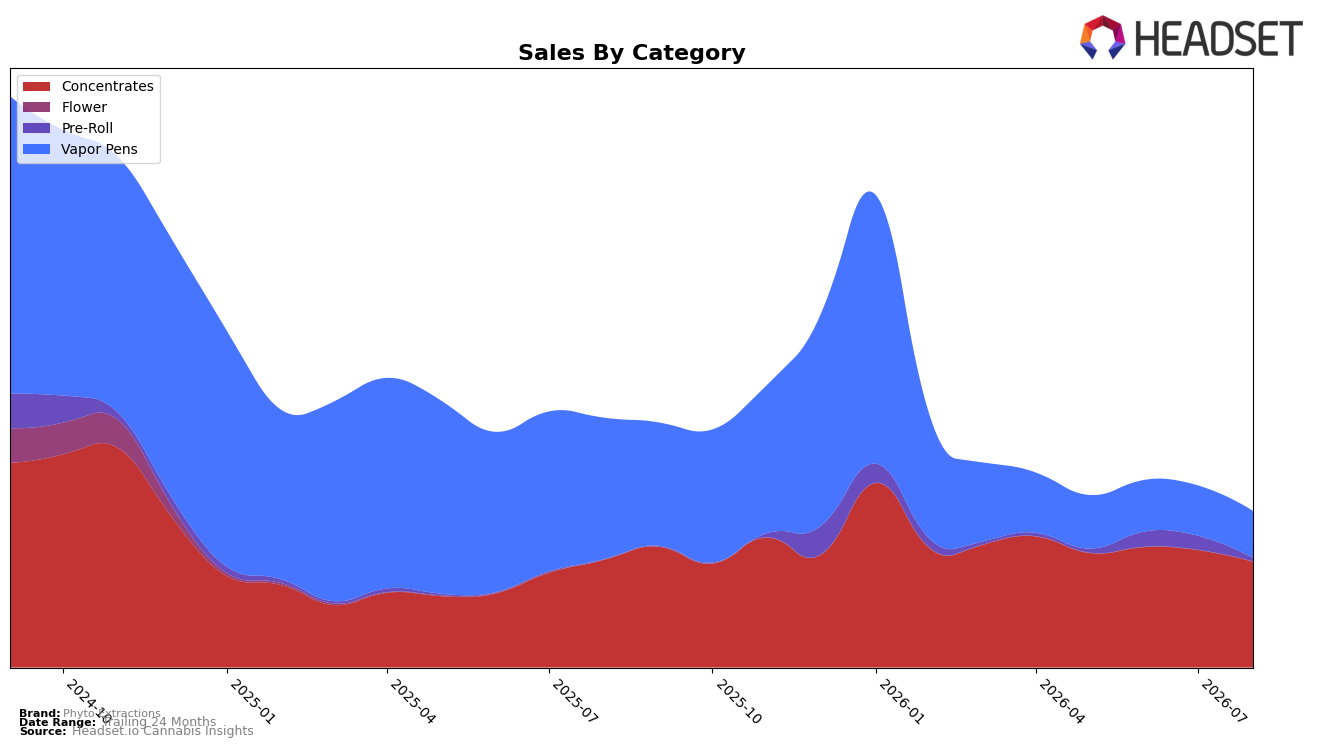
In August 2026, Concentrates accounted for 67.84% of Phyto Extractions sales with a year-over-year decline of 1.84% and a month-over-month drop of 9.95%, while Vapor Pens comprised 30.16% with a steeper 66.78% YoY decline and a 6.36% MoM decrease; Pre-Roll held 2.00% after a 1,871.90% YoY surge but fell 77.46% MoM. The brand’s average price decreased 10.82% YoY to $23.95, and within Concentrates the average price sat at $23.14 versus $28.18 in Vapor Pens, indicating mix pressure as the higher-declining Vapor Pens segment still represents nearly a third of sales. This pattern implies the current portfolio leans on a shrinking core in Concentrates while carrying exposure to a sharper slide in Vapor Pens, leaving limited buffer despite a temporary Pre-Roll spike that lacks MoM follow-through.
Ranked 22 in Concentrates in Alberta, the combination of a 67.84% category share and a 9.95% MoM dip positions Phyto Extractions as a mid-pack player whose monthly volatility can materially shift rank, and the 66.78% YoY decline in Vapor Pens suggests insufficient traction in an adjacent format to offset core softness. With brand-level sales down 37.51% YoY and price down 10.82% YoY, the pricing posture does not appear to be unlocking volume at a pace that compensates for category-specific declines. The implication is that sustaining or improving category rank will require concentrating resources on stabilizing Concentrates while reframing the role of Vapor Pens from a volume driver to a selective, margin-aware presence until demand signals turn.
Competitive Landscape
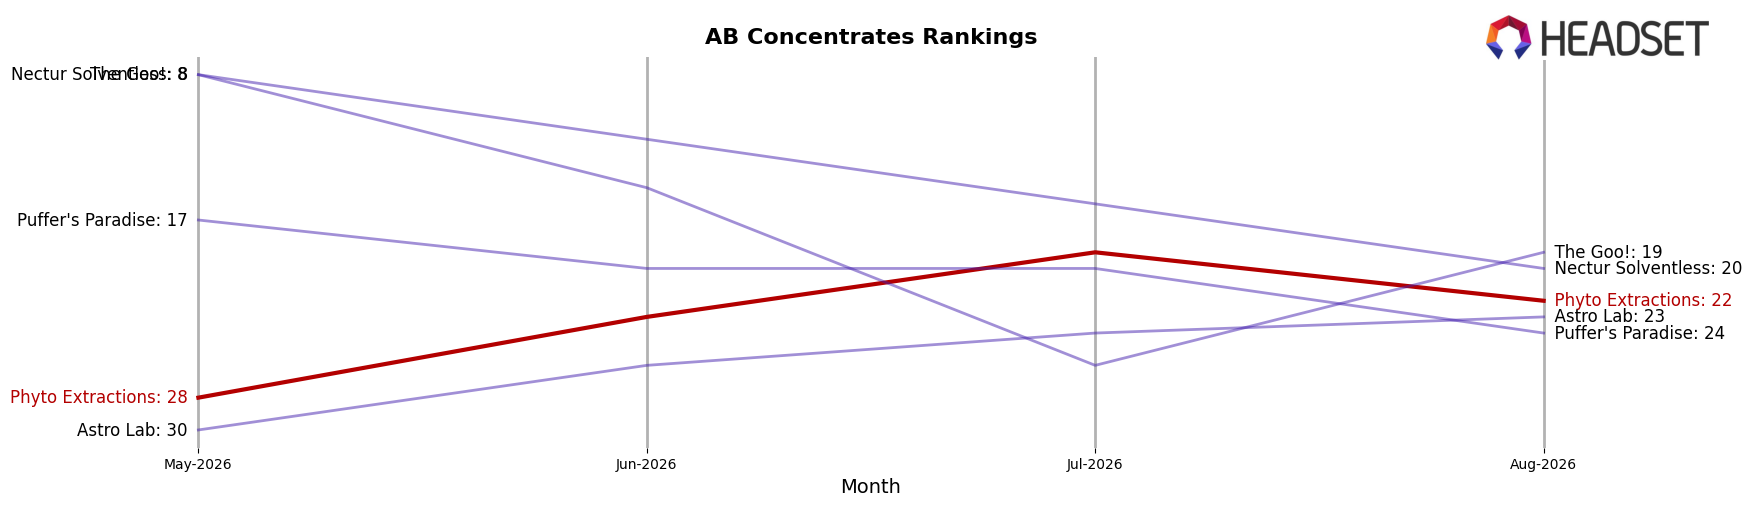
Phyto Extractions is currently ranked #22 in AB Concentrates in August 2026, down 2 positions year over year from #20, but up 7 places from #29 three months ago; against a historical peak of #11 in September 2024, the brand’s present slot is 11 ranks lower. Competitively, BoxHot held at #1 year over year while its sales declined 2.6%, and Sticky Greens vaulted from #49 to #5 with a 1,486.7% sales increase, indicating momentum is concentrating in faster-rising rivals. This mix of a modest YoY rank slip (from #20 to #22) alongside a recent quarter lift (from #29 to #22) implies Phyto Extractions is stabilizing short term but ceding multi-year position to brands accelerating up the table.
Notable Products
Alien Trufflez Shatter (1g) posted the steepest decline in August 2026 at -48.3% MoM while sliding to rank 3, even as Ice Wreck Shatter (1g) surged +149.7% MoM to rank 1 and captured $60,191. With Phyre Shatter (1g) down -30.6% at rank 5 and three Pre-Roll SKUs each falling between -61.9% and -84.4% at ranks 6–8, the category split reveals volatility concentrated outside the lead SKU. Fire Stick - Slurriking Distillate Cartridge (1g) softened -4.5% at rank 2 as Grape Stomper Distillate Cartridge (1g) dropped -24.4% to rank 4, indicating Vapor Pens are ceding share to the breakout Concentrates leader. The pattern implies Phyto Extractions is consolidating revenue around a single high-velocity Concentrates SKU while Pre-Rolls contract, signaling a pivot toward potency-led shatter offerings over breadth across formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

