

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
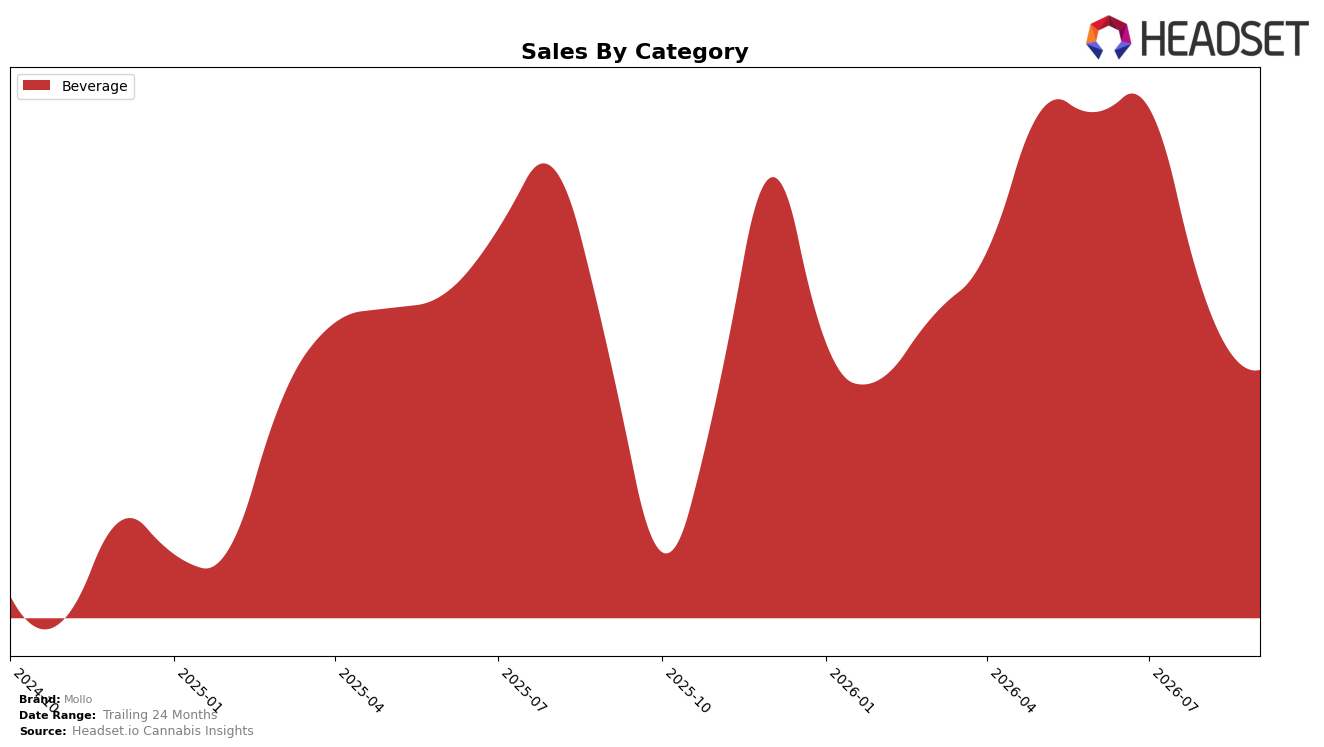
In September 2026, Mollo’s sales were concentrated entirely in Beverage with a 100.0% category share, while category sales were down 1.4% year over year and down 5.3% month over month. Average price rose 16.5% year over year to $7.54, as overall brand sales declined 1.4% year over year and slipped 5.3% month over month within Beverage. The mix staying at 100.0% Beverage alongside a -5.3% month-over-month volume contraction and a 16.5% price lift implies a pricing-led approach within Beverage that is not offset by category diversification.
Ranked 2 in Beverage in British Columbia, Mollo’s single-category focus raises exposure to Beverage-specific swings, as indicated by the 5.3% month-over-month dip and 1.4% year-over-year decline. With average price up 16.5% year over year and a 24.6% two-year sales gain, the brand’s positioning leans on price and distribution depth rather than cross-category insulation, implying that sustaining a number 2 rank will depend on defending price architecture in Beverage while mitigating month-level volatility.
Competitive Landscape
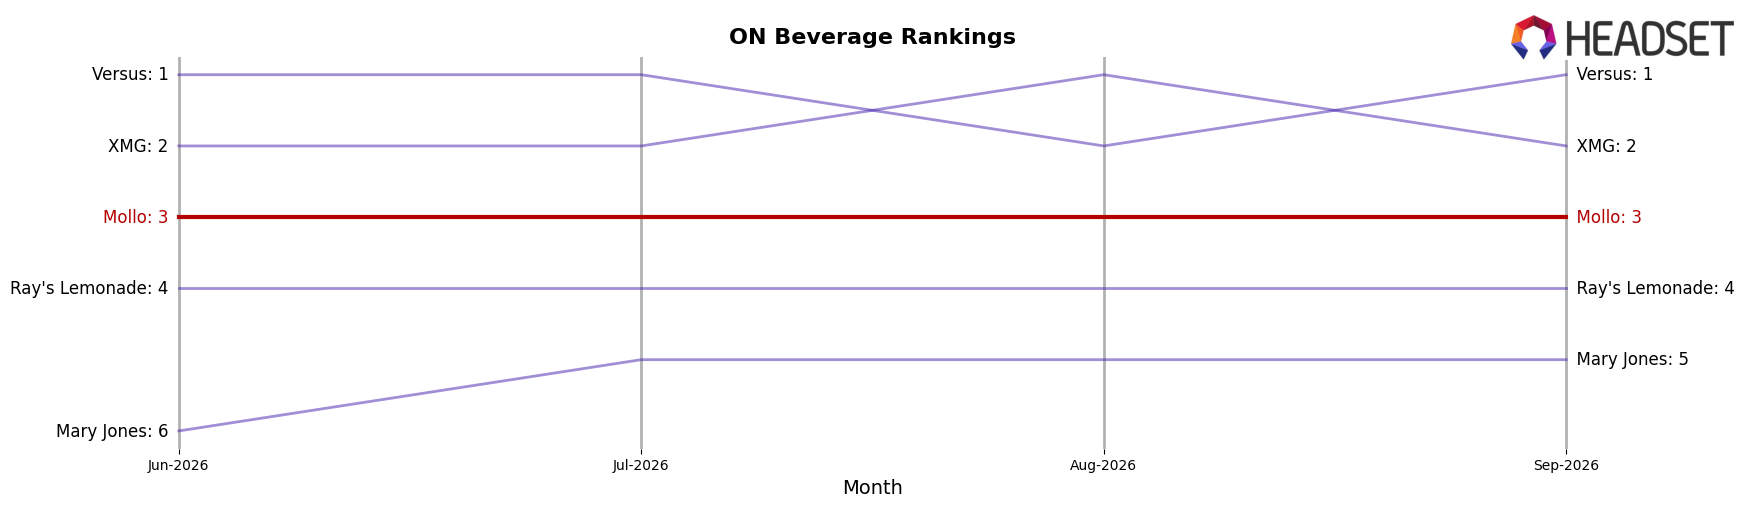
Mollo is currently ranked #3 in ON Beverage in September 2026, unchanged from #3 year over year, and unchanged from #3 over the past three months, while its peak of #2 came in August 2025; in contrast, Versus sits at #1 after rising from #2 year over year with sales up 9.7%, and XMG slipped to #2 from #1 with sales down 20.5%, indicating the top tier is redistributing share without Mollo moving ranks. With Ray's Lemonade holding #4 with 20.4% year-over-year sales growth and Mary Jones advancing to #5 from #8 on 53.6% growth, Mollo’s static #3 suggests stable placement but rising pressure from below could compress its path back to the #2 peak unless it converts category growth into rank gain.
Notable Products
CBG/THC 2:1 Watermelon Lime Seltzer (20mg CBG, 10mg THC, 12oz, 355ml) posted the sharpest move in September 2026 with a -24.8% MoM decline and slid to rank 3, while CBG/THC 2:1 Strawberry Guava Seltzer fell -38.9% MoM to rank 7, pointing to flavor fatigue in the 2:1 fruit line. In contrast, CBG/THC 2:1 Blackberry Seltzer 4-Pack (20mg CBG, 10mg THC, 355ml) grew 5.1% MoM to hold rank 1 and remains the only top-three SKU with positive momentum, capturing the highest basket contribution at approximately $135,351. Four of the top ten are 2:1 fruit seltzers, yet three of those logged double-digit MoM declines between -16.3% and -38.9% while the two 4-Packs at ranks 1 and 10 rose 5.1% and 6.9%, respectively, indicating a channel shift toward multipacks over single cans. The pattern implies Mollo’s commercial direction is consolidating around value-oriented 4-Packs and away from slower single-can fruit variants, suggesting portfolio emphasis on multipack formats and fewer overlapping 2:1 flavors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

