

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
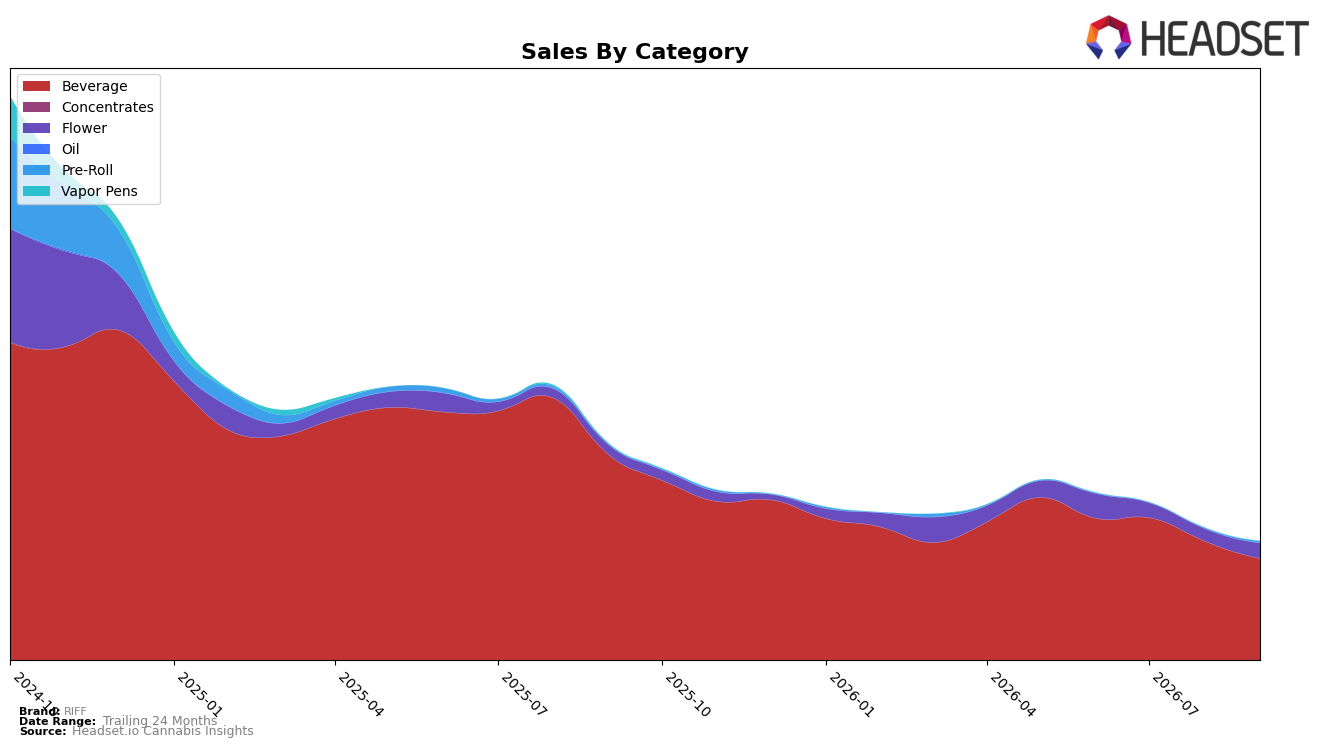
In September 2026, Beverage carried 85.99% share with a year-over-year decline of 50.75% and a month-over-month drop of 14.70%, while Flower rose to 12.76% share on 60.87% YoY and 25.36% MoM growth; Pre-Roll, though only 1.25% share, surged 162.86% YoY and 263.09% MoM. Against a brand-level sales decline of 45.46% YoY and a 24-month contraction of 82.52%, the category mix is tilting away from a shrinking Beverage core (average price $6.54) toward higher-priced Flower (average price $26.42) and a fast-accelerating Pre-Roll entry, implying the brand is leaning into smaller but faster-growing formats to offset core erosion.
Average price rose 8.22% YoY to $7.26 while the Beverage-heavy base contracted, and the brand sat at rank 20 in Beverage in Ontario, indicating reliance on a declining anchor category may cap visibility as consumers migrate to Flower and Pre-Roll. The combination of a 14.70% MoM Beverage decline with 25.36% MoM Flower growth and 263.09% MoM Pre-Roll growth suggests repositioning toward premiumized and convenience formats, with the thesis that mix-driven margin potential can rise even as total volume contracts unless Beverage stabilization occurs.
Competitive Landscape
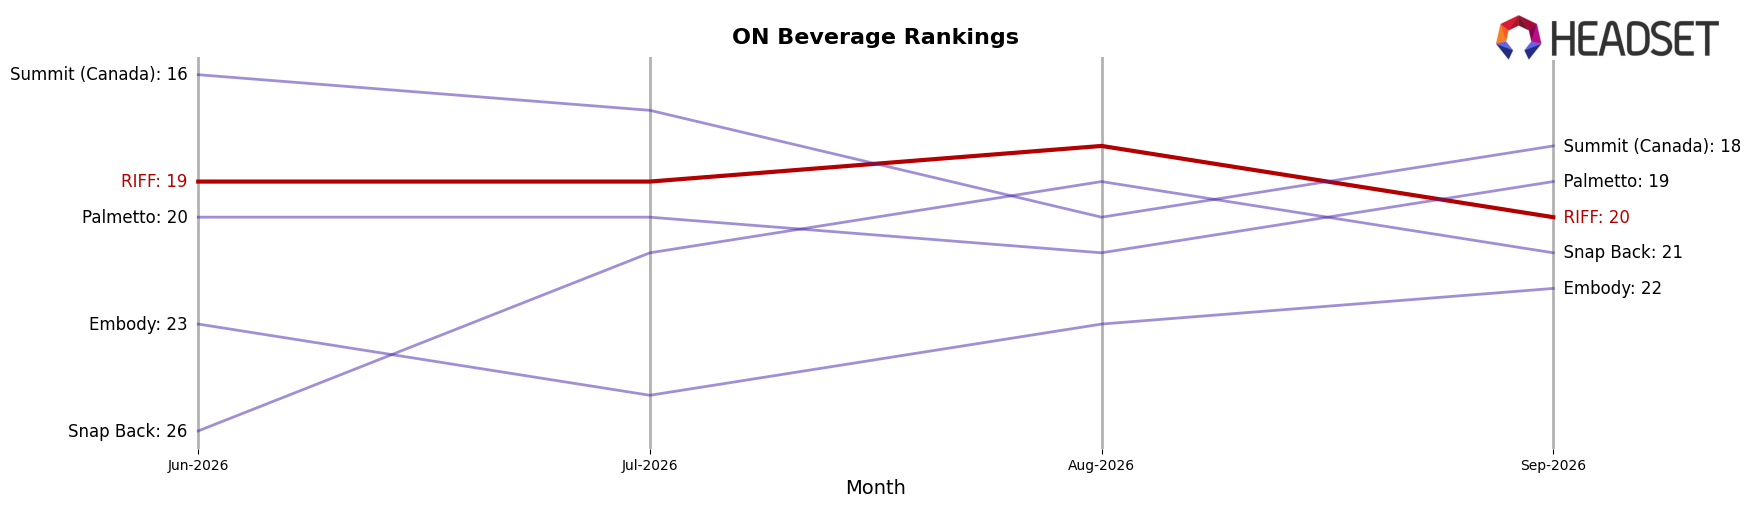
RIFF ranks #20 in ON Beverage in September 2026, down 3 positions year over year from #17 and slipping 1 spot versus June 2026’s #19, while its peak of #12 in September 2024 marks an 8-rank slide since that high. In contrast, Versus holds #1 after improving from #2 with 9.7% year-over-year sales growth, and XMG fell from #1 to #2 alongside a 20.5% sales decline, indicating leadership churn at the top even as mid-tier ranks like #20 become stickier. With Mary Jones climbing from #8 to #5 on 53.6% growth and Ray's Lemonade steady at #4 with 20.4% growth, RIFF’s 3-position YoY drop and 8-rank decline since September 2024 imply erosion in relative velocity that will be hard to reverse without share-capturing moves in faster-growing segments.
Notable Products
Animal Soap Pre-Roll (1g) posted the largest month-over-month surge at +262.6% and climbed into rank 6, while Boost- THC/CBG 1:1 Vanilla Frost Carbonated Drink (10mg THC, 10mg CBG, 12oz, 355ml) jumped +152.4% to rank 5. In contrast, Blue Raspberry Ice Lemonade (10mg THC, 355ml) fell -23.9% at rank 2 and Boost- THC/CBG 1:1 Tropical Burst Carbonated Drink (10mg THC, 10mg CBG 355ml) declined -48.3% at rank 3; four of the top ten are Beverage SKUs, yet the sharp split between +152.4% growth and -48.3% contraction signals shifting flavor and formulation preferences within the same format. Wild Raspberry Lemonade (10mg THC, 355ml) held rank 1 despite a -6.1% dip, and the category mix now includes a rising Pre-Roll, indicating RIFF is diversifying beyond core Beverage demand concentration and should lean into high-velocity novelties while pruning lagging Beverage variants.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

