


Where to Buy
Smokes / The Grow is stocked at 34 licensed dispensaries across Oregon, with the deepest coverage in Salem, Medford, Klamath Falls, Portland, and Bend. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
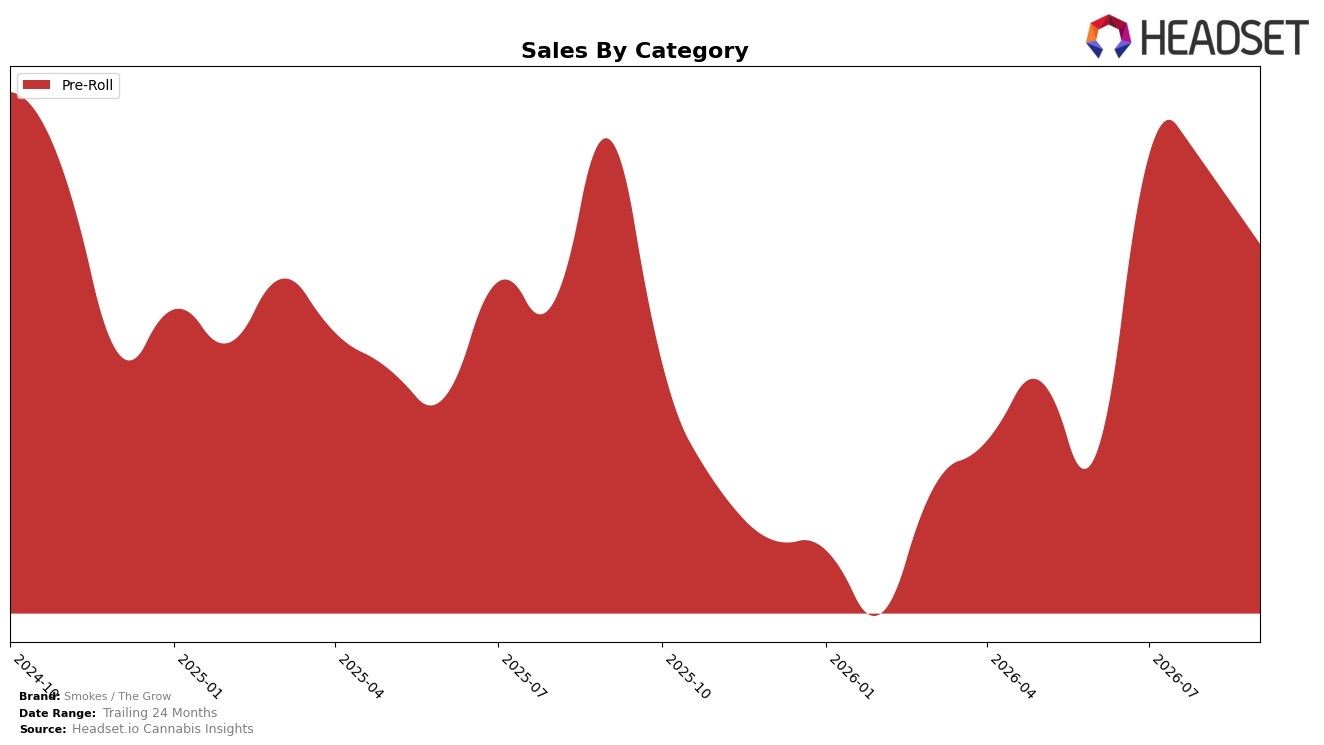
In September 2026, Smokes / The Grow was entirely concentrated in Pre-Roll, with a 100.0% category share and a -13.08% year-over-year decline alongside a -10.18% month-over-month drop, while the brand’s average price fell -76.22% YoY to $4.11. Within Oregon Pre-Rolls, the brand sat at rank 17, pairing that rank with a single-category focus that amplifies exposure to Pre-Roll volatility; the pattern implies price-led volume defense is insufficient to offset demand softness when all sales are tied to one category.
The combination of a 100.0% Pre-Roll mix and a rank position of 17 in Oregon suggests the sharp -76.22% YoY price cut is functioning as a tactical floor rather than an engine for share capture, given the -13.08% YoY and -10.18% MoM sales declines. With no balance from other categories and a single-state anchor implied by the top-state signal, the brand’s positioning skews toward price-sensitive segments where incremental discounting risks diminishing returns; the implication is that stabilizing rank and reversing the double-digit declines will likely require mix expansion or differentiation levers beyond further price compression.
Competitive Landscape
Smokes / The Grow ranks at #17 in Oregon Pre-Roll for September 2026, down 2 positions year over year from #15, but up 11 positions since June 2026 when it sat at #28; the brand also matched its peak at #15 in August 2026 before sliding 2 spots into the current month. Competitors moved in diverging directions: Kaprikorn advanced from #6 to #2 alongside a 159.98% year-over-year sales increase, while Hellavated slipped from #2 to #3 with a -27.05% sales change; at the top, STiCKS held #1 year over year with a 91.71% lift. The pattern—mid-year surge from #28 to #15 followed by a 2-rank pullback to #17—implies momentum exists but is being outpaced by faster-climbing rivals, signaling the need to sustain share gains against brands accelerating into the top five.

Notable Products
Motor Breath Pre-Roll (1g) posted the largest month-over-month swing in September 2026 at +64.1%, climbing into rank 4 while Pineapple Express Pre-Roll (1g) fell 49.9% to rank 2, indicating volatility concentrated at the top of the lineup. Tangie Pre-Roll (1g) held rank 1 with a modest +3.4% while Blackberry Pre-Roll (1g) dropped 48.3% at rank 3, and five of the top five are Pre-Roll SKUs, pointing to a category-heavy mix despite divergent trajectories. With Super Lemon Haze Pre-Roll (1g) up 35.8% at rank 5 and Superboof Pre-Roll (1g) down 23.1% at rank 7, the spread suggests flavor-specific demand that rewards select strains even as adjacent options underperform. The pattern implies Smokes / The Grow is leaning into breadth within Pre-Rolls rather than cross-category balance, using fast-moving strains to offset sharp laggards and monetize the format concentration.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

