

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Anthologie is stocked at 121 licensed dispensaries across New Jersey, Massachusetts, and Arizona, 71 of them in New Jersey, with the deepest coverage in Bridgeton, Camden, Evesham, Gloucester Township, and Runnemede. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
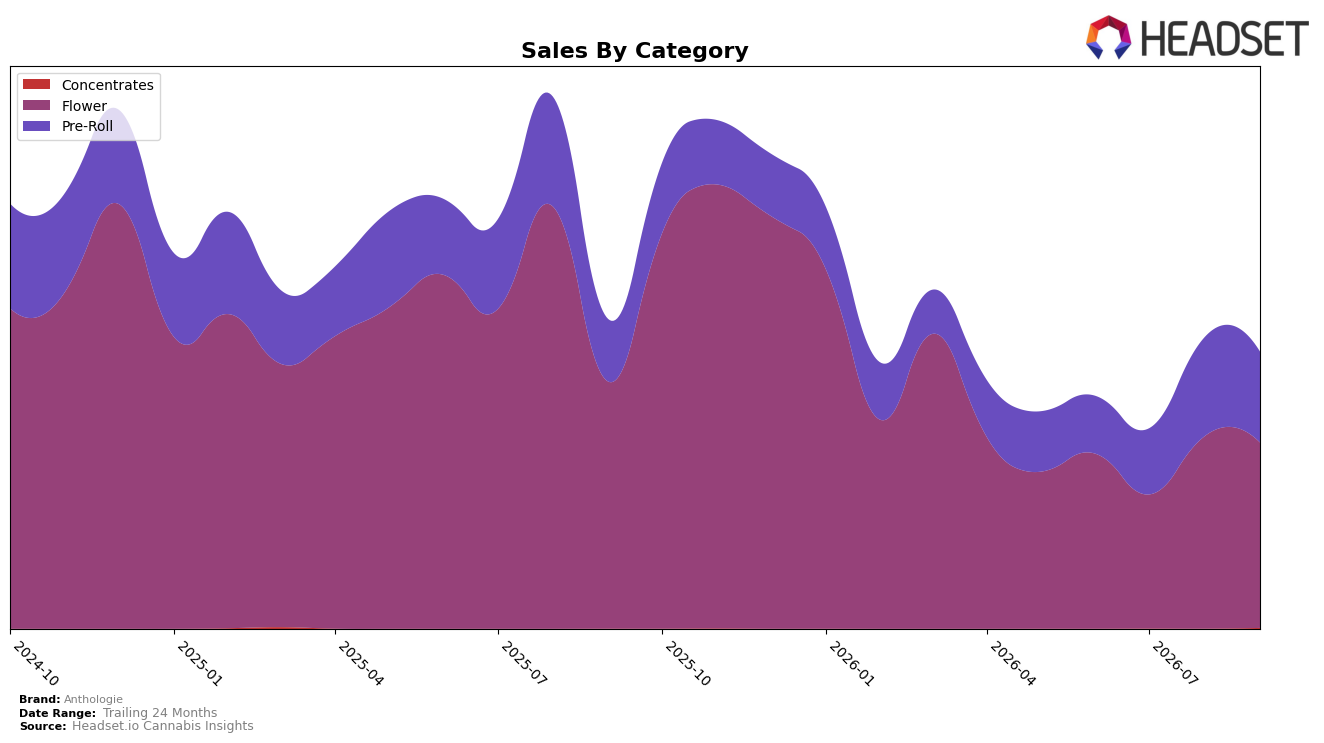
Anthologie’s mix in September 2026 concentrated 66.93% of sales in Flower with year-over-year contraction of 24.99% and month-over-month decline of 3.65%, while Pre-Roll held 32.76% share with 45.68% year-over-year growth but an 8.24% month-over-month dip; Concentrates remained a rounding error at 0.31% share despite triple-digit surges of 697.18% year-over-year and 490.64% month-over-month. Average price fell 13.63% year over year to $20.24 alongside a Flower category rank of 27 in New Jersey, indicating that mix is tilting toward lower-priced, higher-velocity formats even as the core Flower pillar softens, which implies a portfolio rebalancing driven by price compression and format substitution.
With Flower’s shrinking performance (down 24.99% year over year and 3.65% month over month) contrasted against Pre-Roll’s share at 32.76% and 45.68% year-over-year growth, the brand’s positioning is drifting from premium Flower toward value-accessible, convenience-led formats, further reinforced by a 13.63% year-over-year average price reduction. Holding rank 27 in New Jersey Flower while Pre-Roll gains share suggests the brand is trading rank stability in its largest category for broader basket reach, and the outsized but tiny-base growth in Concentrates (697.18% year over year and 490.64% month over month at 0.31% share) implies cautious experimentation rather than scale, pointing to a strategy where sustaining relevance hinges on accelerating Pre-Roll depth while selectively defending Flower price-pack architecture.
Competitive Landscape
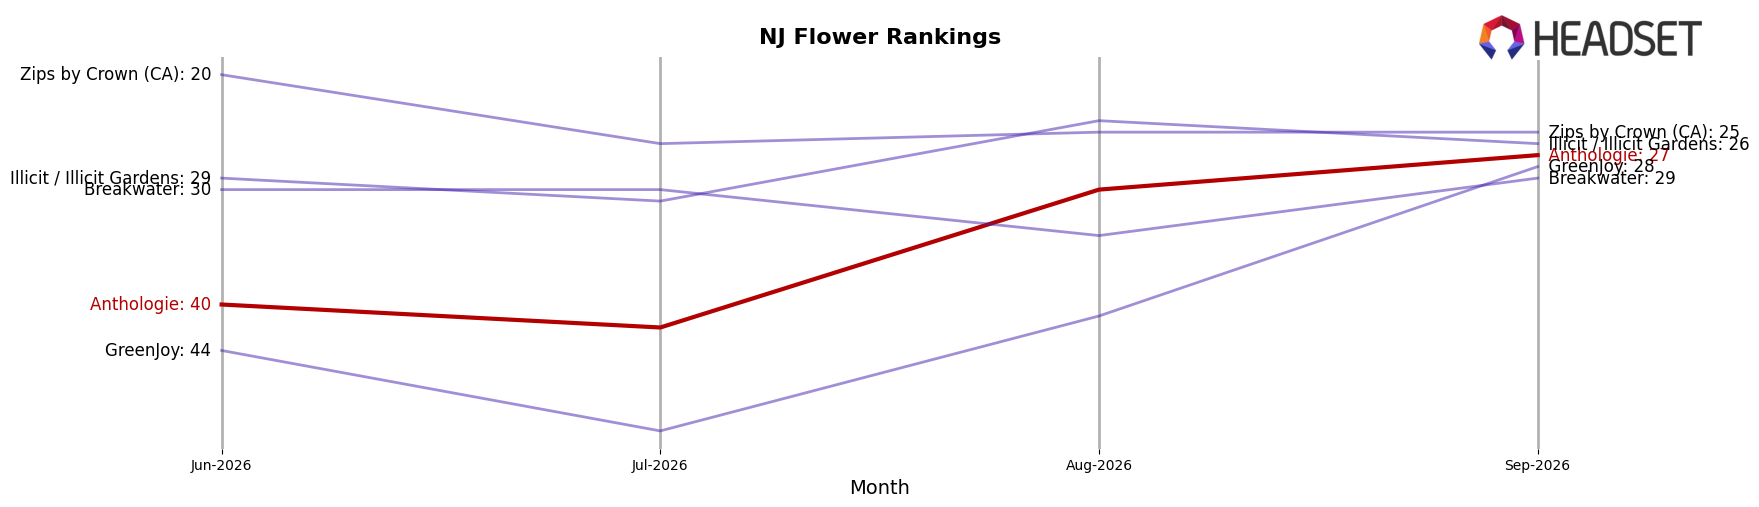
Anthologie sits at rank #27 in New Jersey Flower for September 2026, improving 3 positions year over year from #30 and rising 13 spots since June 2026 from #40, while remaining 8 places below its peak of #19 reached in November 2025; in contrast, Find. climbed from #6 to #1 with 111.6% YoY sales growth and Ozone held near the top at #2 despite a -2.8% YoY sales decline, indicating that Anthologie’s rank recovery is outpacing mid‑tier churn but still trails the acceleration seen at the category’s leaders, implying a stabilization phase with upside only if momentum extends beyond recent quarter gains.
Notable Products
JMO Pre-Roll (1g) posted the steepest move with a -66.4% MoM decline to rank 9, while AJ's Sour Diesel Pre-Roll (1g) also fell -55.4% at rank 6, indicating sharp volatility at the lower end of the top 10. In contrast, Local Skunk (3.5g) gained 54.5% MoM to rank 3, and Local Skunk Pre-Roll (1g) rose 47.9% to rank 2, with the Pie Scream Pre-Roll (1g) up 33.2% at rank 1. Seven of the top ten are Pre-Roll SKUs, and within that cluster the spread between rank 1 growth of 33.2% and rank 9 decline of -66.4% implies a portfolio leaning into Pre-Rolls that drive traffic but with SKU-level churn that will favor a narrower lineup anchored by Local Skunk formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

