

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Bacon Buds is stocked at 88 licensed dispensaries across Washington, with the deepest coverage in Vancouver, Seattle, Tacoma, Bellingham, and Olympia. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
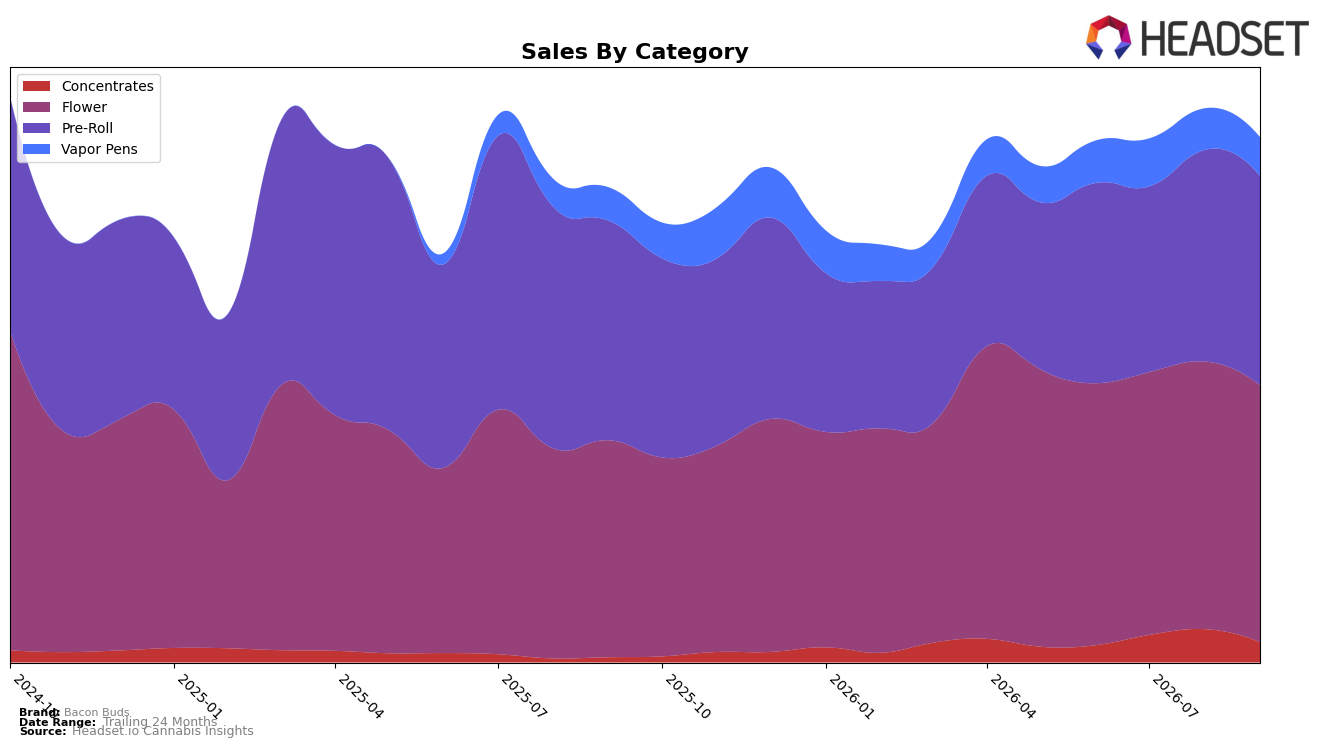
In September 2026, Bacon Buds concentrated nearly half of sales in Flower at 48.98% share with 18.48% year-over-year growth, while month-over-month dipped 3.97%; Pre-Roll held 39.89% share with a 4.71% year-over-year decline and a 1.02% month-over-month decline. Vapor Pens accounted for 7.33% share with 16.05% year-over-year growth but a 7.16% month-over-month pullback, and Concentrates reached 3.80% share on a 305.24% year-over-year surge despite a 39.67% month-over-month drop. With overall brand sales up 10.55% year over year and average price up 21.84% amid a $14.49 basket, this mix implies Bacon Buds is leaning into higher-velocity Flower and selectively expanding in Concentrates, while moderating Pre-Roll exposure as short-term demand softens.
The shift toward Flower at rank 37 in Washington alongside a 18.48% year-over-year gain and a 3.97% month-over-month dip suggests a scale-first stance in a mid-tier position, using category depth to stabilize share. The 305.24% year-over-year spike in Concentrates paired with a 39.67% month-over-month decline, and the 16.05% year-over-year rise in Vapor Pens offset by a 7.16% month-over-month slide, indicate opportunistic testing that lifts annual growth but introduces near-term volatility; the strategic implication is to codify repeatable assortment in Concentrates and Vapor Pens while defending the 48.98% Flower anchor to improve rank efficiency against price-led trade-ups.
Competitive Landscape
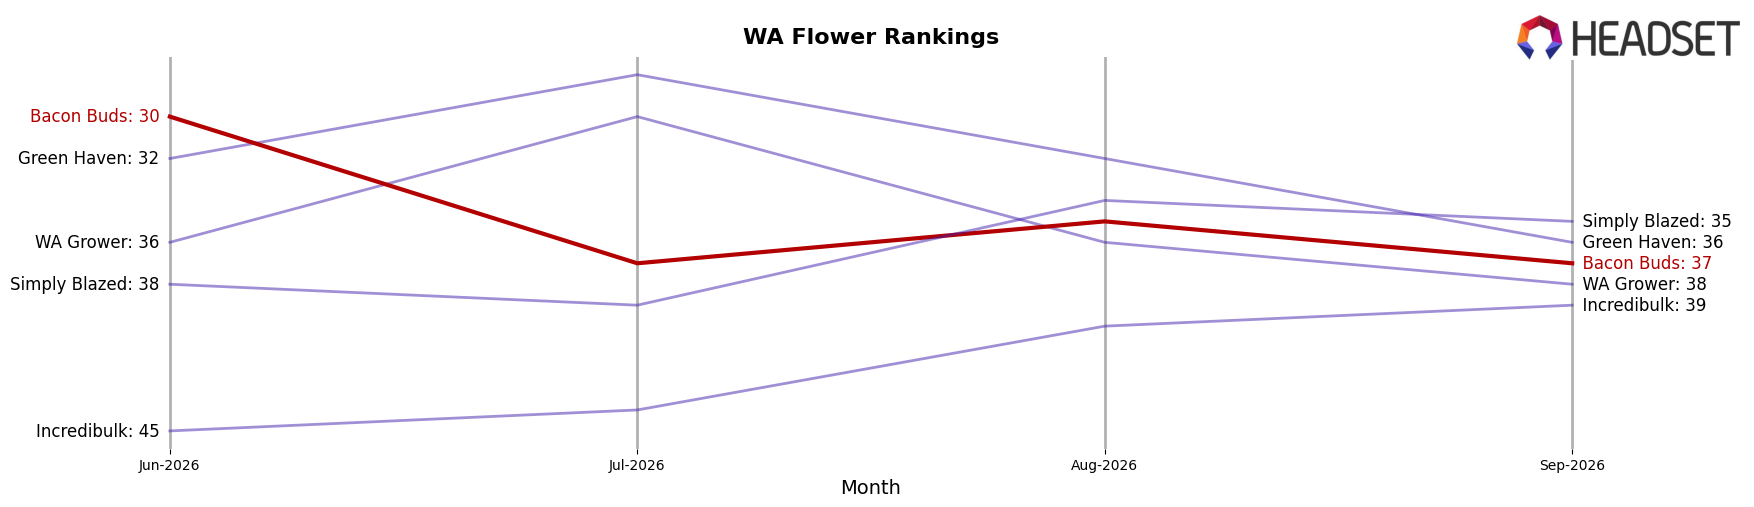
Bacon Buds sits at rank #37 in WA Flower in September 2026, a 2-position improvement from #39 year over year, but down 7 spots from #30 in June 2026 when it hit its peak rank; this mixed trajectory contrasts with Phat Panda holding #1 with +18.99% YoY sales and Hemp Kings vaulting from #24 to #5 on +105.09% YoY sales, while Legends stayed at #2 despite a -16.90% YoY sales change. Compared with Mama J's moving from #4 to #3 and Lifted Cannabis Co rising from #6 to #4 on +6.27% YoY sales, Bacon Buds’ YoY rank uptick alongside a 3-month slide from #30 to #37 implies momentum has shifted toward faster-climbing incumbents and challengers, signaling that near-term share defense likely requires reactivation where it briefly peaked.
Notable Products
Legend of Nigeria (3.5g) posted the steepest decline at -17.9% and slid to rank 7, while Big Smooth (3.5g) fell -20.1% at rank 10, indicating demand is shifting away from Bacon Buds’s Flower even as the top line is carried elsewhere. In contrast, Big Smooth Pre-Roll 2-Pack (1g) surged +38.3% to rank 2 and Legend of Nigeria Pre-Roll 2-Pack (1g) rose +6.5% at rank 1, showing momentum concentrated in Pre-Roll formats. Seven of the top ten are Pre-Roll SKUs, and within that group Moon Pie Pre-Roll 2-Pack (1g) dipped -3.4% at rank 5 while Clementine Pre-Roll 2-Pack (1g) dropped -12.8% at rank 9, pointing to selective consumer trade-up into a few lead strains rather than broad category lift. The mix implies Bacon Buds is being pulled toward a Pre-Roll-led strategy anchored by two hero strains, with Flower’s double-digit declines signaling a need to defend premium eighths or accelerate format conversion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

