

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
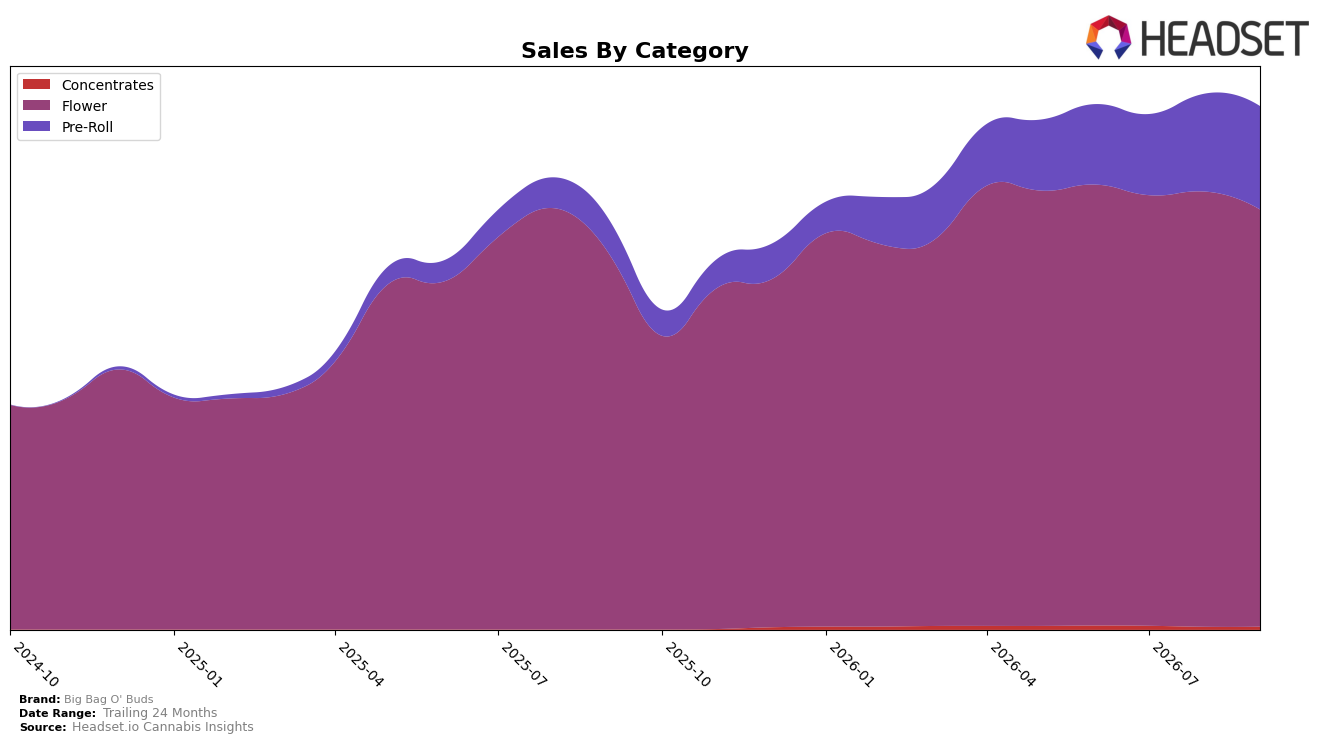
In September 2026, Big Bag O' Buds concentrated 79.75% of sales in Flower while Pre-Roll accounted for 19.71% and Concentrates held 0.53%, indicating a category mix that both widened and deepened. Flower grew 10.71% year over year but slipped 4.14% month over month, whereas Pre-Roll surged 203.90% year over year and added 5.67% month over month, and Concentrates ticked up 4.27% month over month despite a negligible base. With brand-wide average price down 18.75% year over year to $50.04, the mix shift toward lower-priced Pre-Roll alongside a modest Flower pullback implies volume-led expansion that reduces revenue reliance on a single category.
Holding rank 1 in Flower in British Columbia while Flower’s month-over-month decline of 4.14% contrasts with Pre-Roll’s 5.67% month-over-month gain positions Big Bag O' Buds to defend its Flower leadership while using Pre-Roll momentum to buffer short-term category softness. The 203.90% year-over-year Pre-Roll growth against a 10.71% year-over-year Flower rise, coupled with a 19.71% share now in Pre-Roll versus 79.75% in Flower, implies a deliberate push into value-access points that can expand household penetration and sustain the 27.34% brand sales year-over-year growth even if Flower normalizes.
Competitive Landscape
Big Bag O' Buds is currently ranked #4 in ON Flower in September 2026, unchanged from #4 year over year, after slipping from #3 in June 2026 while previously peaking at #1 in August 2025; meanwhile, Spinach moved from #3 to #1 with a 15.7% sales increase and Back Forty / Back 40 Cannabis fell from #1 to #3 with a 7.4% sales decline, indicating that sideways rank at #4 alongside upward and downward moves around it points to share being defended rather than expanded.

Notable Products
Frosted Rootbeer (28g) posted the steepest decline in September 2026 at -12.9% and slipped to rank 9, while Purple Cherry Punch (28g) also contracted -9.6% yet held a higher rank at 3. Purple Cherry Punch (3.5g) dipped -9.0% but still led the lineup at rank 1, contrasting with Blueberry Dream Pre-Roll 10-Pack (5g) which climbed +15.0% to rank 4. With four of the top ten in Flower and four in Pre-Roll, the tilt toward Pre-Roll growth alongside erosion in large-format Flower implies a demand shift from bulk value buys toward convenient multipacks, pressuring ounce formats while supporting multi-pack line extensions.
Purple Cherry Punch Pre-Roll 10-Pack (5g) rose +17.0% to rank 2 against Ultra Sour Pre-Roll 20-Pack (8g) at -5.5% and rank 8, and Blueberry Dream Pre-Roll 20-Pack (8g) gained +3.5% at rank 7 while Frosted Rootbeer Pre-Roll 10-Pack (7.5g) added +8.7% at rank 5. Across the assortment, only one large Flower pack declined by more than -10% while two Pre-Roll SKUs posted double-digit gains, and the category split concentrates momentum in Pre-Rolls. The pattern implies Big Bag O' Buds can capture near-term volume by prioritizing Pre-Roll multipacks and defending premium ounces selectively rather than scaling all large-format Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

