
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
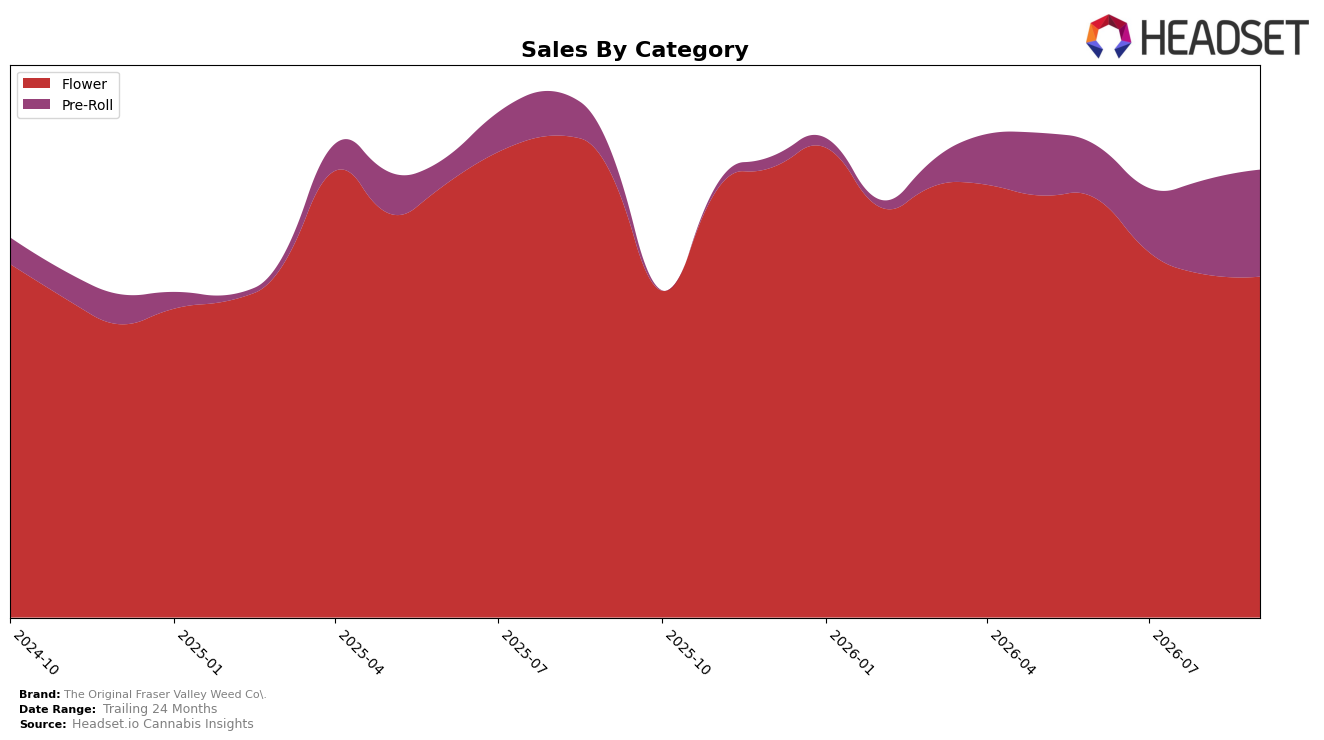
In September 2026, The Original Fraser Valley Weed Co. concentrated 69.26% of sales in Flower and 30.74% in Pre-Roll, with Flower down 20.49% year over year and 0.52% month over month while Pre-Roll rose 80.37% year over year and 7.20% month over month. Despite brand-level sales down 3.99% year over year, the average price fell 28.81%, indicating volume lift concentrated in lower-priced formats even as Flower’s average price at $86.10 contrasts with Pre-Roll at 25.86. This mix pattern implies the brand is reallocating demand from a contracting Flower base toward faster-growing Pre-Roll to defend overall share and smooth volatility.
The category shift aligns with a rank of 4 in Flower within British Columbia, suggesting reliance on a high-visibility but softening core while momentum builds in a value-accessible Pre-Roll line. With ON as the top market and Pre-Roll gaining 7.20% month over month versus Flower’s 0.52% decline, the brand is trading some premium-weighted Flower exposure for higher-frequency Pre-Roll occasions, positioning for steadier throughput if the Flower downturn persists. The pattern implies that protecting position in Flower while accelerating Pre-Roll penetration is the near-term route to offset price compression and stabilize rank-sensitive performance.
Competitive Landscape
The Original Fraser Valley Weed Co. sits at rank #7 in ON Flower for September 2026, slipping 1 spot YoY from #6 while retreating 2 positions from its peak at #5 in August 2026, indicating share pressure despite a near-peak summer placement; in contrast, Spinach climbed from #3 to #1 with 15.7% YoY sales growth and Back Forty / Back 40 Cannabis fell from #1 to #3 alongside a -7.4% YoY sales decline, while FIGR surged from #14 to #5 with 51.7% YoY growth; this pattern implies The Original Fraser Valley Weed Co.’s rank trajectory is drifting from the lead pack and risks further share loss if it does not counter faster-moving climbers.

Notable Products
Kush Breath (28g) posted the steepest decline at -26.6% and slid to rank 6, while Strawberry Amnesia Pre-Roll 14-Pack (7g) fell -11.1% at rank 8, indicating pressure on specific SKUs despite Big Red - Hybrid Pre-Roll 20-Pack (10g) holding rank 1 with +12.3% growth. Pre-Rolls occupy six of the top ten ranks and include two top-five positions at ranks 1 and 2, whereas Flower holds ranks 3, 4, 6, 7, and 10 with mixed MoM shifts from +6.2% to -26.6%; this split suggests the brand is leaning into multi-pack Pre-Rolls for volume while culling underperforming Flower formats.
Little Red Indica Pre-Roll 4-Pack (2g) dipped -9.5% at rank 2 and contrasts with Little Red Sativa Pre-Roll 4-Pack (2g) up +23.1% at rank 5, pointing to intra-family rotation favoring sativa in September 2026. Against that backdrop, Big Red - Hybrid Pre-Roll 20-Pack (10g) added an estimated $1.27M with +12.3% at rank 1 and Big Red Sativa Pre-Roll 20-Pack (10g) climbed +11.5% at rank 9, reinforcing that value-oriented 20-packs are anchoring share even as select single-strain Flowers soften; the product mix implies The Original Fraser Valley Weed Co. is consolidating around high-count Pre-Rolls while selectively deprioritizing weaker Flower SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

