

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
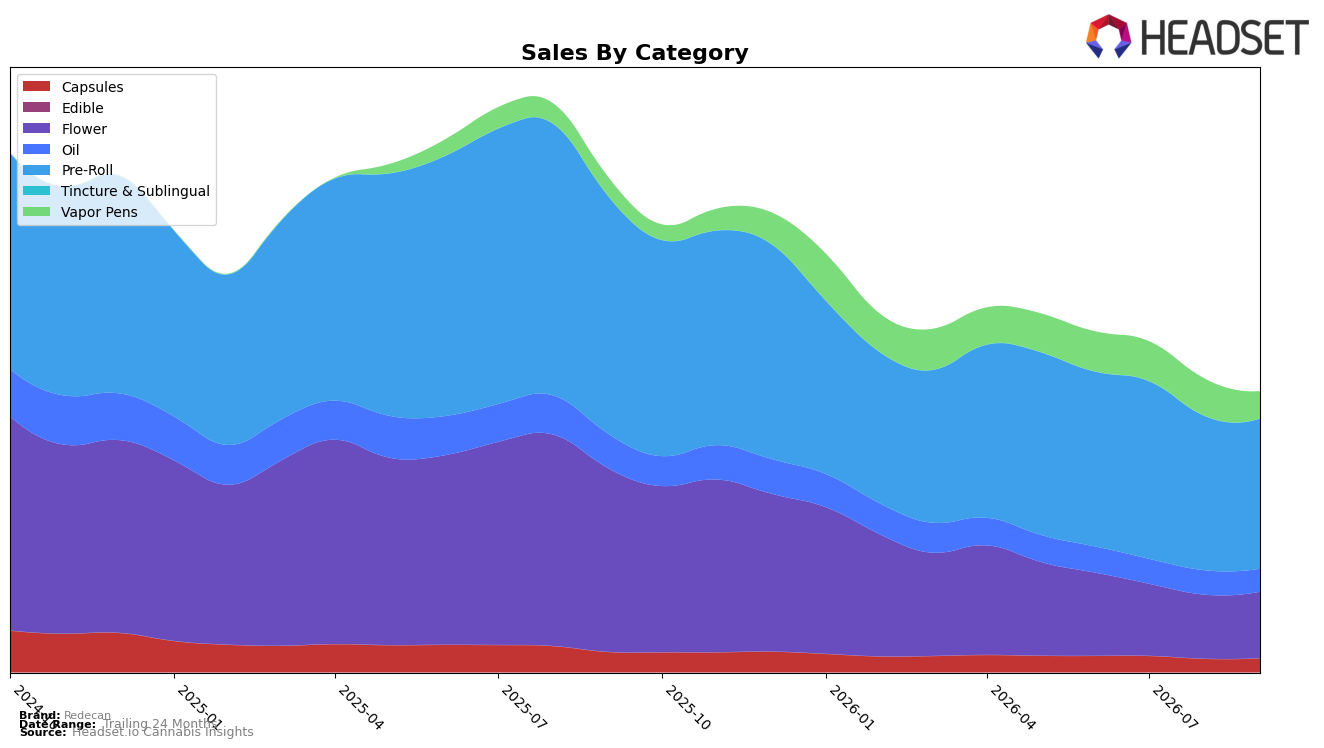
Redecan’s mix in September 2026 is anchored by Pre-Roll at 53.61% share with year-over-year decline of 36.80% and month-over-month slippage of 2.63%, while Flower holds 23.64% share with a 63.95% year-over-year drop but a 3.68% month-over-month uptick. Vapor Pens accounts for 9.66% share with a 43.85% year-over-year increase but a 27.07% month-over-month pullback, and Oil at 8.13% share is down 33.66% year-over-year and 5.83% month-over-month. Capsules contributes 4.97% share with a 31.17% year-over-year decline and a 4.26% month-over-month rise; combined with an average price dip of 0.74% year-over-year and an overall brand sales decline of 43.37% year-over-year, the pattern implies Redecan is dependent on a contracting Pre-Roll base while tactical volume is shifting toward selective recovery in Flower and Capsules.
The shifts imply portfolio repositioning pressure: a heavier 53.61% Pre-Roll reliance alongside a 36.80% year-over-year contraction concentrates risk, while the 43.85% year-over-year gain in Vapor Pens combined with a 27.07% month-over-month retreat signals volatility rather than stable expansion. With Flower down 63.95% year-over-year yet up 3.68% month-over-month, and Capsules down 31.17% year-over-year but up 4.26% month-over-month, Redecan’s near-term positioning leans toward defending core share in Pre-Roll while probing recovery in value-sensitive formats, supported by a 0.74% year-over-year price decrease, which implies the brand is trading price for retention without offsetting enough mix decline to reverse the 43.37% year-over-year sales drop or improve its rank position to 10 in Pre-Roll in Saskatchewan.
Competitive Landscape
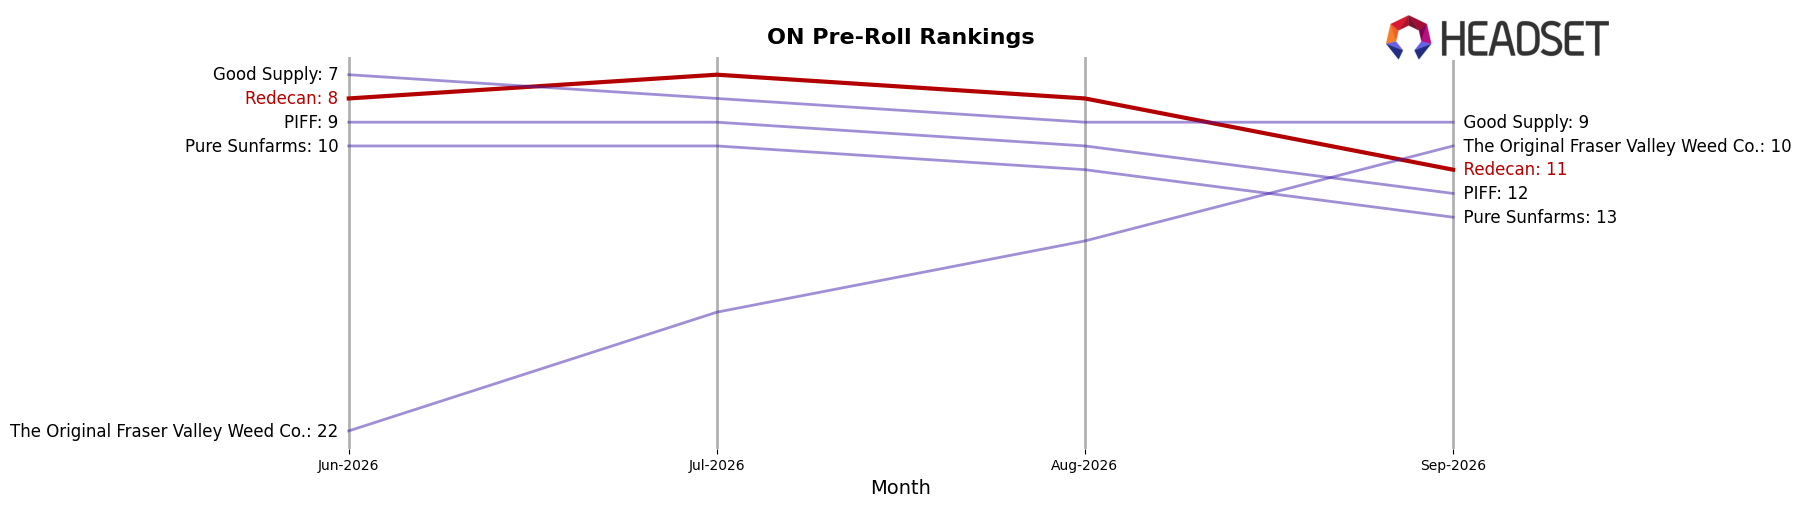
Redecan ranks #11 in ON Pre-Roll in September 2026, down 6 positions from #5 in September 2025, and 3 positions from #8 in June 2026; this sits well below its peak of #4 in November 2025 but outside the top 10 now. In contrast, Back Forty / Back 40 Cannabis holds #1 after improving from #2 year over year with sales up 46.6%, while General Admission slipped from #1 to #2 as sales fell 38.2%; additionally, Spinach climbed from #17 to #4 with 141.2% sales growth. The directional gap—Redecan moving from #5 to #11 as multiple rivals advance in rank—implies a share redistribution where Redecan’s trajectory risks further erosion unless it counters momentum shifts concentrated among faster-rising peers.
Notable Products
September 2026 brought no outsized surges or collapses, so the headline is the quiet reshuffle: Redees - Purple Churro Pre-Roll 10-Pack (4g) slid 6.4% MoM to rank 4 while Redees - Wappa Pre-Roll 10-Pack (4g) rose 5.8% MoM to rank 3, a swap that concentrates share in higher-velocity pre-roll SKUs. With Redees - Cold Creek Kush Pre-Roll 10-Pack (4g) up 10.0% MoM at rank 1 and the 20-Pack holding rank 7 on a -0.6% MoM dip, five of the top ten are Pre-Roll formats, indicating Redecan’s assortment is leaning further into multi-pack convenience at the top of the chart.
Outside pre-rolls, THC 30 Reign Drops Oil (30ml) fell 6.7% MoM at rank 5 while Animal Rntz (3.5g) gained 11.2% MoM at rank 6, signaling a modest tilt from ingestible oil to inhalable flower. Animal RNTZ (1g) declined 7.2% MoM at rank 9 even as Purple Churro (3.5g) grew 3.1% MoM at rank 10, which suggests flower strength is SKU-specific rather than category-wide.
The mix implies Redecan is prioritizing pre-roll multi-packs to anchor volume while selectively nurturing a few flower strains to backfill softness in oil, a stance that concentrates growth in repeatable, convenience-led formats rather than spreading bets across slower-moving forms.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

