

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Boujee is stocked at 103 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Adrian, Benton Harbor, Detroit, and Flint. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
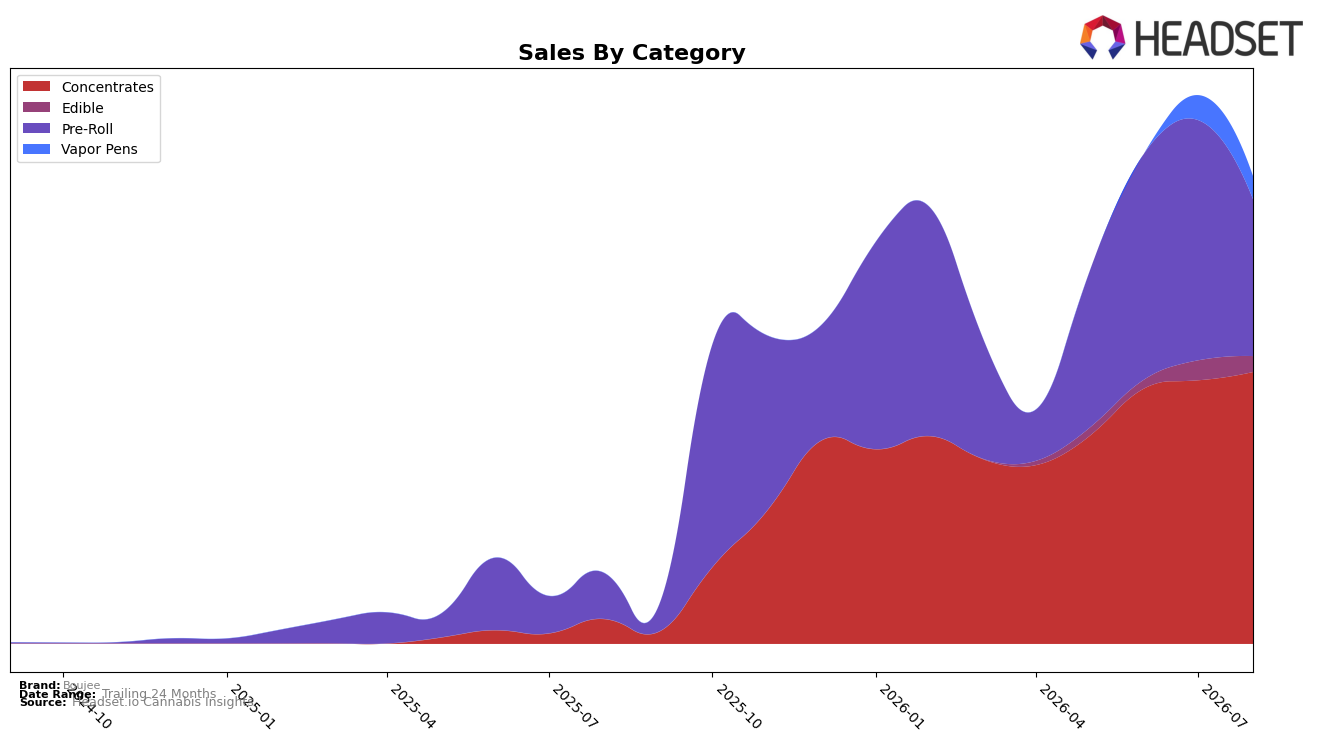
In August 2026, Boujee’s mix tilted toward Concentrates at 58.21% share with a 1,007.93% year-over-year increase and a 3.14% month-over-month gain, while Pre-Roll held 33.54% share with 241.78% year-over-year growth but a 34.79% month-over-month decline. Vapor Pens and Edible contributed 4.90% and 3.36% share, respectively, with month-over-month drops of 7.48% and 20.40%; average prices diverged, with Concentrates at $32.39 and Pre-Roll at $12.21 alongside a brand-level average price up 31.54% year over year. This mix shift implies Boujee is consolidating revenue density in higher-priced Concentrates while cycling down in Pre-Roll volume month over month, setting a trajectory where Concentrates become the anchor category as Pre-Roll volatility dampens.
With Concentrates ranked 17 in Michigan and holding a 58.21% share of Boujee sales, the 3.14% month-over-month uptick contrasts with a 34.79% month-over-month pullback in Pre-Roll, indicating execution and distribution are aligning more effectively to Concentrates’ price-to-demand elasticity than to Pre-Roll. Given brand sales up 563.74% year over year and month-over-month declines in Vapor Pens and Edible of 7.48% and 20.40%, respectively, the positioning leans toward deepening a single-category beachhead rather than broad multi-category expansion, implying resource allocation should favor Concentrates assortment and retail placement while treating Pre-Roll as a tactical, promotion-sensitive lever rather than a stable growth engine.
Competitive Landscape
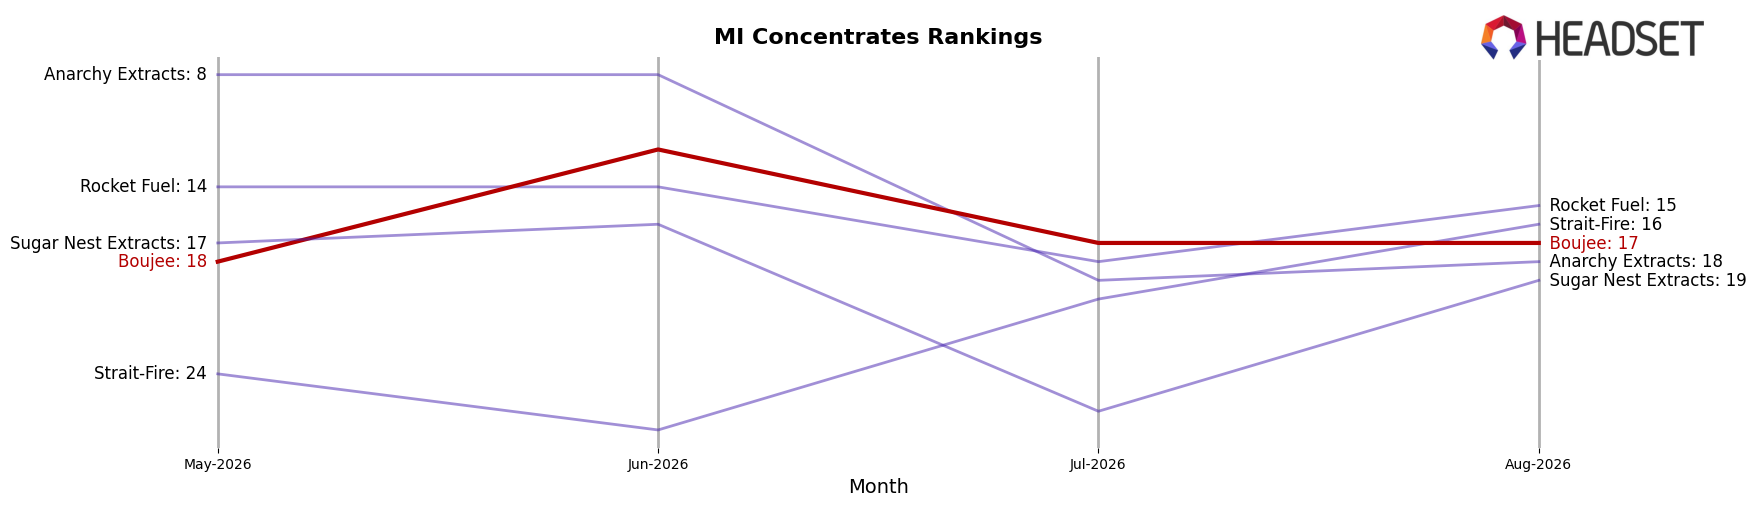
Boujee sits at rank #17 in MI Concentrates in August 2026, improving 102 positions year over year from #119, while slipping 1 rank from May–June’s #18 to #17 across the last three months and peaking at #12 in June 2026; this step-up in placement coincides with a market where The Limit held #1 despite a -3.36% YoY sales change and Uniq Pressure surged from #126 to #3 alongside a 3,686.24% YoY sales increase, indicating Boujee’s advance is competitive but comparatively slower than the fastest risers and more stable than peers with negative growth. The mix of a 102-rank YoY climb and a recent slip from a #12 peak to #17 implies Boujee’s trajectory is upward but entering a consolidation phase where share gains require defending against rapid climbers as the category reorders around high-growth entrants.
Notable Products
Terpaja Blast Infused Pre-Roll (1.5g) posted the steepest move in August 2026 with a -75.6% month-over-month decline, dropping to rank 10 while Ecto Cooler Infused Pre-Roll (1.5g) fell -51.2% at rank 2. In contrast, Unicorn Piss Infused Pre-Roll (1.5g) jumped +64.2% to rank 3, while Cereal Milk Infused Pre-Roll (1.5g) eased -7.6% but held rank 1. Six of the top ten are Pre-Roll SKUs, yet the highest single-month revenue sits in Concentrates with Hella Jelly Live Hash Rosin (5g) at rank 6 and +14.9% MoM, indicating a mixed reliance on volume-leading Pre-Rolls and value-dense extracts. The pattern implies Boujee is pivoting toward a barbell mix where volatile Pre-Roll innovations drive trial while Concentrates anchor dollars and margins.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

