

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
BoxHot is stocked at 40 licensed dispensaries across California, with the deepest coverage in Los Angeles, Vallejo, Lake Elsinore, San Jacinto, and Adelanto. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
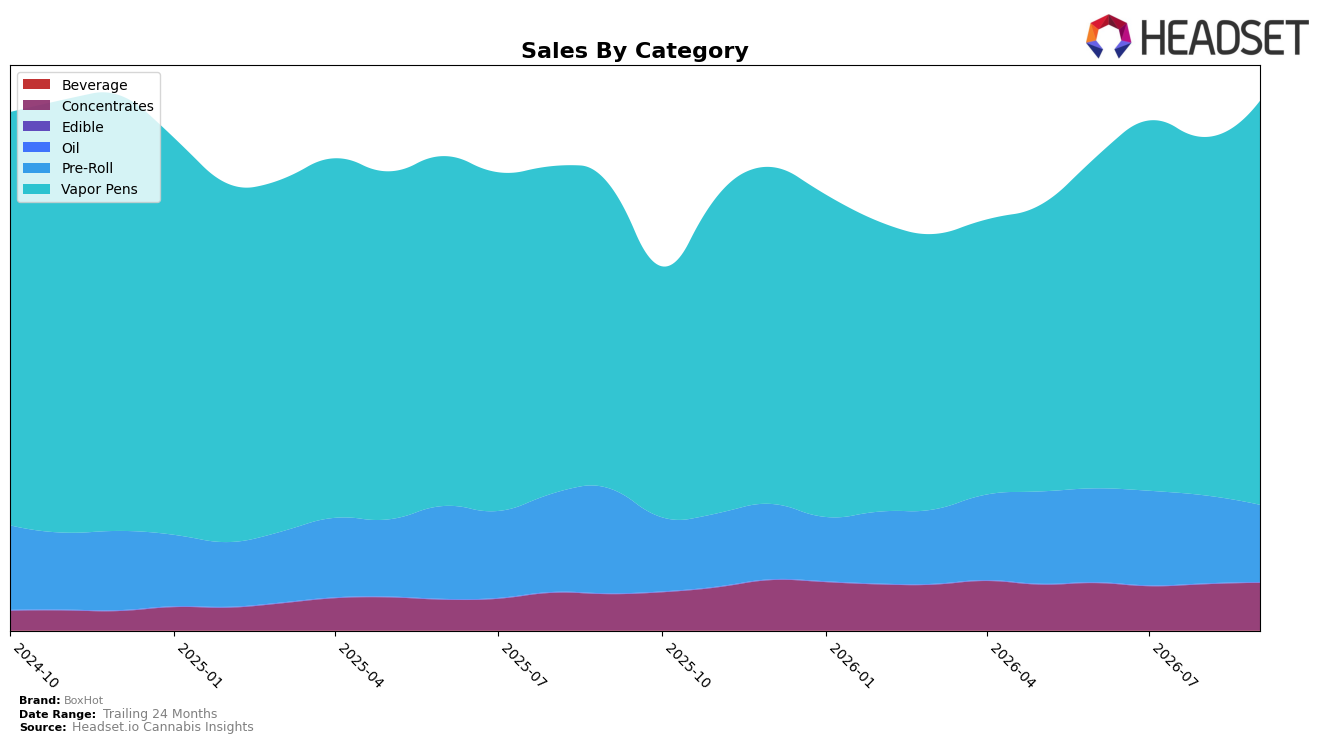
In September 2026, Vapor Pens accounted for 76.48% share with year-over-year growth of 32.61% and month-over-month growth of 12.76%, while Pre-Roll fell to 14.54% share with a -26.77% YoY decline and -12.43% MoM contraction; Concentrates held 8.97% share with 31.38% YoY growth and 3.17% MoM growth. The average price rose 3.04% YoY to $33.61, alongside a Vapor Pens average price of $35.53, implying demand held despite modest price pressure. With Vapor Pens expanding share and rank position at 1 in Vapor Pens in Alberta, the mix shift indicates BoxHot is consolidating around its lead category while pulling back exposure to the underperforming Pre-Roll segment.
The pattern implies BoxHot’s positioning is tilting further toward a premium-leaning inhalables focus: a 12.76% MoM gain in Vapor Pens paired with a -12.43% MoM retreat in Pre-Roll concentrates revenue into higher-velocity formats, and a 31.38% YoY rise in Concentrates provides a secondary growth pillar. Holding 76.48% mix in Vapor Pens while prices are up 3.04% YoY suggests pricing headroom in the core, and the -26.77% YoY in Pre-Roll indicates selective deprioritization; together, these shifts point to prioritizing margin and category leadership over breadth.
Competitive Landscape
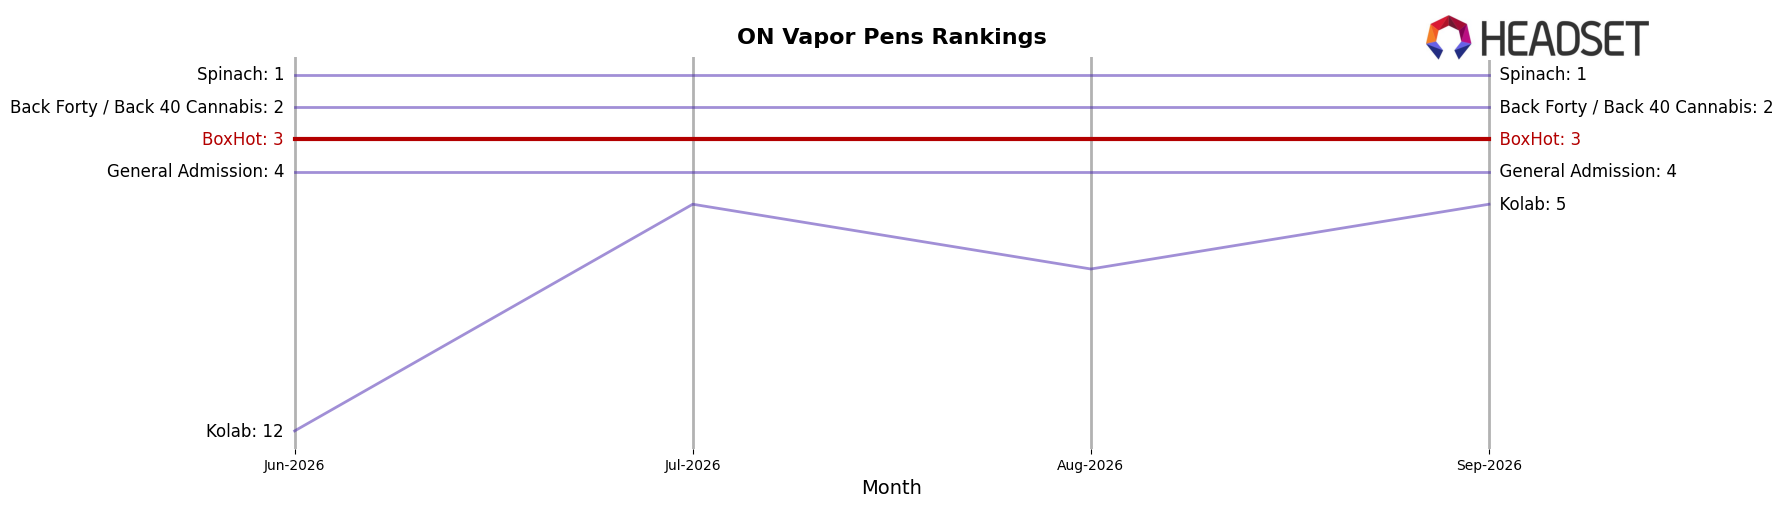
BoxHot sits at rank #3 in ON Vapor Pens in September 2026, down 1 place year over year from #2, and flat versus June 2026 where it also held #3; meanwhile, the brand’s historical peak was #1 in June 2025, marking a 2-position slide from that high. Competitive movement tightened the gap: Spinach climbed from #4 to #1 with a 172.5% year-over-year sales lift, while Back Forty / Back 40 Cannabis eased from #1 to #2 despite a 3.0% YoY increase; by contrast, General Admission slipped from #3 to #4 on an 12.0% YoY decline. The pattern implies BoxHot’s rank trajectory has shifted from peak leadership toward a stable #3 position as faster YoY movers displace share at the top.
Notable Products
Berry Baddie Liquid Diamond Charged Cartridge (1g) set the tone in September 2026 with a -10.4% month-over-month decline while holding rank 2, contrasting with Maui Madness Liquid Diamond Charged Cartridge (1g) up 13.5% at rank 1. Pink Kush Liquid Diamond Charged Disposable (1g) climbed 37.1% at rank 4, while Highlighters - Blue Razz Lemonade Liquid Diamond Charged Disposable (1g) rose 10.1% at rank 3, indicating the gains are concentrated in disposables even as a flagship cartridge retrenches; nine of the top ten are Vapor Pens. The balance of a -10.1% Pre-Roll at rank 9 against an 8.99% Concentrates move at rank 10, alongside a single raw sales outlier at $595,185 for Maui Madness, implies BoxHot is tilting assortment and demand toward higher-velocity pens and select disposables while deprioritizing slower Pre-Roll formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

