

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
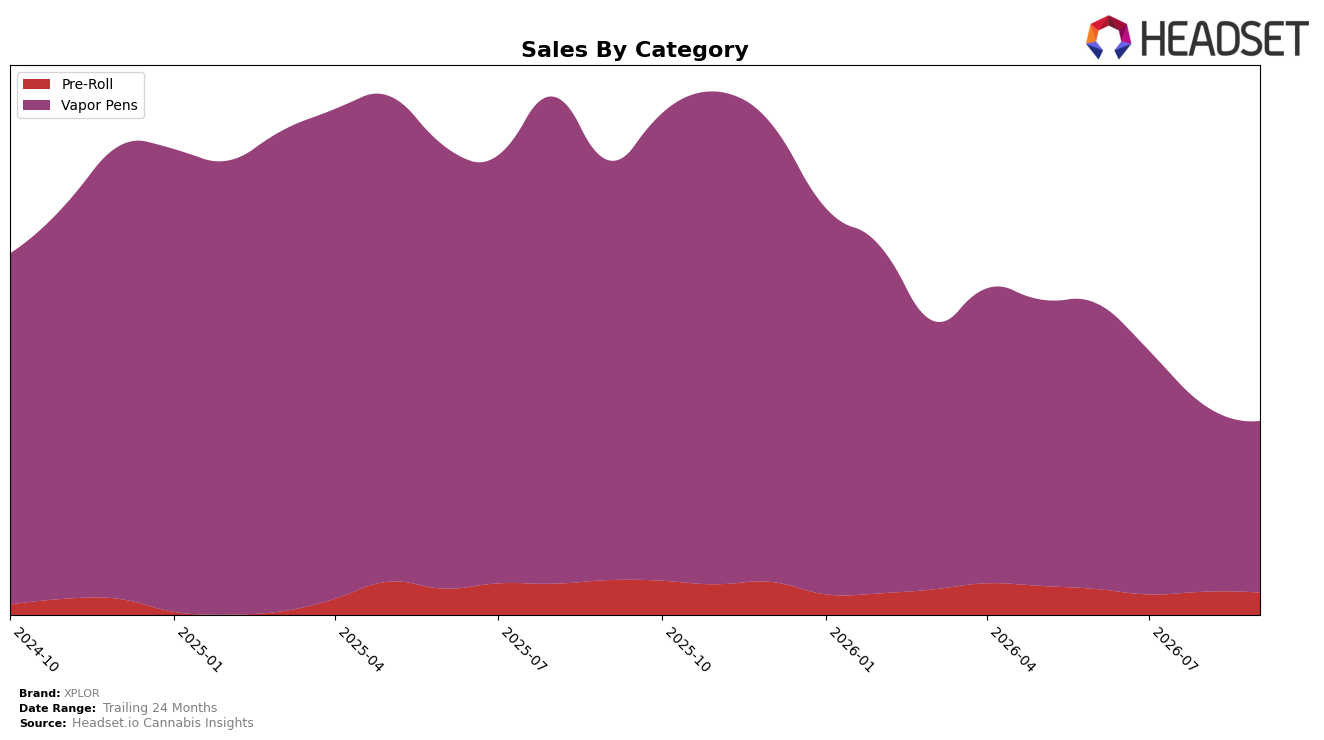
XPLOR’s mix in September 2026 concentrated 78.27% in Vapor Pens (rank 11 in Vapor Pens within Alberta), with Pre-Roll holding 21.73%; Vapor Pens declined 54.60% year over year and 6.64% month over month, while Pre-Roll fell 17.85% year over year and 1.46% month over month. Against a brand-level sales change of -49.71% year over year and an average price decline of 11.62%, the heavier exposure to the faster-contracting Vapor Pens category versus the milder Pre-Roll contraction created a category-mix drag, implying that concentration risk rather than broad-based weakness is the primary driver.
The sharper pullback in Vapor Pens relative to Pre-Roll suggests XPLOR’s positioning is tethered to a segment with steeper demand or pricing pressure, while the smaller 21.73% Pre-Roll share limited cushioning despite its comparatively smaller 17.85% year-over-year decline and 1.46% month-over-month dip. With an average brand price down 11.62% alongside a 6.64% month-over-month slide in Vapor Pens, the data implies XPLOR is leaning defensively on pricing within its core segment but lacks enough Pre-Roll scale to offset volatility, signaling a need to rebalance toward categories with shallower declines to stabilize rank beyond position 11.
Competitive Landscape
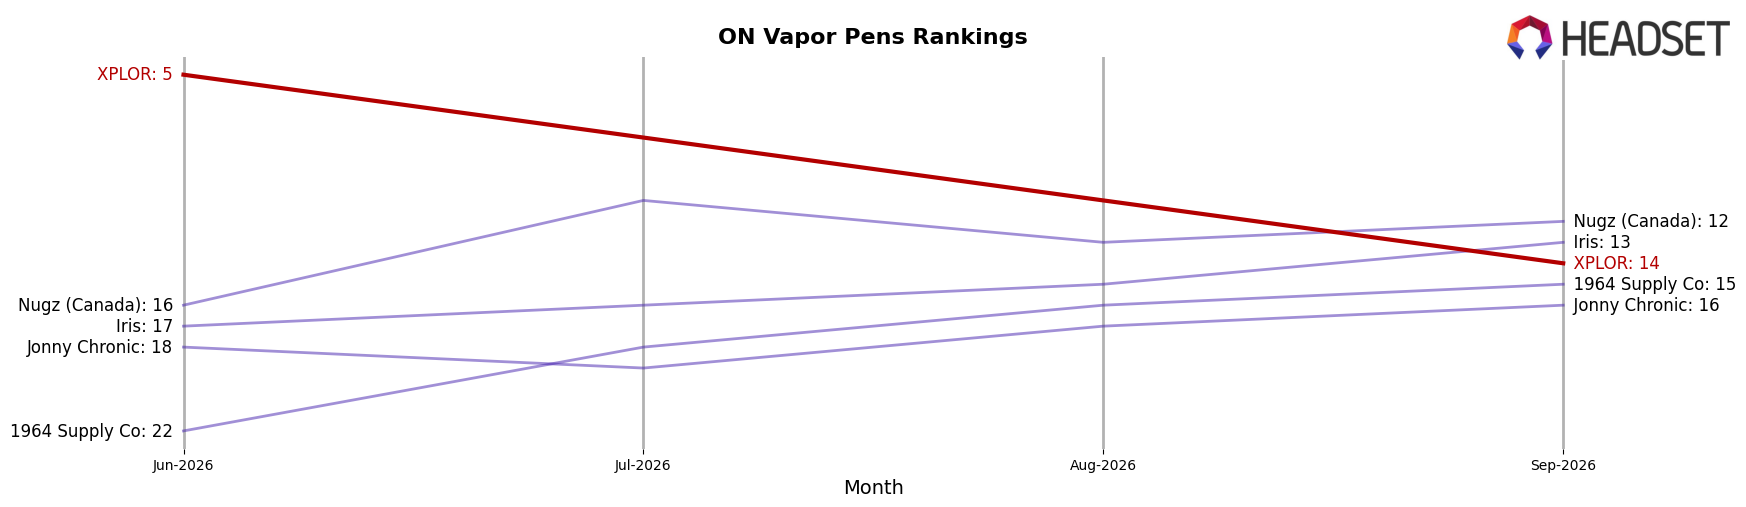
XPLOR sits at rank #14 in ON Vapor Pens in September 2026, down 9 positions year over year from #5, and down 9 positions versus June 2026 when it was also #5; this follows a trajectory from a peak at #3 in February 2025 to #14 today, a 11-place slide from peak to current. Meanwhile, Spinach climbed from #4 to #1 with 172.5% YoY sales growth, and Kolab jumped from #14 to #5 with 93.0% YoY growth, whereas General Admission moved from #3 to #4 while contracting by 12.0% YoY; against this backdrop, XPLOR’s fall from #5 to #14 implies share is being ceded to faster-rising rivals concentrating gains at the top of the table.
Notable Products
Unicorn Blood Infused Pre-Roll (1g) posted the steepest shift in September 2026 with a -10.1% month-over-month change while holding rank 2, contrasting with Nana's Jam CO2 Cartridge (1g) at rank 1 on a +134.6% surge and Red Hawaiian Co2 Cartridge (1g) at rank 4 on +11.7%. Four of the top ten are Vapor Pens, concentrated across ranks 1, 4, 5, and 8, and two of the top three positions are Pre-Rolls with mixed momentum at +4.3% and -10.1%. This mix implies XPLOR is tilting toward Vapor Pens for growth while using a narrower set of Pre-Rolls to defend top-tier visibility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

