

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
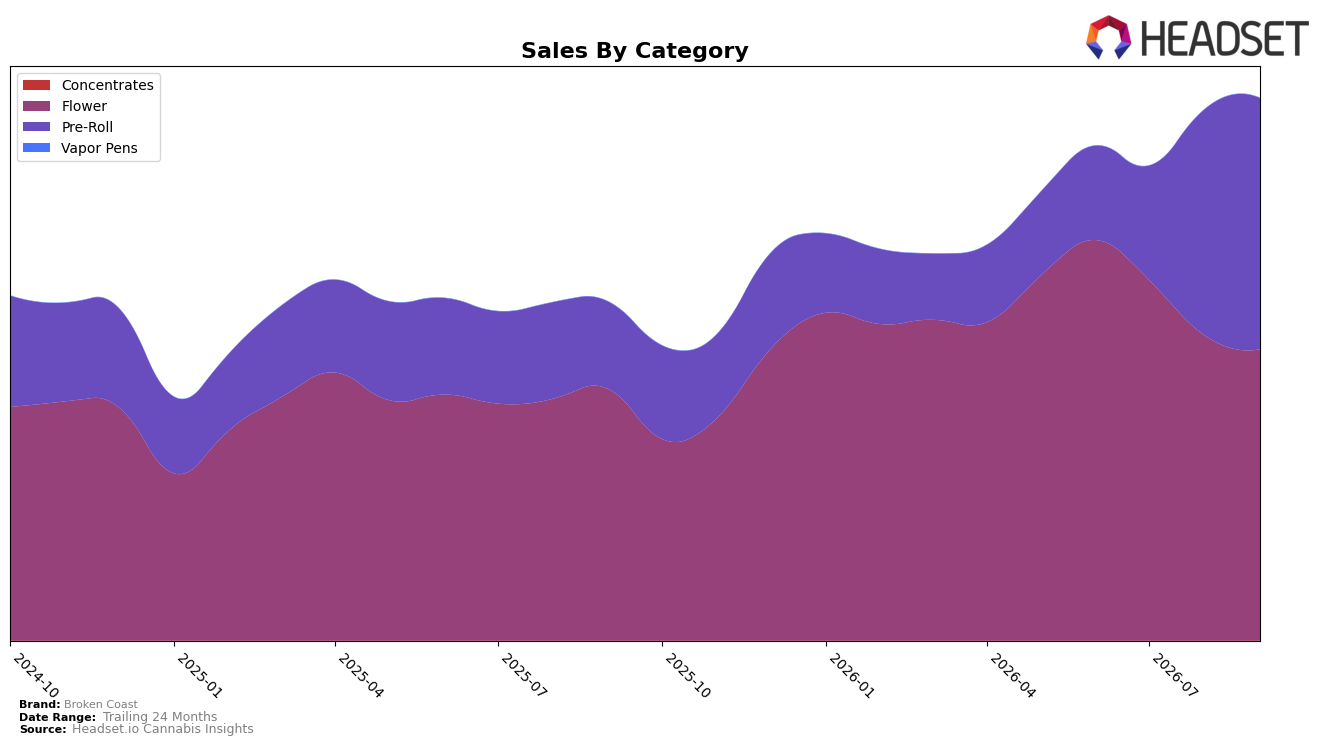
Broken Coast’s mix in September 2026 was concentrated in Flower at 53.70% share (ranked 13 in Flower within Alberta) alongside Pre-Roll at 46.30% share, with year-over-year growth diverging sharply: Flower up 15.83% YoY while Pre-Roll jumped 188.01% YoY. Month-over-month, Flower declined 4.55% as Pre-Roll grew 11.10%, indicating a near parity of category shares despite Flower’s historical lead. With brand-level sales up 60.16% YoY and average price down 2.71% YoY, the combination of a Pre-Roll surge and slight price deflation implies Broken Coast is trading volume for share in faster-turning formats rather than relying on premium pricing to sustain September 2026 growth.
The tilt toward a 46.30% Pre-Roll share alongside a 4.55% Flower MoM decline and 11.10% Pre-Roll MoM gain suggests Broken Coast is repositioning toward convenience-driven occasions, using lower average price points relative to Flower (17.10 vs one higher-priced Flower average) to accelerate throughput. The 15.83% Flower YoY increase paired with a 188.01% Pre-Roll YoY surge implies the brand’s growth engine is now format-led rather than strain-led, and the 13 rank in Alberta Flower indicates headroom if the brand can convert Pre-Roll trial back into Flower replenishment. The pattern points to a two-track positioning: protect Flower equity while using expanding Pre-Roll penetration to seed repeat purchasing, with September 2026 mix signaling that marginal gains will come more from distribution breadth and pack-size strategy than from further price elevation.
Competitive Landscape
Broken Coast ranks #29 in ON Flower in September 2026, improving 2 positions from #31 year over year but slipping 2 spots from #27 in June 2026, which was also its peak rank. The competitive set is consolidating at the top: Spinach moved from #3 to #1 while growing sales 15.7% year over year, and FIGR jumped from #14 to #5 with 51.7% sales growth, whereas Back Forty / Back 40 Cannabis fell from #1 to #3 alongside a 7.4% sales decline. With a three-month rank softening from #27 to #29 as top-tier rivals either advance upward or reshuffle, the rank trajectory implies Broken Coast is stabilizing mid-tier but risks further share erosion unless it counters rivals’ upward mobility.

Notable Products
Blue Dream Blunt (1g) posted the steepest decline in September 2026 at -10.0% MoM while holding rank 1, and Coffee Creamer (3.5g) fell -11.8% MoM at rank 9, signaling pressure on both the lead single and a key Flower format. In contrast, Blue Dream Pre-Roll 10-Pack (5g) rose 13.5% MoM at rank 4 and Coffee Creamer Blunt (1g) gained 11.3% MoM at rank 2, while Platinum Pave Blunt (1g) climbed 30.6% MoM at rank 8, indicating momentum concentrated in multi-pack and infused-style pre-rolls. Eight of the top ten are Pre-Roll SKUs, and Cherry Ztripez shows mixed signals with -8.0% MoM at rank 3 for the Blunt versus +8.8% MoM at rank 5 for the 10-Pack, implying consumers are trading into value-density formats even as single sticks soften. The product mix points to Broken Coast tilting toward pre-roll depth and larger-count packs as the commercial focus, with Flower de-prioritized despite Blue Dream (7g) still contributing $351,715.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

