

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
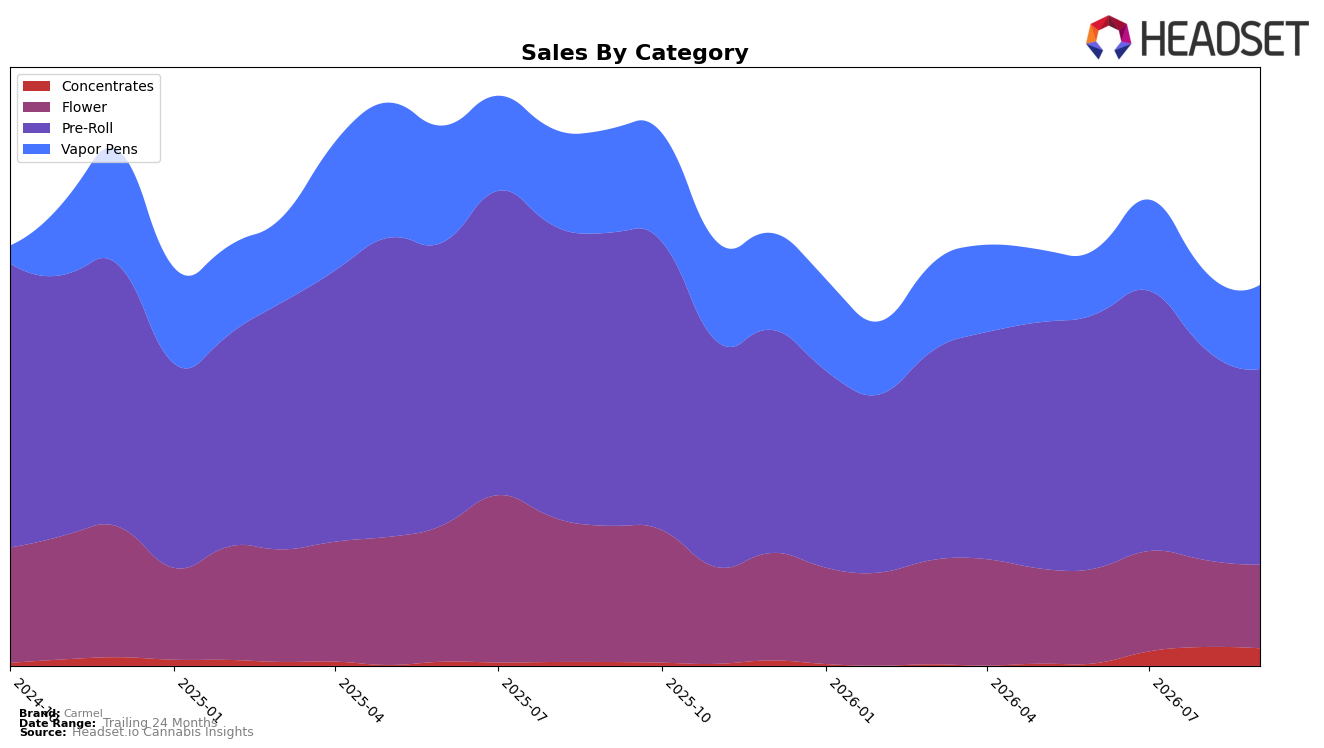
Carmel’s category mix in September 2026 concentrated nearly half of sales in Pre-Roll at 48.7% share, where sales fell 32.1% year over year and 7.1% month over month, while Vapor Pens held 22.4% share with a 17.0% YoY decline but a 7.4% MoM increase. Flower maintained 22.3% share with steeper contractions of 35.8% YoY and 3.5% MoM, and Concentrates, though only 6.7% share, surged 94.3% YoY despite a 4.4% MoM dip; together these shifts occurred alongside a brand-level sales decline of 26.9% YoY and an average price down 3.4% YoY, implying a pivot away from higher-volume legacy segments into a more mixed portfolio where growth pockets are not yet offsetting Pre-Roll and Flower drag.
Positioning-wise, holding the top category as Pre-Roll while ranking 16th in Ontario Pre-Roll indicates mid-pack placement that is pressured by a 32.1% YoY decline in that anchor segment and only a 7.1% MoM contraction, whereas Vapor Pens’ 7.4% MoM gain alongside a 17.0% YoY drop signals momentum that could re-balance mix if sustained. With Concentrates up 94.3% YoY but just 6.7% share and Flower down 35.8% YoY at 22.3% share, the brand is weighted toward categories with larger declines than gains, implying near-term focus on Vapor Pens and Concentrates to lift rank from 16 and counter the 26.9% YoY brand decline as average prices sit 3.4% lower YoY.
Competitive Landscape
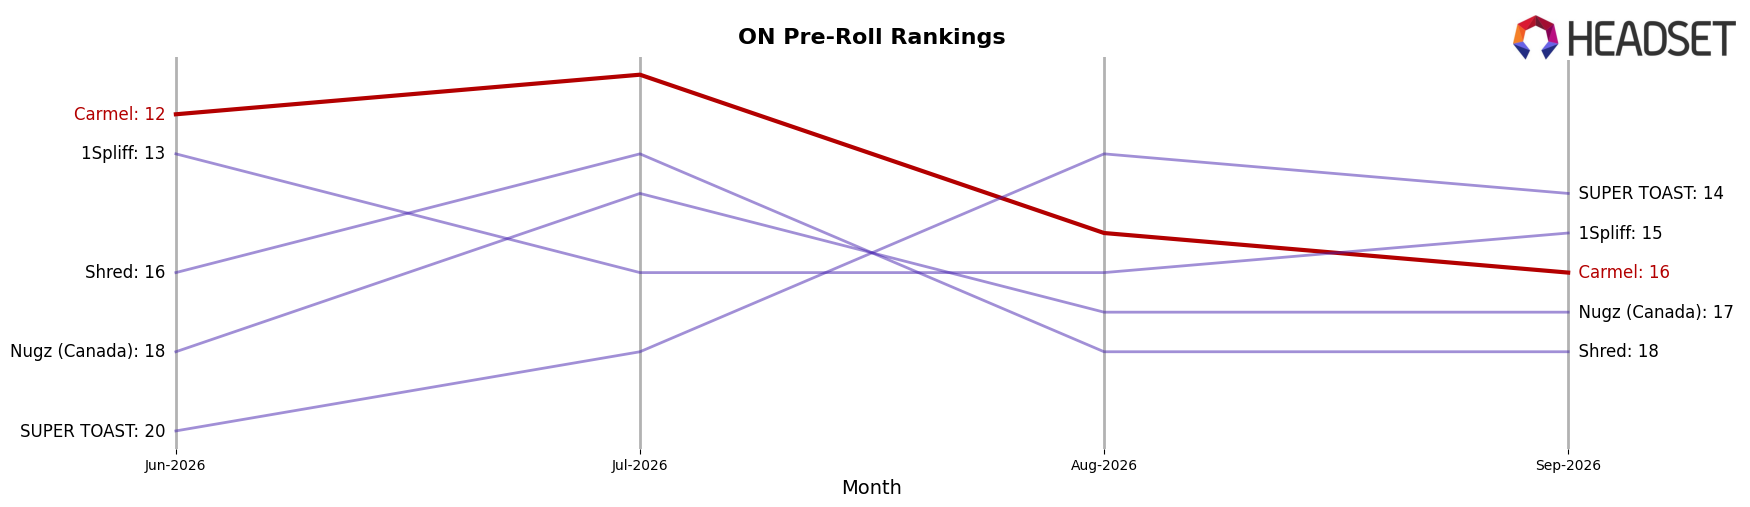
Carmel sits at rank #16 in ON Pre-Roll for September 2026, down 5 positions year over year from #11, and 4 spots below its June 2026 mark of #12; against its peak of #6 in September 2024, the brand is 10 ranks lower. Meanwhile, Back Forty / Back 40 Cannabis holds #1 after a 1-position YoY rise with 46.6% sales growth, while General Admission slipped from #1 to #2 with a 38.2% sales decline, and Spinach surged from #17 to #4 on 141.2% growth; relative to these moves, Carmel’s fall from #12 to #16 over the last three months and from #11 YoY indicates share is being redistributed toward faster risers, implying the brand must pivot assortment or pricing to arrest a downward rank trajectory.
Notable Products
Animal Face Pure Live Resin Cartridge (1g) posted the steepest downturn in September 2026 with a -158% month-over-month swing and slid to rank 2, while Animal Face Pre-Roll 3-Pack (1.5g) fell -86% MoM at rank 1. Against those declines, Animal Face Ceramic Tip Infused Pre-Roll (1g) jumped +86% MoM and moved to rank 6, and Bubble Pop Cake Pre-Roll 3-Pack (1.5g) rose +59% MoM at rank 4. With six of the top ten coming from the Pre-Roll category and only one Flower SKU cracking rank 10, the mix points to Carmel leaning into pre-roll velocity while vapor pens retrench despite Jungle J Pure Live Resin Cartridge (1g) gaining +39% MoM at rank 9; this tilt implies near-term attention on maintaining pre-roll depth as cartridge volatility resets price and inventory strategy, with rank 1 still concentrated in one Animal Face format generating $525,585.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

