

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
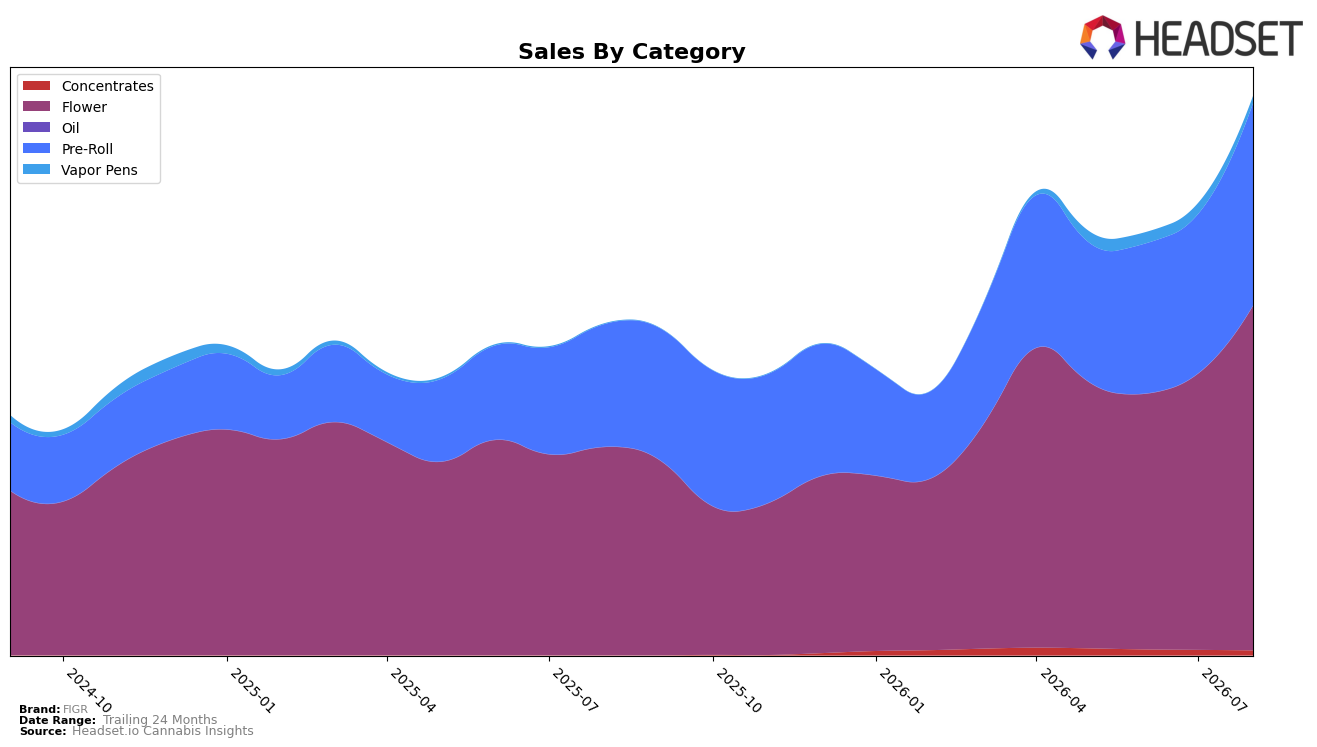
In August 2026, FIGR’s mix concentrated in Flower at 61.69% share with year-over-year growth of 65.98% and month-over-month growth of 24.98%, while Pre-Roll held 36.20% share with 65.53% YoY and 27.21% MoM. Vapor Pens remained a niche at 1.23% share despite a 1,179.74% YoY surge, but its MoM contraction of 35.59% offsets that spike; Concentrates were 0.87% share with a 9.99% MoM decline and no YoY comparator. With an average price up 6.14% YoY to $32.33 alongside category-level MoM gains concentrated in Flower and Pre-Roll, the pattern implies FIGR is doubling down on inhalables where near-term velocity is rising, rather than diversifying into smaller segments.
FIGR’s Flower rank at 1 in Alberta combined with a 24.98% MoM in Flower and 27.21% MoM in Pre-Roll suggests a positioning anchored in top-shelf throughput over breadth, even as Vapor Pens’ 35.59% MoM drop warns against overextending into low-base growth. The 61.69% Flower share versus 36.20% in Pre-Roll indicates a deliberate tilt toward higher-share SKUs where price can carry modest expansion, as evidenced by the 6.14% YoY average price increase and 65.98% YoY growth in Flower; the implication is that FIGR’s competitive footing hinges on defending premium Flower leadership while using Pre-Roll as the secondary volume engine.
Competitive Landscape
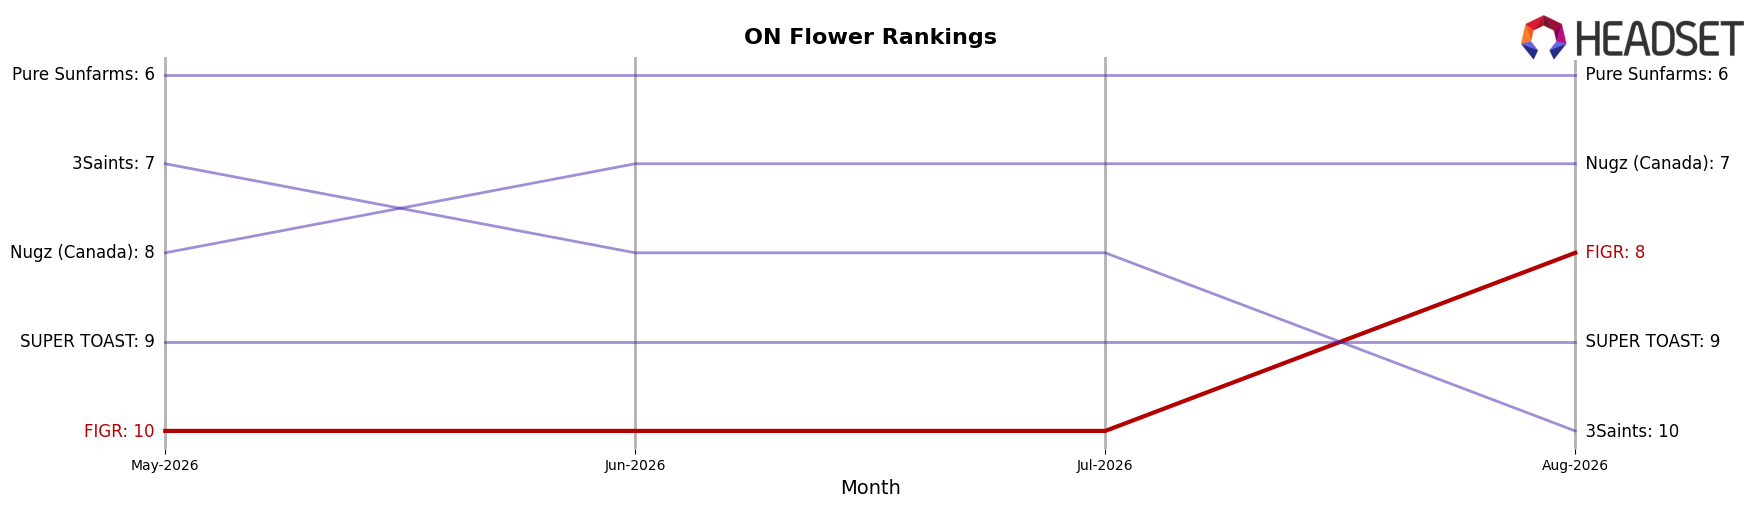
FIGR ranks #8 in ON Flower in August 2026, improving 6 positions from #14 year over year, and edging up 2 spots from #10 in May 2026; this is also a peak rank of #8 in August 2026, indicating upward momentum within the top 10. Meanwhile, Shred holds #1 after rising from #2 with +18.6% YoY sales growth, and Spinach climbed from #4 to #2 with +27.5% YoY, while Big Bag O' Buds slipped from #1 to #4 despite +1.5% YoY growth; against this backdrop, FIGR’s #8 position versus #3 for Back Forty / Back 40 Cannabis and #5 for The Original Fraser Valley Weed Co. (with -17.4% YoY) points to share being redistributed toward brands with clearer velocity. The pattern implies FIGR’s rank trajectory—up 6 places YoY to a new peak and gaining 2 ranks in the last three months—positions it to compete for ranks #6-#7 if it converts momentum into sustained velocity against incumbents consolidating at #1-#3.
Notable Products
With no month-over-month movements above +50% or below -10% in August 2026, FIGR’s story is a consolidation around Pre-Roll multipacks: Jungle Fumes Pre-Roll 10-Pack (3.5g) held rank 1 with +37.7% MoM while Mellow Man Pre-Roll 10-Pack (3.5g) moved at +45.4% MoM into rank 2, and seven of the top ten SKUs are Pre-Rolls. Chatty Kathy Pre-Roll 10-Pack (3.5g) advanced at +22.4% MoM to rank 3, contrasted with single-pack Pre-Rolls like Chatty Kathy Pre-Roll (1g) at rank 10 with a modest +6.1% MoM, indicating consumer trade-up to multipacks as value anchors. Flower stayed present but secondary, with Jungle Fumes (28g) at rank 9 and Mellow Man (7g) at rank 6, while the leading multipack Jungle Fumes delivered $654,187 as a benchmark against which Pre-Roll share concentration is tightening. The mix implies FIGR is skewing assortment and demand toward high-velocity Pre-Roll 10-packs, orienting commercial focus toward value-driven, repeatable bundle formats over single sticks or large Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

