

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
CannaBiotix (CBX) is stocked at 507 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Sacramento, San Francisco, and Santa Ana. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
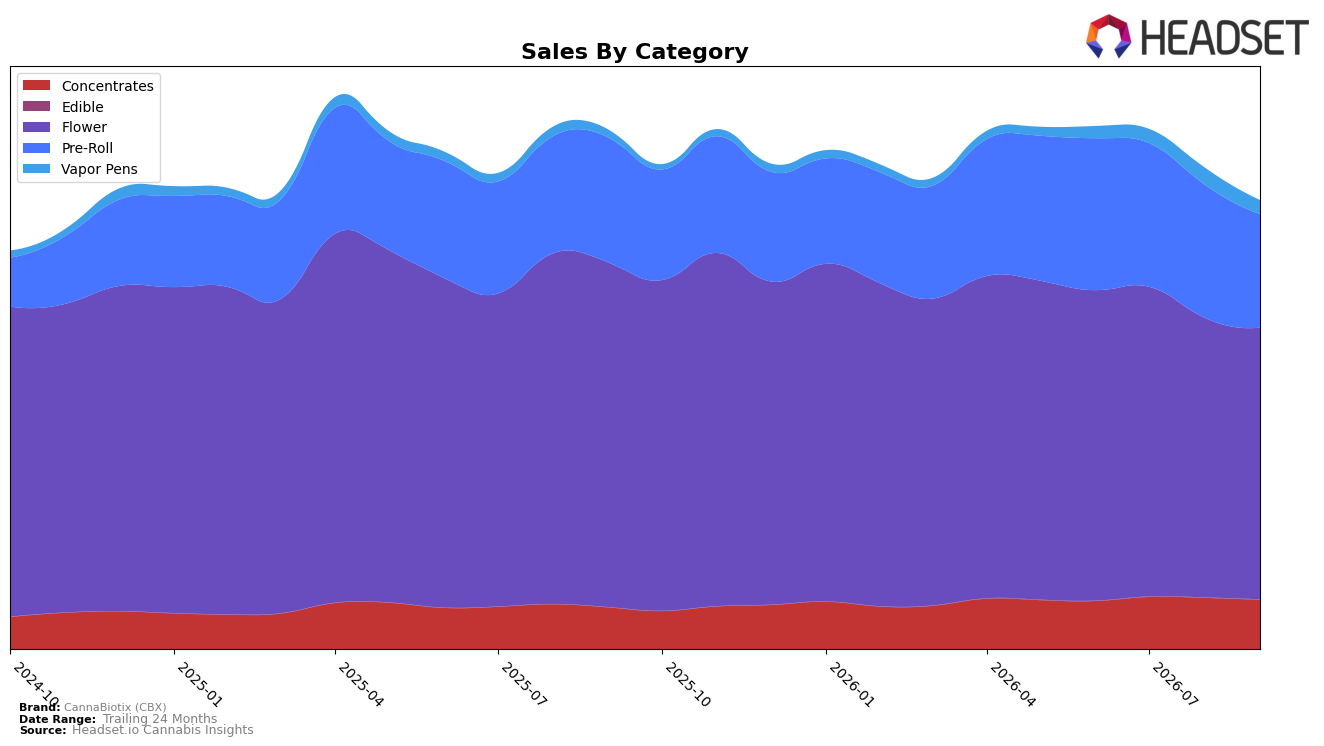
In September 2026, CannaBiotix (CBX) concentrated 60.64% of sales in Flower with year-over-year decline of 21.18% and month-over-month decline of 2.84%, while Pre-Roll held 25.30% share with a 9.15% YoY drop and a steeper 14.84% MoM pullback; by contrast, Concentrates reached 10.99% share with 18.53% YoY growth but slipped 3.71% MoM, and Vapor Pens at 3.05% share surged 77.44% YoY yet fell 18.29% MoM. Average price across the brand decreased 7.25% YoY to $24.16 as Flower’s higher ticket averaged $41.35 versus Pre-Roll at $12.78 and Concentrates at $20.92, indicating mix pressure from shrinking Flower and Pre-Roll volumes alongside pricing normalization; the pattern implies category reliance on Flower is amplifying overall YoY contraction despite selective growth pockets in smaller segments.
Maintaining rank 3 in Flower in California positions CannaBiotix (CBX) as a top-tier Flower player despite a 21.18% YoY decline there, while the 77.44% YoY lift in Vapor Pens and 18.53% YoY gain in Concentrates suggest adjacencies that can buffer volatility if scaled above their current 3.05% and 10.99% shares. With Pre-Roll’s 14.84% MoM contraction and overall MoM softness in Flower (-2.84%) and Concentrates (-3.71%), the mix skews toward categories under monthly pressure; the implication is that sustaining Flower rank while reallocating attention to faster-growing, lower-share formats could stabilize the 13.62% brand-level YoY decline and convert price-led elasticity into share capture rather than margin dilution.
Competitive Landscape
CannaBiotix (CBX) sits at rank 3 in California Flower in September 2026 after sliding 2 positions year over year from rank 1, while remaining flat versus June 2026 at rank 3; by contrast, STIIIZY moved up 1 spot YoY to rank 1 with 47.8% sales growth and CAM climbed from rank 3 to rank 2 alongside 28.9% YoY growth. Although CannaBiotix (CBX) peaked at rank 1 in January 2026 and now trails brands like Allswell at rank 4 and Oakfruitland rising from rank 11 to rank 5 on 73.5% YoY growth, the three-month hold at rank 3 implies a stabilized share position that depends on arresting further slippage against faster-rising leaders.

Notable Products
Cereal Milk Pre-Roll 4-Pack (2g) posted the steepest decline in September 2026 at -13.8% MoM while sliding to rank 4, contrasted by Cereal Milk (3.5g) rising 16.8% MoM at rank 1. Pre-Roll volatility was broad with GM-uhOh Pre-Roll 4-Pack (2g) down 17.3% at rank 8 and Dropane Pre-Roll (0.75g) down 15.4% at rank 7, while Super Mango Haze Pre-Roll (0.75g) was a rare gainer at +15.9% in rank 2. Four of the top ten are Pre-Roll SKUs concentrated between ranks 2 and 9, yet the largest dollar pull remains anchored in Flower with Cereal Milk (3.5g) and GM-uhOh (3.5g) holding ranks 1 and 10 and a combined September 2026 revenue of $940,652. The pattern implies CBX is leaning on flagship Flower for stability while rotating Pre-Roll assortment needs pruning or promo recalibration to reduce MoM drawdowns.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

