

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Canyon is stocked at 24 licensed dispensaries across Colorado, with the deepest coverage in Denver, Golden, Boulder, Grand Junction, and Louisville. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
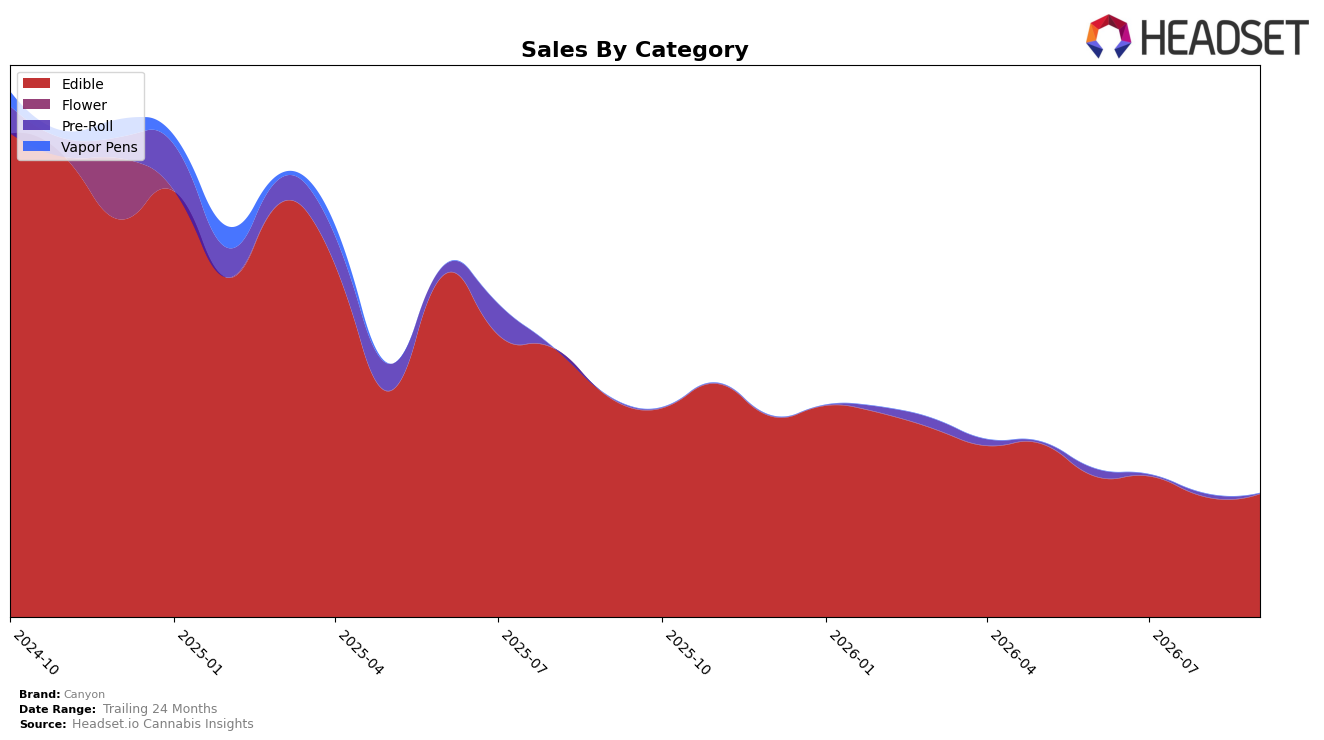
In September 2026, Canyon operated as a single-category brand with Edible accounting for 100.0% of sales, while Edible sales declined 44.2% year over year and rose 2.4% month over month. Average price fell 12.8% YoY to $12.38, with no offsetting category diversification, and rank in Edible sat at 32 in Colorado. The pattern implies Canyon has concentrated exposure to Edible volatility: a small 2.4% MoM lift and a 12.8% price decline are not yet bridging a 44.2% YoY contraction, so reliance on a single 100.0% category limits buffering capacity against demand swings.
These shifts point to a repositioning need: a 32 rank in Edible within Colorado combined with a 12.8% YoY price compression and a 44.2% YoY sales drop suggests current pricing and assortment are oriented toward defending share via discounting rather than trading up. With Edible at 100.0% mix and only a 2.4% MoM uptick, Canyon’s positioning skews toward a value-led stance that is not converting into rank gains, implying the brand must either recalibrate price-pack architecture within Edible or introduce adjacent categories to dilute sensitivity to single-category demand cycles.
Competitive Landscape
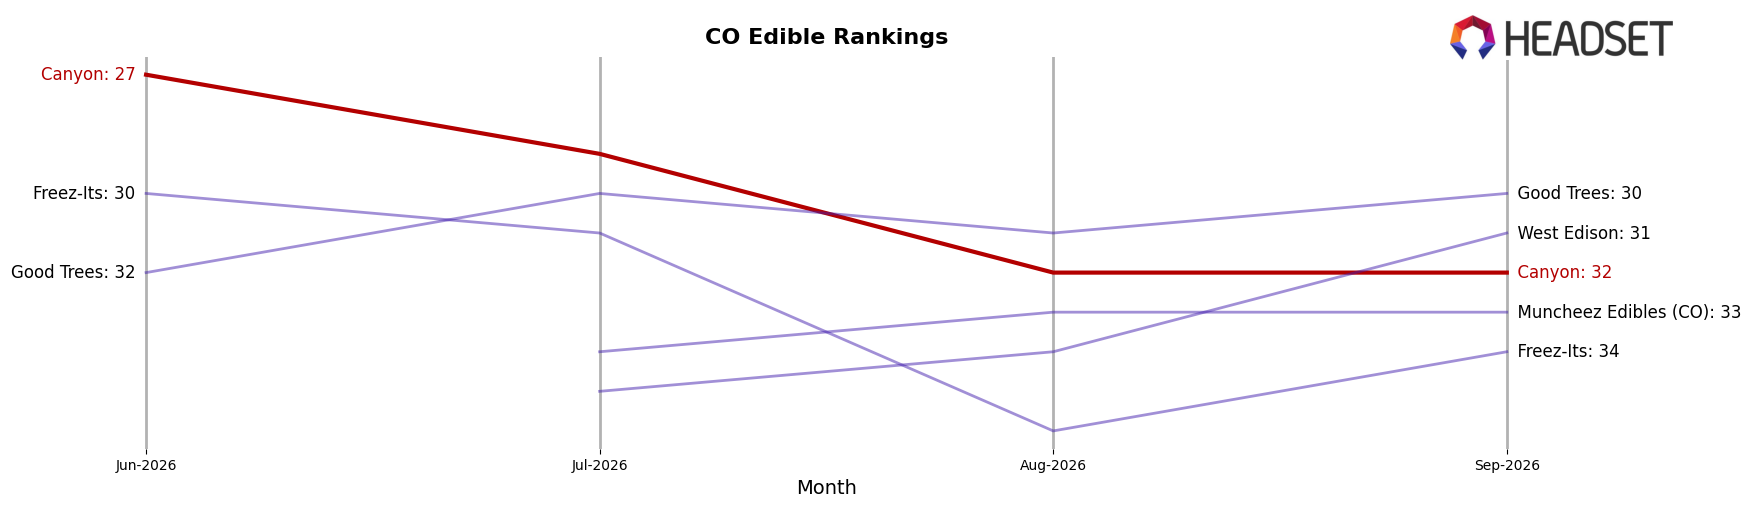
Canyon sits at rank #32 in September 2026, down 4 positions year over year from #28 and 5 positions from June 2026’s #27, while still 10 places below its peak of #22 from September 2024; in contrast, Wana moved to #1 from #2 year over year and Wyld slipped to #2 from #1 as its sales declined 23.8% year over year. With Dialed In Gummies steady at #3 and growing sales 30.6% year over year while Canyon’s rank fell 5 spots over three months and 4 spots year over year, the pattern implies Canyon is ceding relative shelf position as faster-rising leaders consolidate the top five.
Notable Products
Chew It - Blueberry Pomegranate Rosin Gummies 10-Pack (100mg) delivered the standout move in September 2026 with an 87.0% month-over-month surge and a climb to rank 5, while Chew It - Blue Raspberry Rosin Gummies 20-Pack (100mg) jumped 73.7% MoM to rank 3. In contrast, Suck It - Sativa Strawberry Lemonade Hard Candy 40-Pack (100mg) fell 21.2% MoM and slid to rank 2 from a prior leadership position, and Lick It - Strawberry Lemonade Lollipop (10mg) dropped 44.5% MoM to rank 9. With four of the top five slots occupied by Chew It gummies and the category’s No. 1 product up 3.4% MoM at rank 1, the mix points to a pivot toward rosin-forward gummies and away from hard candy.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

