
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Green Label Cannabis is stocked at 20 licensed dispensaries across Colorado, with the deepest coverage in Denver, Boulder, Colorado Springs, Aspen, and Avon. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
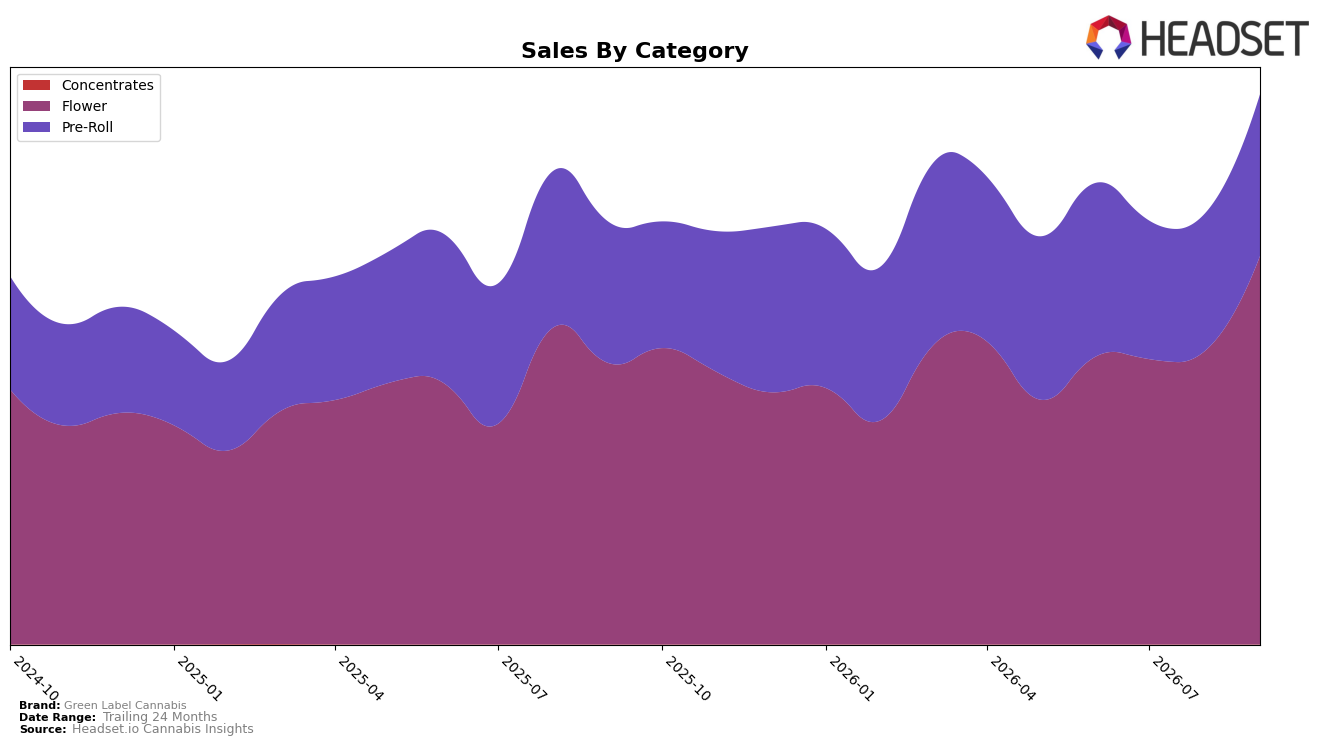
In September 2026, Green Label Cannabis concentrated 70.62% of sales in Flower with year-over-year growth of 38.04% and month-over-month growth of 32.49%, while Pre-Roll accounted for 29.38% of sales with 14.45% YoY and 17.72% MoM. Average price rose 11.20% YoY to $13.43 as Flower carried a higher price point at $25.60 versus Pre-Roll at $6.27, and brand sales advanced 30.16% YoY alongside a 48.63% 24‑month lift. With Flower ranked 1 in Colorado, the mix shift toward higher-growth Flower and a double‑digit MoM expansion in both categories implies deliberate momentum capture in core inhalables rather than dilution into adjacent forms.
The combination of a 1st‑place Flower rank in Colorado and a 70.62% mix concentration, paired with 32.49% MoM Flower growth versus 17.72% in Pre-Roll, indicates category leadership is being leveraged to pull price and volume without overextending assortment. Given brand sales grew 30.16% YoY while Flower outpaced that at 38.04% and Pre-Roll lagged at 14.45%, the portfolio is tilting toward the category where the brand over-indexes in share and rank; this positioning suggests defensible pricing power and a focus on depth in Flower rather than breadth across formats.
Competitive Landscape
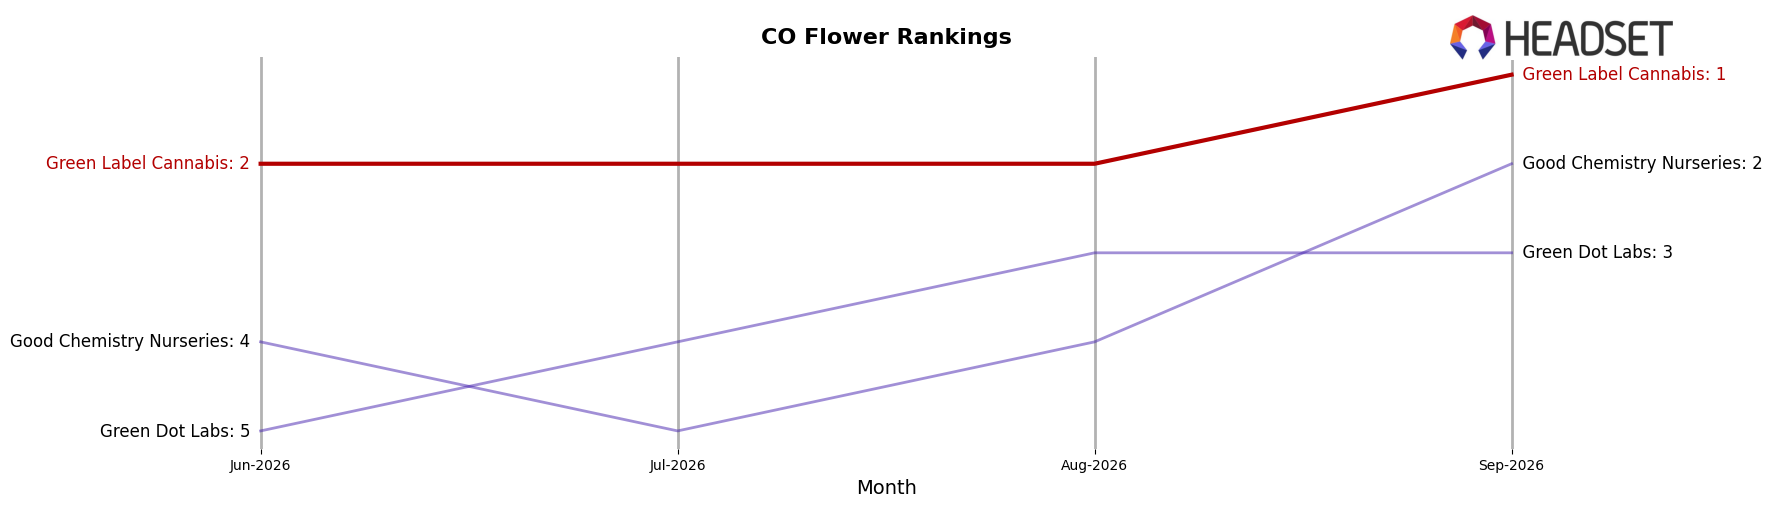
Green Label Cannabis is ranked #1 in CO Flower in September 2026, unchanged YoY from #1, while moving up from #2 three months ago to #1 now; that stability contrasts with Good Chemistry Nurseries at #2 after improving from #3 YoY and Green Dot Labs at #3 after rising from #4 YoY. Meanwhile, Seed & Strain Cannabis Co. slipped to #4 from #2 YoY despite a -33.5% sales change, and In The Flow advanced to #5 from #12 YoY alongside a 113.5% sales increase; this mix of upward and downward mobility around the #1 spot implies Green Label Cannabis’s hold on the top rank is defended by consistency rather than outsized growth, suggesting future risk if faster risers convert momentum into share.
Notable Products
Tropical Banana Pre-Roll (1g) posted the standout move in September 2026 with a 115.7% month-over-month surge, landing at rank 3 while Lilac Diesel Pre-Roll (1g) gained 10.2% to hold rank 2. Apple Fritter Pre-Roll (1g) sat at rank 1 despite no reported month-over-month rate, and Durban Cookies Pre-Roll (1g) advanced 27.9% to rank 7 as Lemon Cookies Pre-Roll (1g) climbed 40.1% to rank 9, indicating velocity gains are concentrated mid-pack rather than only at the top. With all top 10 items concentrated in the Pre-Roll category and a single SKU exceeding 100% growth alongside multiple 25–40% risers, Green Label Cannabis is consolidating around pre-roll depth to prioritize momentum SKUs for near-term share capture.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

