
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
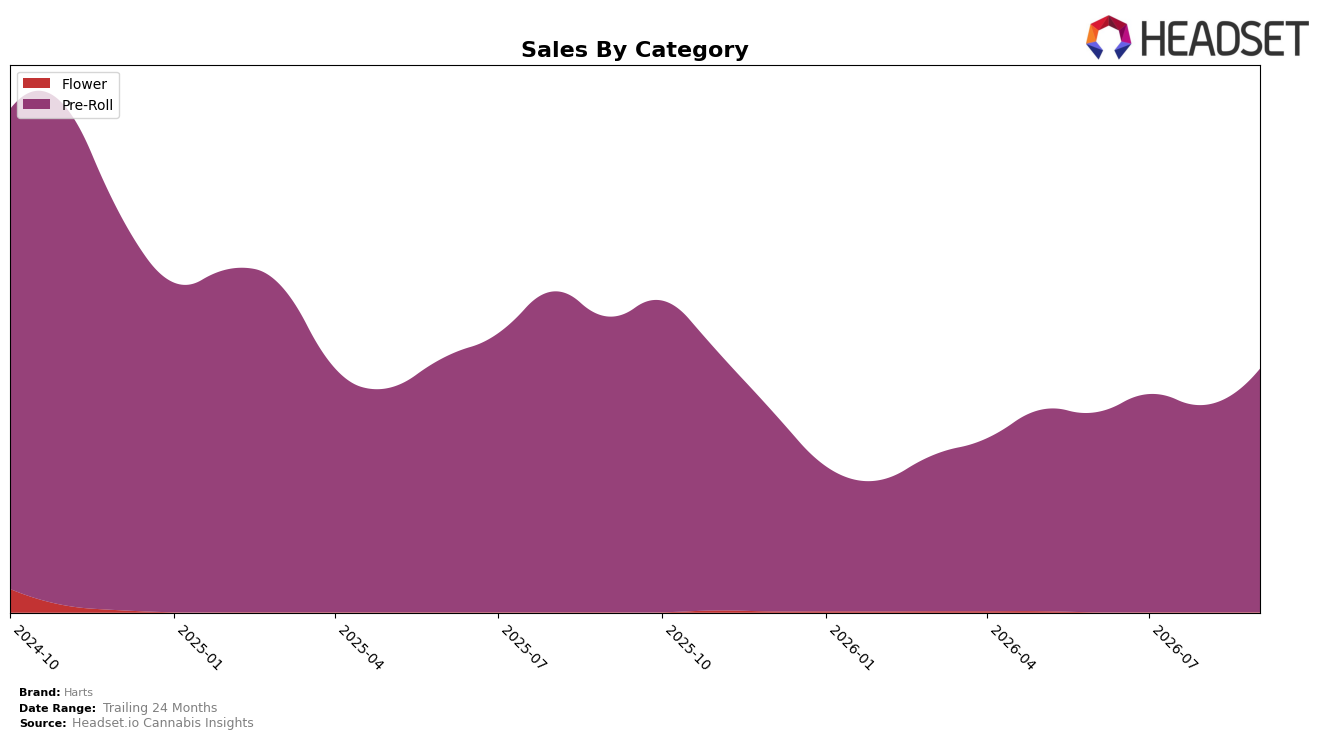
In September 2026, Harts operated as a single-category brand with Pre-Roll at 100.0% of mix, posting a year-over-year decline of 17.7% alongside a month-over-month increase of 17.5%; paired with a 4.4% average price decrease year over year, this combination indicates unit volumes likely rose month over month while lagging year over year. Within Saskatchewan Pre-Roll, Harts held rank 19 while carrying 100.0% category concentration, a positioning that moved opposite directions on the two time horizons (up month over month, down year over year), implying a tactical rebound rather than a structural share gain.
The mix locked at 100.0% Pre-Roll plus a 17.5% month-over-month sales lift suggest short-cycle responsiveness—likely promo-driven or format-led—while the 17.7% year-over-year contraction and a 4.4% price deflation point to pressure on baseline demand and price realization; together, that combination implies a value-leaning posture rather than premium stretch. Sitting at rank 19 in Saskatchewan with a 51.0% two-year sales contraction and full reliance on Pre-Roll concentrates risk in one lane, meaning the current momentum is more about capturing transient deal- or assortment-driven traffic than expanding into higher-margin segments.
Competitive Landscape
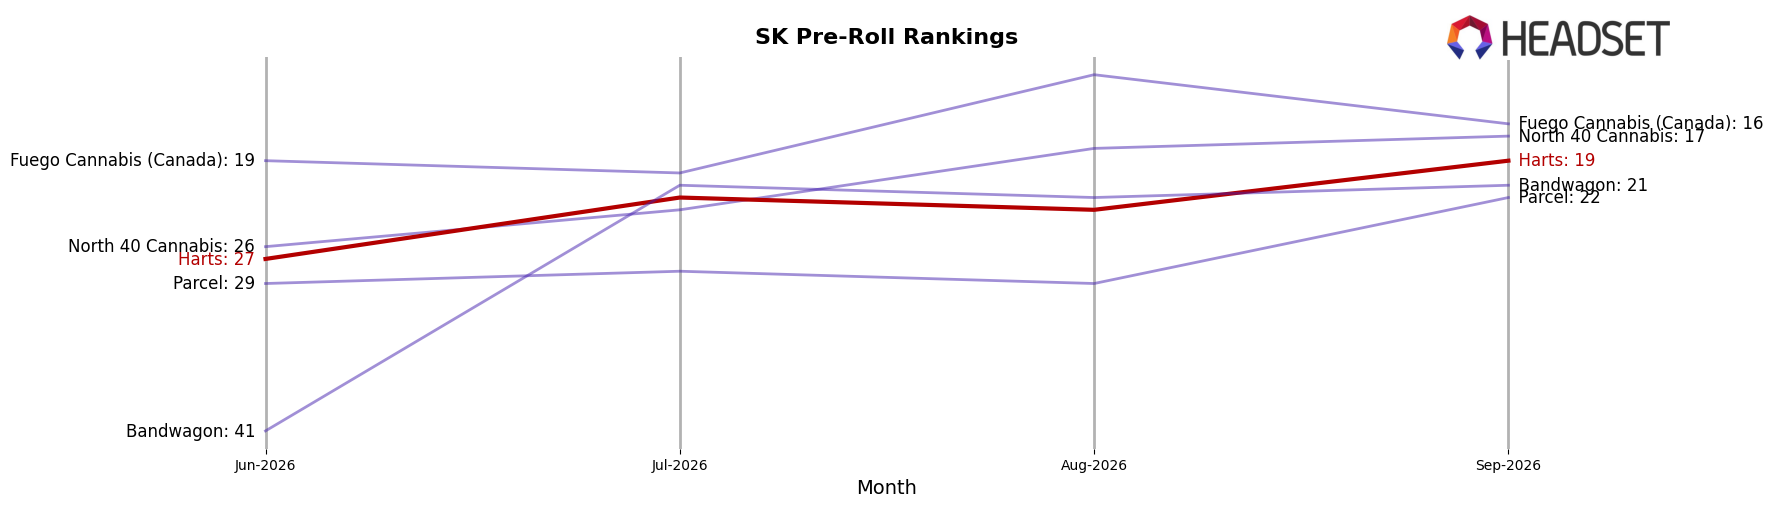
Harts ranks #19 in SK Pre-Roll in September 2026, down 1 position from #18 year over year, but up 8 positions versus June 2026 when it sat at #27; the brand’s peak of #12 in November 2024 sets a higher-water mark that contrasts with the current tier. Competitors are moving in the opposite direction: Doobie Snacks climbed from #6 to #2 with 179.6% YoY sales growth, while General Admission improved from #8 to #4 alongside 95.0% YoY growth, indicating share consolidation above rank #10. With Back Forty / Back 40 Cannabis stable at #1 and Spinach inching from #3 to #5 amid 13.9% growth, the mix at the top tightened even as Harts rebounded quarter-on-quarter by 8 ranks; the trajectory implies Harts is stabilizing mid-pack but will require a step-change to re-enter the low-teens band it last reached in November 2024.
Notable Products
Aceberry Pre-Roll 10-Pack (3.5g) posted the largest move in September 2026 with +102.9% MoM to rank 2, while Blue Breath Pre-Roll 10-Pack (3.5g) jumped +108.2% MoM to rank 6, implying momentum is coalescing mid-table rather than at the very top. Watermelon Zkittlez Pre-Roll 10-Pack (3.5g) held rank 1 despite an -11.1% MoM decline and $23,963 in sales, while King Louis Blunt 10-Pack (3.5g) rose +40.0% MoM at rank 3, signaling share is rotating toward SKUs with faster monthly velocity even as the leader softens. With all visible top products in September 2026 concentrated in the Pre-Roll category, the mix implies Harts is leaning into multi-pack inhalables and nurturing a bench of fast risers rather than depending on a single flagship.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

