

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
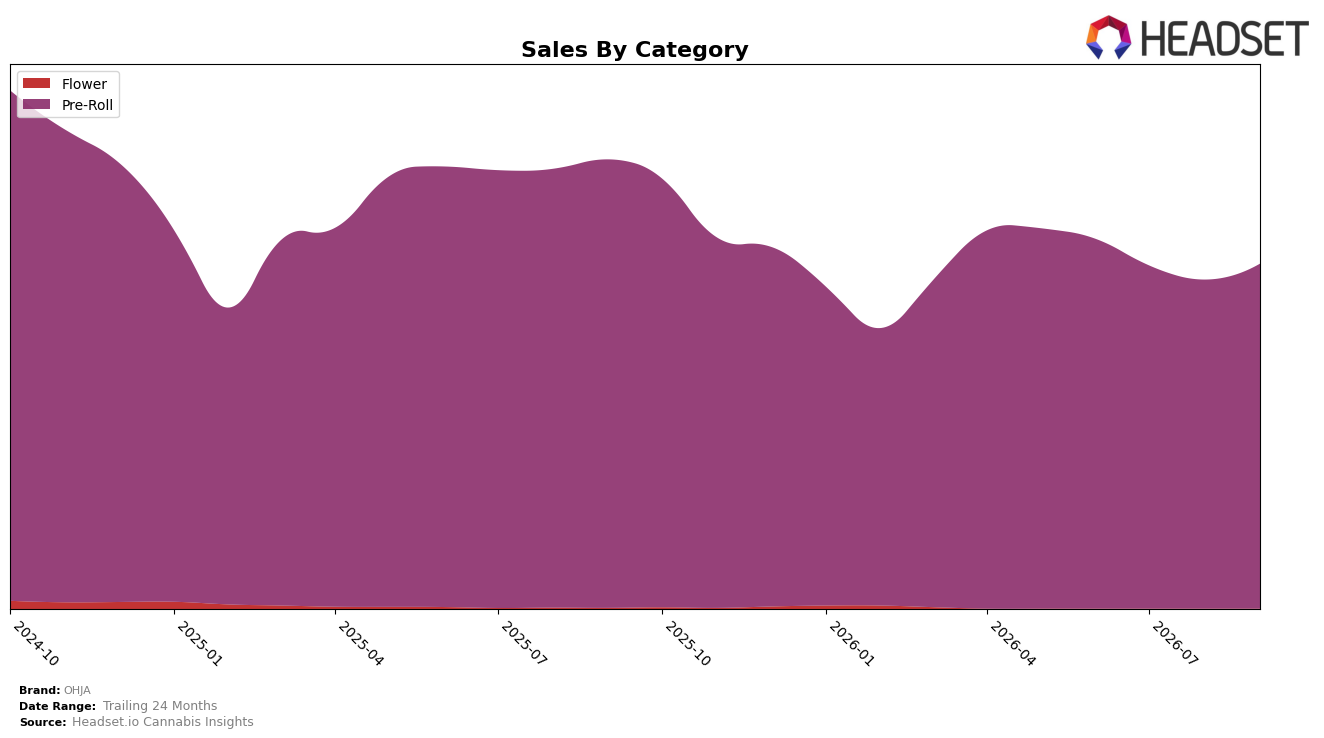
In September 2026, OHJA concentrated entirely in Pre-Roll with a 100.0% category mix, while brand sales declined year over year by 23.24% and Pre-Roll sales within the mix fell by 23.11%. Month over month, Pre-Roll sales rose 4.84% as average price increased 4.39% YoY, and the brand held rank 15 in Pre-Roll within Saskatchewan. With ON as the top market and only one category in play, the combination of a YoY contraction of more than 23% and a MoM uptick of 4.84% implies OHJA is relying on short-cycle velocity or pricing recovery within a single-category footprint rather than diversified demand.
The 100.0% reliance on Pre-Roll alongside a 4.84% MoM lift and a 23.24% YoY decline implies vulnerability to category cyclicality, as any Pre-Roll headwinds translate directly to brand performance. Holding rank 15 in Pre-Roll in Saskatchewan while average price is up 4.39% YoY suggests the brand is trading on price resilience over mix expansion; the pattern points to a need for product or pack-size architecture shifts within Pre-Roll rather than cross-category moves to stabilize share when YoY pressure exceeds 20%.
Competitive Landscape
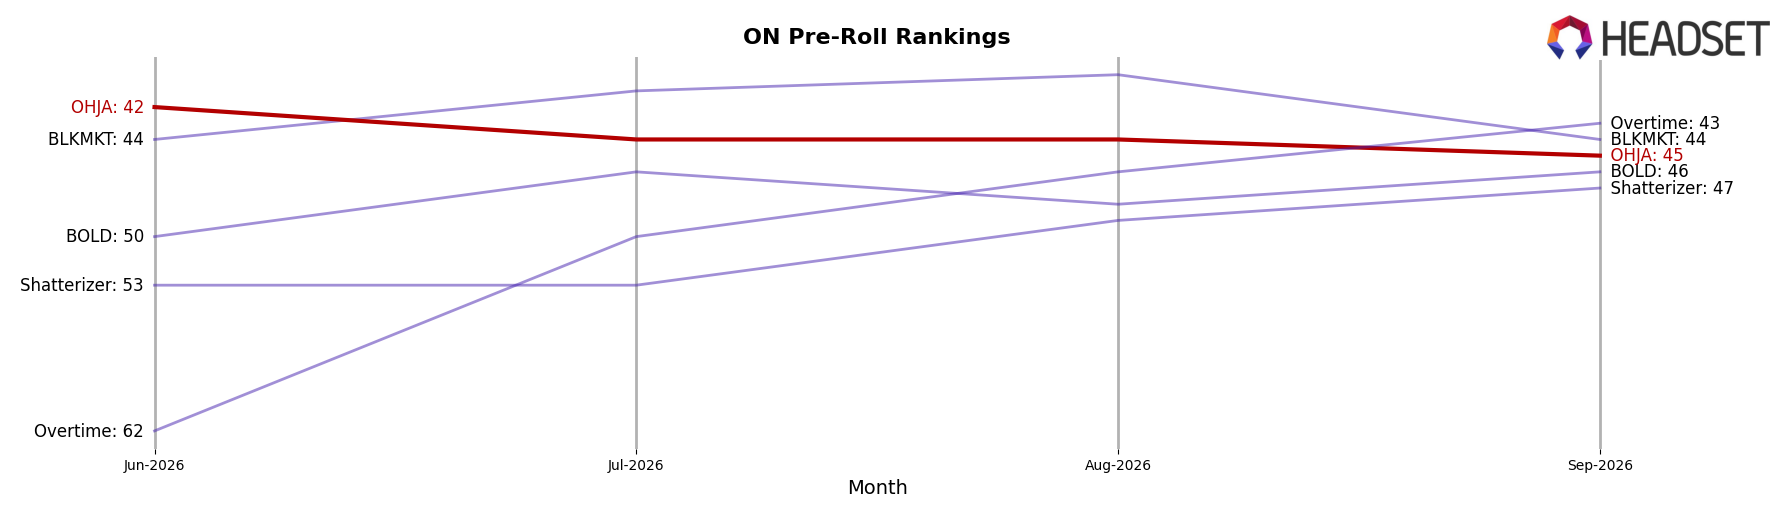
OHJA sits at rank #45 in ON Pre-Roll for September 2026, down 11 places from #34 year over year, and 3 places softer than June 2026’s #42, while still well below its peak at #26 from September 2024; meanwhile, Back Forty / Back 40 Cannabis moved up from #2 to #1 as its sales rose 46.6% year over year, and General Admission slipped from #1 to #2 as sales fell 38.2%, indicating that leadership churn at the top coincides with OHJA’s drift downward in the middle tier. The competitive center is compressing as Thumbs Up Brand climbed from #8 to #3 on 62.1% growth and Spinach jumped from #17 to #4 with 141.2% growth, while Claybourne Co. fell from #4 to #5 on a 21.8% decline, implying OHJA’s year-over-year rank erosion is less about category contraction and more about share being absorbed by faster-advancing rivals.
Notable Products
El Jefe Pink Pre-Roll 10-Pack (3.5g) posted the steepest decline in September 2026 at -13.9% MoM while holding rank 2, and Lemon Cherry Gelato Pre-Roll 10-Pack (3.5g) fell -12.4% at rank 4, signaling slippage among mid-table anchors. In contrast, Lime Mjto Pre-Roll 10-Pack (3.5g) climbed +26.9% MoM to rank 3 and Raspberry Diesel Pre-Roll 10-Pack (3.5g) grew +11.1% while maintaining rank 1 with $129,224 in sales. With all top-10 entries concentrated in the Pre-Roll category and three SKUs moving more than 10% MoM in opposite directions, the mix implies OHJA is consolidating around flagship Pre-Rolls while pruning or repositioning flavor variants that are losing velocity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

