

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Heirbloom by CBX is stocked at 215 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, La Mesa, San Francisco, and Sacramento. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
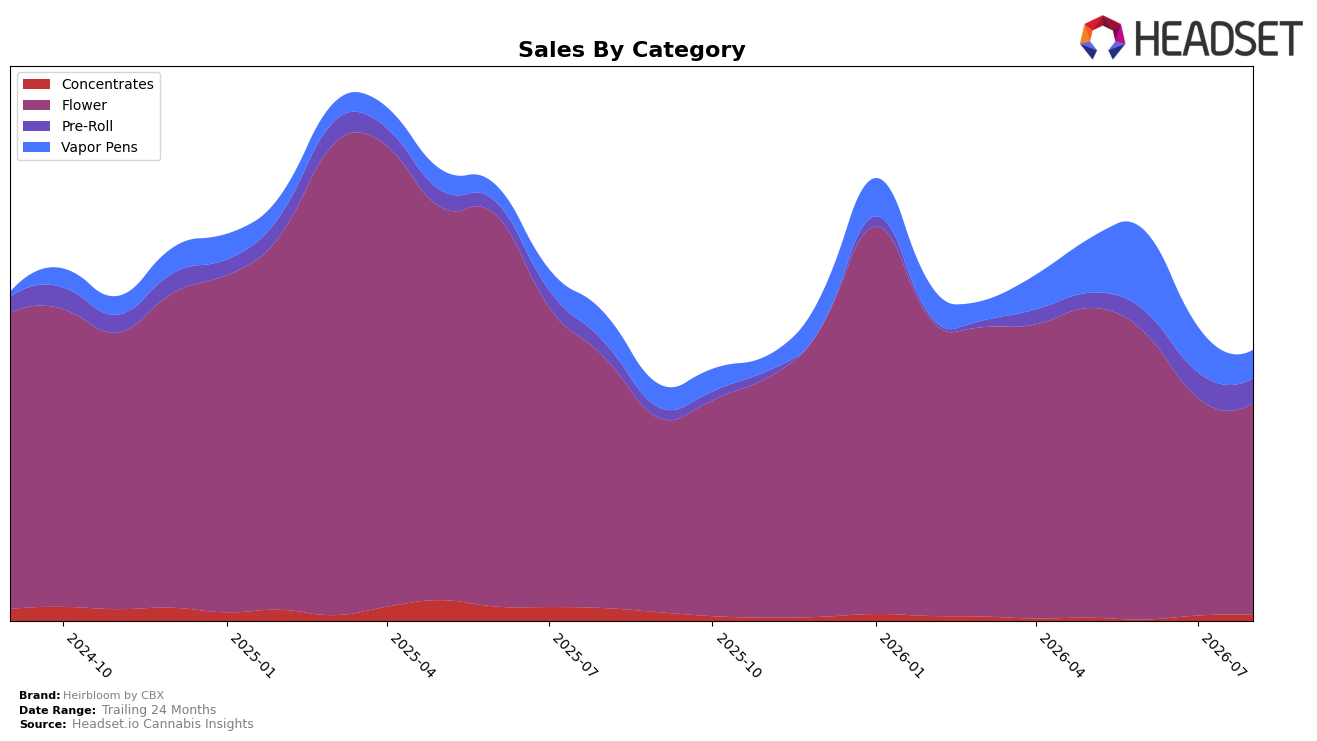
In August 2026, Heirbloom by CBX concentrated 73.94% of sales in Flower, where year-over-year declined 15.23% and month-over-month slipped 2.54%, while Vapor Pens held 11.61% share with a 2.23% YoY drop but a sharper 33.42% MoM pullback. Pre-Roll rose 45.34% YoY to 10.28% share despite a 3.58% MoM dip, and Concentrates, at 4.18% share, fell 35.20% YoY but grew 6.91% MoM. With an average price down 17.15% YoY to $21.40 and overall brand sales down 11.20% YoY, the pattern implies a recalibration toward value within a Flower-heavy mix that is still losing momentum MoM while Pre-Roll emerges as the only YoY growth engine.
These shifts indicate the brand is overexposed to a weakening Flower base (49th rank in Flower in California) while the expanding Pre-Roll (+45.34% YoY, 3.58% MoM decline) provides diversification but not yet enough MoM stability to offset Vapor Pens’ 33.42% MoM contraction. The 6.91% MoM uptick in Concentrates alongside a 35.20% YoY decline suggests opportunistic recovery pockets that, combined with the 17.15% YoY price decrease, position Heirbloom by CBX to lean into lower-priced formats and pack sizes where Pre-Roll and selective Concentrates can mitigate Flower’s 2.54% MoM drag and improve category balance.
Competitive Landscape
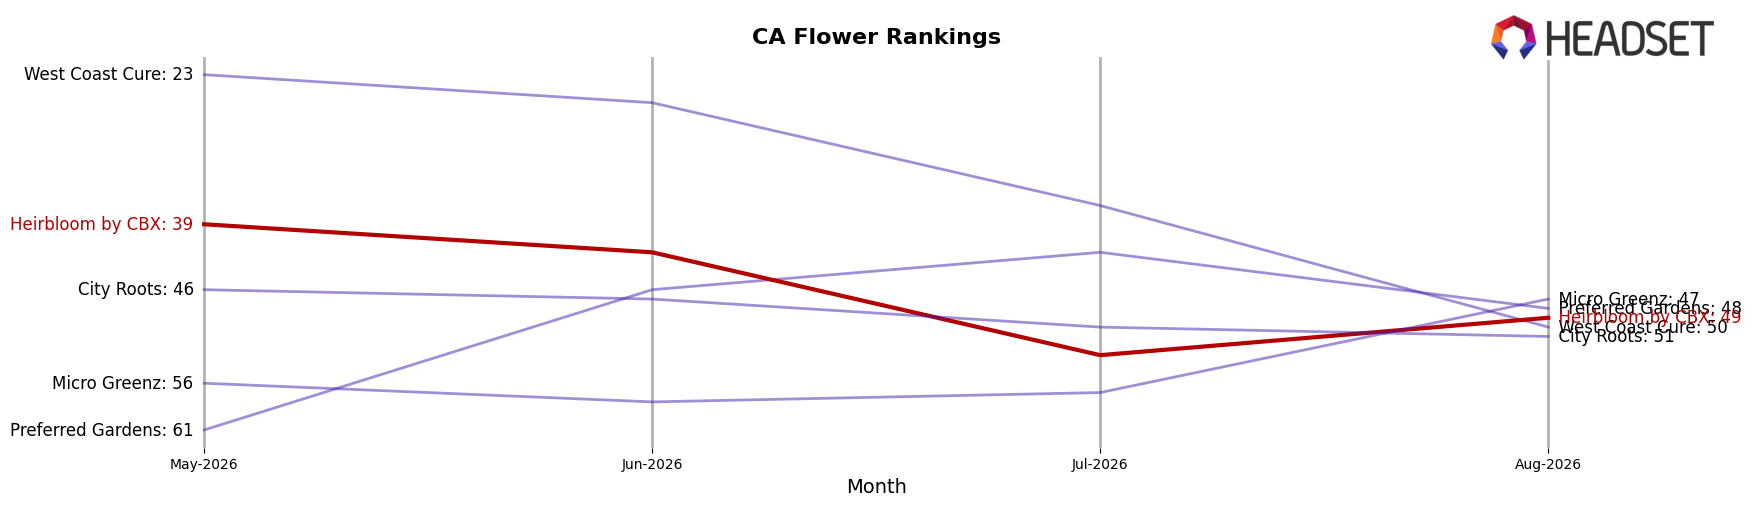
Heirbloom by CBX sits at rank #49 in California Flower in August 2026, slipping 2 positions year over year from #47 while falling 10 spots since May 2026 from #39, and remaining 25 places below its April 2025 peak at #24; meanwhile, STIIIZY climbed from #2 to #1 with 50.4% YoY sales growth and Oakfruitland jumped from #14 to #5 with 79.9% YoY growth, indicating that Heirbloom by CBX is losing share of rank momentum as faster-accelerating leaders widen the gap.
Notable Products
Master Kush (3.5g) posted the headline move in August 2026 with a 135.4% month-over-month surge to claim rank 2, while Super Silver Haze Pre-Roll (0.75g) fell 24.3% to rank 8, and Durban Poison (3.5g) slipped 17.4% but still held rank 1. Blueberry (3.5g) rose 55.0% to rank 3, and Watermelon Live Resin Sauce Disposable (0.5g) declined 8.9% at rank 5, indicating a split between accelerating core Flower and softening non-Flower formats. Four of the top ten are Flower SKUs concentrated in eighths, and that cluster includes Green Crack (3.5g) at rank 7 with a 6.1% dip, implying assortment gravity around classic strain eighths is pulling share from Pre-Roll and Vapor Pens. The product mix points to Heirbloom by CBX leaning into flagship Flower velocity while letting slower Pre-Roll and select Vapor Pen items take a secondary role.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

