

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Highly Casual is stocked at 306 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Grand Rapids, Monroe, and Kalamazoo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
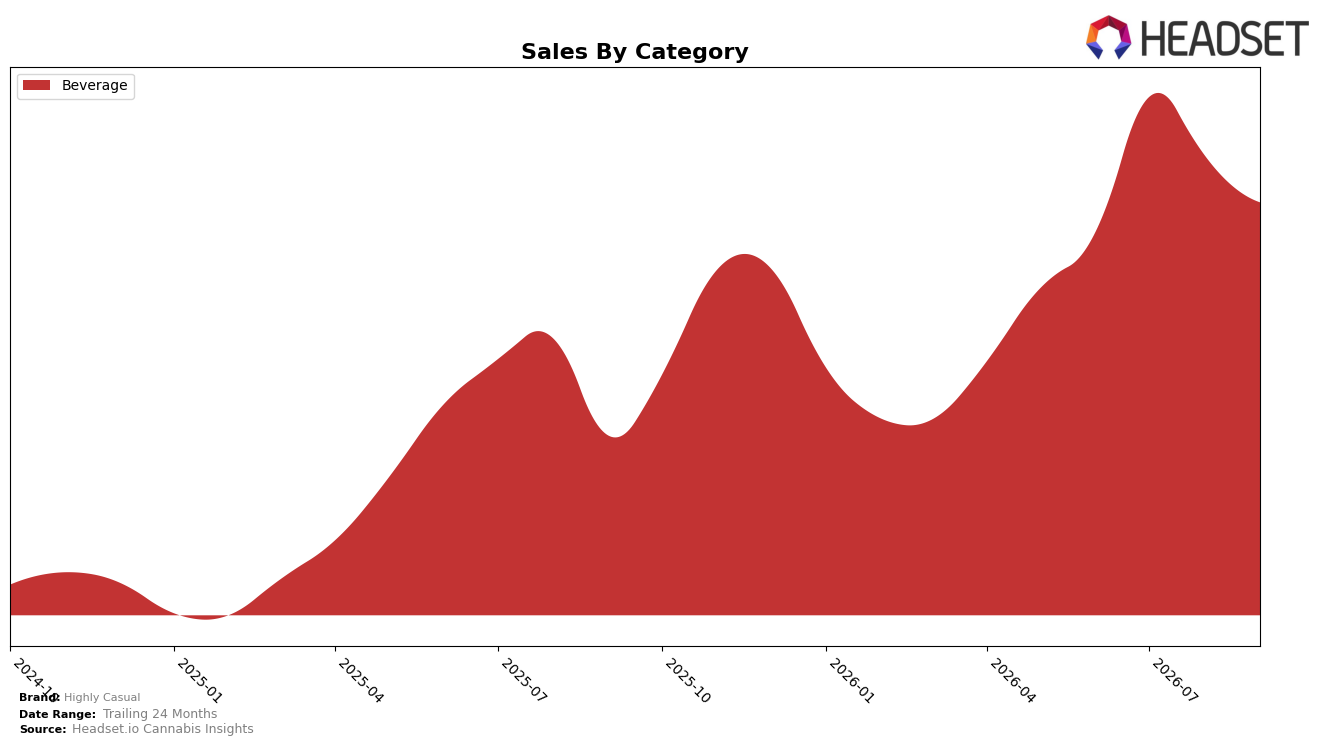
Highly Casual operated as a single-category brand in September 2026, with Beverage accounting for 100.0% of sales, posting year-over-year growth of 64.25% alongside a month-over-month decline of 7.32%. Average item price rose 12.59% year over year to $4.92, while category focus remained concentrated at 100.0% share with no diversification into adjacent formats. The pattern implies price-led revenue expansion within Beverage on a yearly basis, offset by short-term volume or velocity pressure month over month that narrows near-term momentum while preserving annual trajectory.
With Beverage at 100.0% of mix and a category rank of 4 in Michigan, a 64.25% year-over-year lift paired with a 7.32% monthly dip suggests positioning as a scale player whose gains rely more on sustained demand and pricing than on broad assortment. The 12.59% price increase combined with negative month-over-month movement points to sensitivity to recent pricing or seasonal shifts, implying that defending rank 4 will likely depend on stabilizing monthly sell-through without diluting the single-category focus that powered the annual growth.
Competitive Landscape
Highly Casual sits at #4 in MI Beverage in September 2026 after rising 4 positions year over year from #8, and edging up 1 spot from June 2026 when it was #5; however, its best-ever placement of #3 in December 2025 indicates a modest retreat from peak while still advancing versus last year. In contrast, Mary Jones held at #1 year over year despite a -8.5% sales change, and CQ (Cannabis Quencher) climbed from #6 to #3 on 74.1% YoY sales growth, placing a direct constraint on Highly Casual’s path back to #3. Taken together, the +4 rank improvement YoY alongside a slide from the December 2025 peak implies Highly Casual is gaining baseline position but is being outpaced at the top end, so future rank upgrades hinge on outgrowing fast risers rather than just holding current share.

Notable Products
Cold Brew Coffee (10mg THC, 12oz, 355ml) posted the steepest decline at -33.9% and slid to rank 6, while Fruit Punch Drink (50mg THC, 12oz, 355ml) fell -27.8% to rank 5; by contrast, Haha Blast - Tropical Soda (50mg) rose 20.8% to rank 7 and CBD/THC 1:1 Lemon + Lime Seltzer (5mg CBD, 5mg THC, 12oz, 355ml) gained 11.1% at rank 4. Honeycrisp Apple Hang Ten Seltzer (10mg THC, 12oz, 355ml) stayed at rank 1 with +4.3% month over month and $30,684 in sales, while the High 5 - CBD/THC 1:1 Variety Seltzer 6-Pack (30mg CBD, 30mg THC, 12oz, 355ml) dipped -2.2% at a tied rank 6. Four of the top ten are CBD/THC 1:1 Seltzer SKUs, and their mixed results (from -4.4% to +11.1%) alongside the -0.6% for High 5 - CBD/THC 1:1 Strawberry & Watermelon Seltzer (5mg CBD, 5mg THC, 12oz, 355ml) indicate selective retention for low-dose formats over higher-dose legacy drinks. The pattern suggests Highly Casual’s commercial direction is consolidating around 10mg and 1:1 sessionable seltzers while deprioritizing 50mg and non-seltzer niches that are ceding rank.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

