
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Hitz Cannabis is stocked at 124 licensed dispensaries across Washington and California, 111 of them in Washington, with the deepest coverage in Vancouver, Seattle, Everett, Spokane, and Tacoma. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
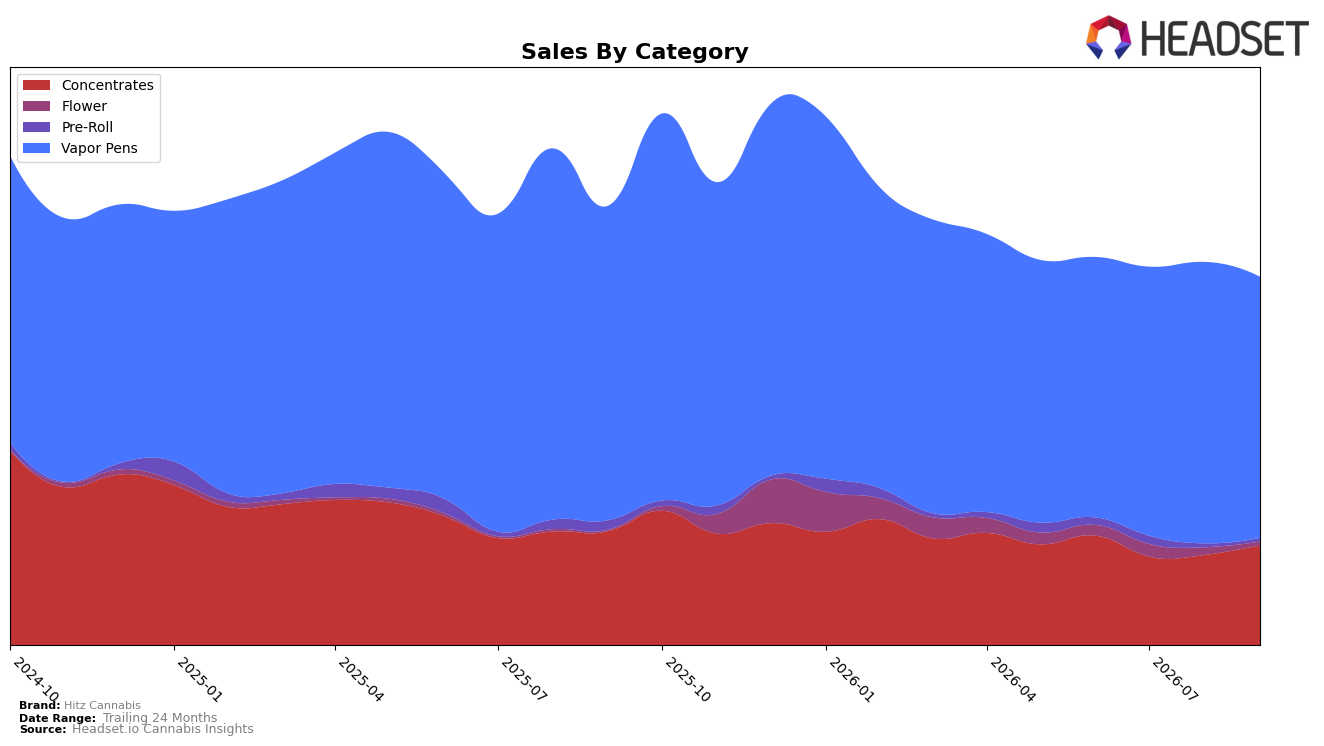
Hitz Cannabis concentrated 70.26% of September 2026 sales in Vapor Pens, where sales declined 16.89% year over year and 7.17% month over month, while Concentrates rose 10.38% month over month despite a 12.52% year-over-year drop to reach 27.01% share; minor lines diverged, with Flower up 87.62% year over year but down 41.66% month over month at 1.40% share, and Pre-Roll down 53.70% year over year and 5.73% month over month at 1.32% share. With brand-level sales down 15.99% year over year and average price down 8.94%, the mix tilt toward Vapor Pens amplified downside versus the relatively smaller but improving month-over-month performance in Concentrates, implying that short-term stability hinges on rebalancing away from the single category that drove both the largest share and the steepest declines.
Positioning-wise, a 70.26% Vapor Pens dependency alongside a rank of 32 in Washington Vapor Pens suggests that incremental share gains will be harder to capture if category headwinds persist, whereas Concentrates’ 10.38% month-over-month growth at 27.01% share offers near-term traction despite its 12.52% year-over-year drag. The opposing signals in Flower (up 87.62% year over year but down 41.66% month over month) and persistently contracting Pre-Roll (down 53.70% year over year and 5.73% month over month) indicate that niche expansion must be selective, implying that price-led defense in Vapor Pens and targeted scaling in Concentrates would diversify risk and reduce sensitivity to a single-category downturn.
Competitive Landscape
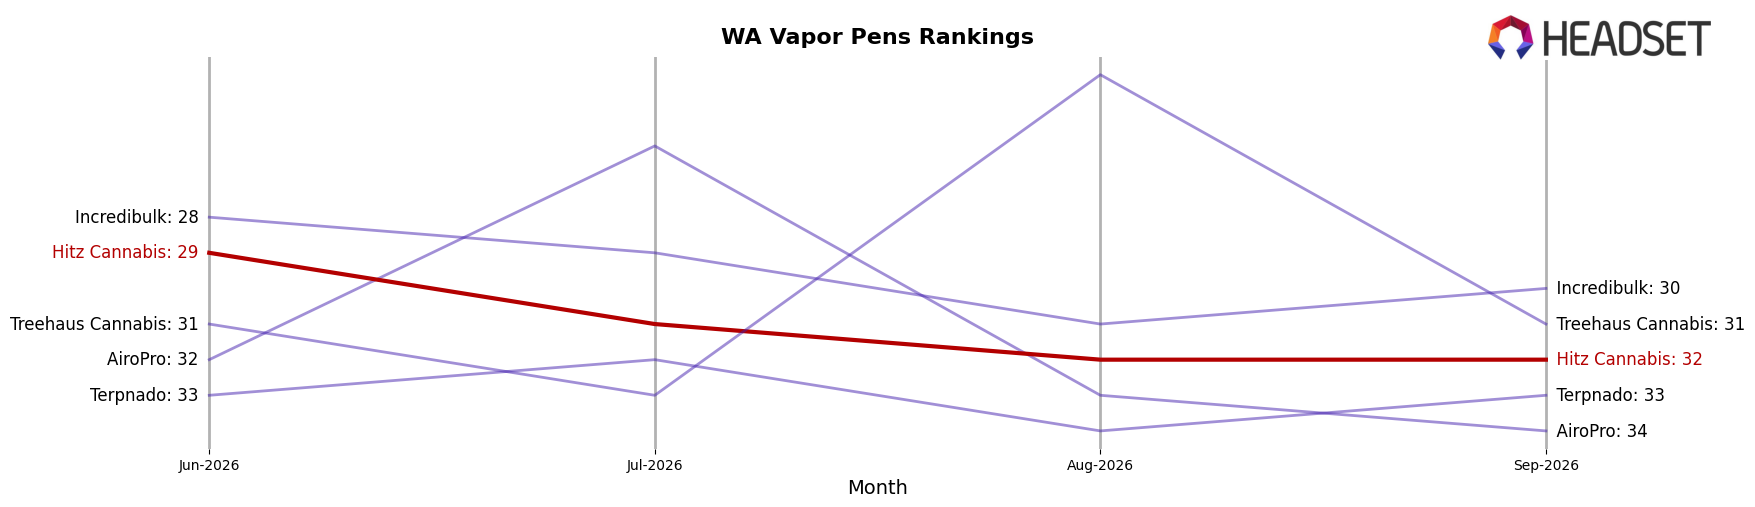
Hitz Cannabis ranks #32 in WA Vapor Pens in September 2026, sliding 6 positions from #26 year over year and down 3 spots from #29 since June 2026, while its prior peak was #21 in October 2025; by contrast, Crystal Clear climbed from #3 to #1 with a 26.4% year-over-year sales increase and Mfused fell from #1 to #2 alongside a 30.9% decline, indicating share is consolidating at the top as mid-pack brands lose rank. With peers like Plaid Jacket advancing from #6 to #3 on 23.3% growth while Phat Panda dropped from #2 to #5 on a 25.1% decline, Hitz Cannabis’s 6-rank YoY retreat and 11-rank gap from its October 2025 peak imply its trajectory is drifting from recovery toward entrenchment in the lower third unless mix or pricing changes alter its position.
Notable Products
Blackberry Kush Distillate Cartridge (1g) posted the steepest decline in September 2026 at -31.1% MoM while slipping to rank 3, contrasted by Bubba Kush RSO Syringe (1g) rising 48.0% MoM to rank 2. Blackberry Kush RSO (1g) grew 14.7% MoM at rank 1, and Gorilla Glue #4 Distillate Cartridge (1g) fell -18.5% MoM at rank 9. Four of the top ten are Concentrates SKUs, and four are Vapor Pens, indicating share is tilting toward RSO-led Concentrates as Vapor Pens face mixed momentum; the pattern implies Hitz Cannabis is consolidating around RSO formats while culling underperforming vape variants.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

