
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
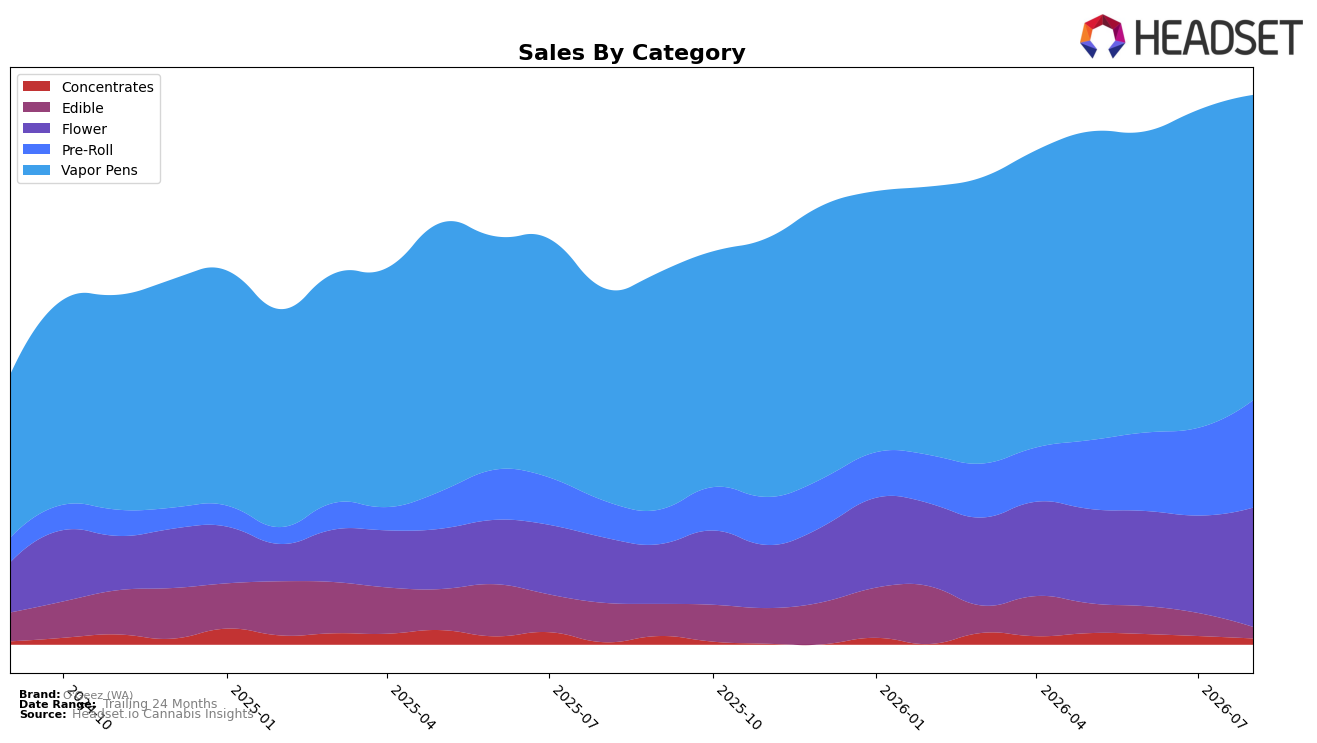
O'Geez (WA) concentrated nearly half of sales in Vapor Pens at 49.94% share with year-over-year growth of 39.71% but a month-over-month dip of 3.78%, while Flower expanded to 21.46% share with 63.15% YoY and 18.68% MoM growth. Pre-Roll reached 19.62% share with 123.70% YoY and 18.27% MoM growth, whereas Edible contracted to 4.89% share with -46.68% YoY and -26.64% MoM change; Concentrates held 4.10% share with 16.22% YoY but -8.35% MoM. The mix indicates a pivot toward inhalables as Flower and Pre-Roll add 37.95 percentage points of combined YoY growth while Vapor Pens cool MoM, implying diversification away from single-category dependence in Washington.
With Vapor Pens still the largest at rank 17 in Washington and 49.94% share but declining 3.78% MoM, the accelerating gains in Pre-Roll (123.70% YoY, 18.27% MoM) and Flower (63.15% YoY, 18.68% MoM) suggest headroom to reposition the portfolio mix toward combustible formats. The sharp Edible decline (-46.68% YoY, -26.64% MoM) alongside a modest Concentrates pullback (-8.35% MoM, 16.22% YoY) implies resource reallocation can prioritize the two fastest-growing share engines while using Vapor Pens’ scale to defend presence; the thesis is to treat Vapor Pens as the traffic anchor while channeling incremental assortment and pricing into Flower and Pre-Roll to balance the 0.40% YoY brand-wide average price uptick and sustain the 42.13% YoY sales trajectory.
Competitive Landscape
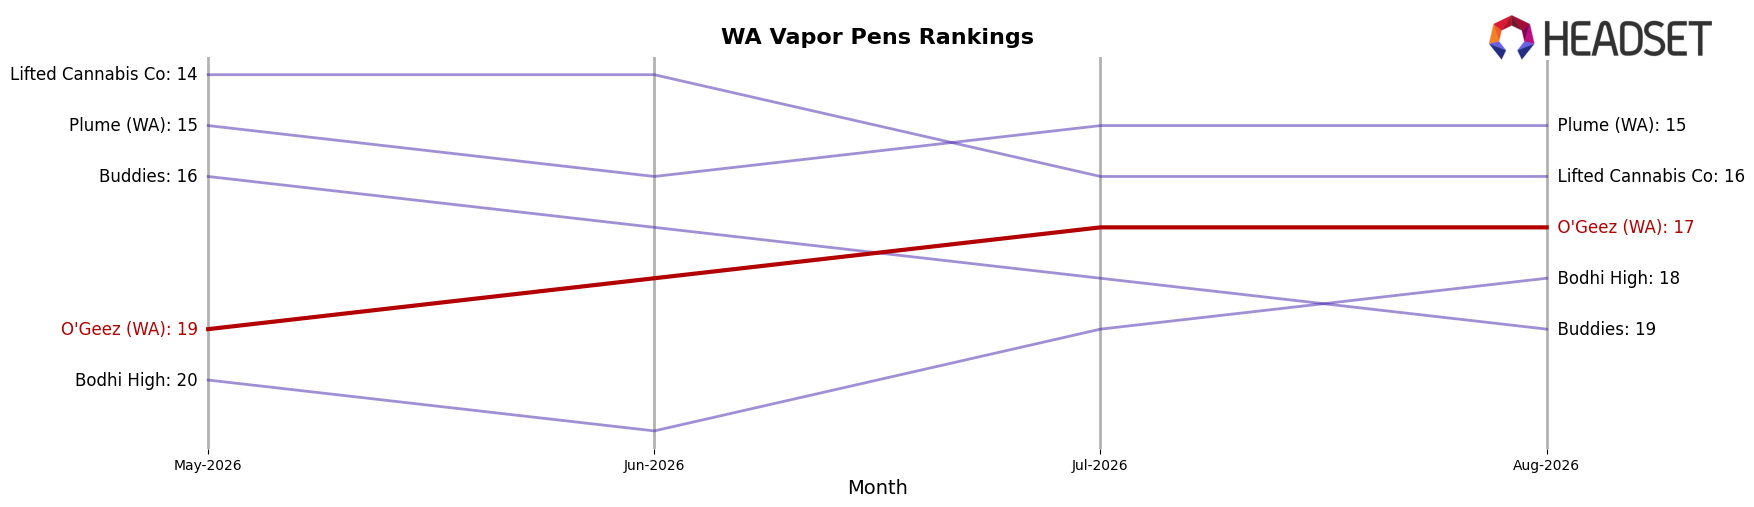
O'Geez (WA) sits at rank #17 in WA Vapor Pens in August 2026, improving 8 positions from #25 year over year, and edging up 2 positions from #19 in May 2026 to reach its peak at #17 in August 2026; in contrast, Crystal Clear climbed from #3 to #1 with 19.4% YoY sales growth while Mfused slipped from #1 to #2 amid a 32.6% YoY decline, indicating that O'Geez (WA) is gaining rank share in a reshuffling top tier where leadership is rotating and mid-pack mobility is achievable.
Notable Products
Blue Dream Distillate Cartridge (1g) posted the steepest decline at -16.18% MoM, slipping to rank 7 while Alaskan Thunder Fuck Distillate Cartridge (1g) fell -11.00% to rank 6, pointing to softening demand among mid-tier Vapor Pens. In contrast, Pineapple Express Distillate Cartridge (1g) rose +16.73% to rank 1 and Granddaddy Purple Distillate Disposable (1g) inched up +4.53% at rank 2, indicating leadership consolidation at the top. Eight of the top ten are Vapor Pens, while the lone Edible — CBD/THC 1:1 Strawberries & Cream Gummies 10-Pack (100mg CBD, 100mg THC) — dropped -26.92% to rank 3 despite $33,067 in August 2026 sales, concentrating category risk in inhalables. The mix implies O'Geez (WA) is leaning into a high-velocity Vapor Pen core where winners are concentrating share as trailing SKUs cycle down, signaling a need to refresh or prune underperforming cartridges while stabilizing the lone Edible anchor.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

