


Where to Buy
Junk is stocked at 11 licensed dispensaries across Oregon, with the deepest coverage in Portland, Oregon City, Beaverton, Depoe Bay, and Eugene. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
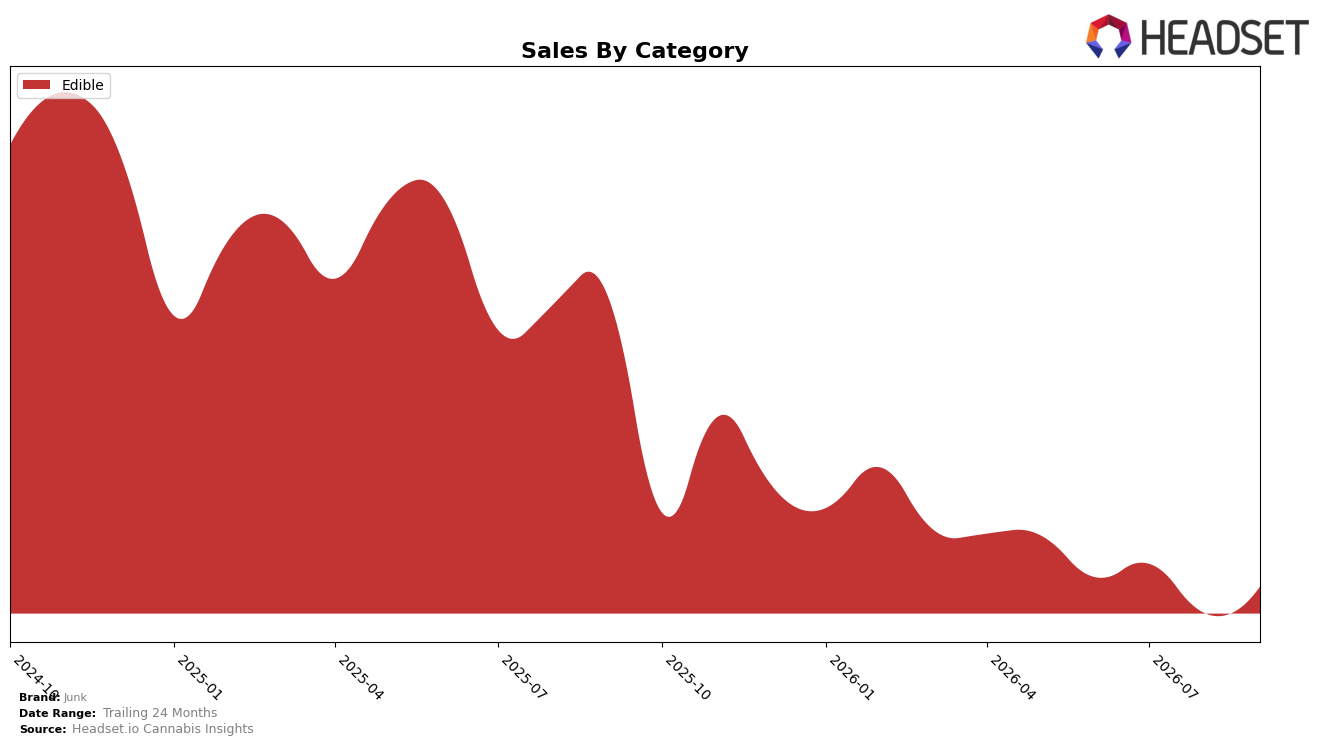
In September 2026, Junk operated as a single-category brand with Edible accounting for 100.0% of sales share, pairing a year-over-year sales change of -75.38% with a month-over-month rise of 38.96%. Average price fell 19.66% YoY to $13.38, while category share concentration stayed at 100.0%, indicating no cross-category offset despite a 24-month sales decline of -82.76%. This combination implies the September 2026 rebound was driven by Edible volume recovery within a narrowed portfolio, not by diversification or premium pricing.
The mix and pricing shifts suggest a repositioning pressure: a 100.0% Edible share alongside a -75.38% YoY sales change points to under-penetration in adjacent categories, while the 38.96% MoM gain and 19.66% YoY price drop indicate elasticity-driven lift rather than assortment breadth. With no rank reported in Oregon Edible and a 24-month decline of -82.76%, the current path implies Junk is trading price for volume in a single lane, which concentrates risk and caps reach unless the brand either restores price premium or reintroduces secondary categories.
Competitive Landscape
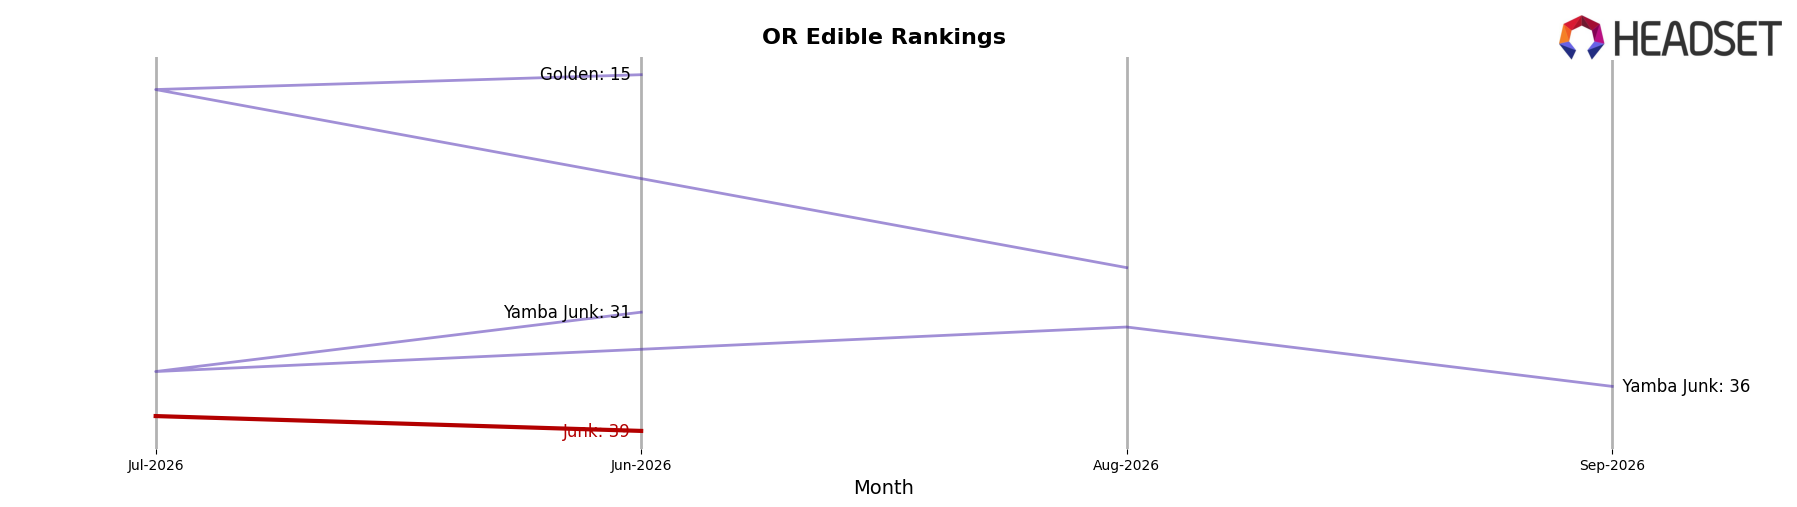
Junk sits at #37 in Oregon Edible for September 2026, down 16 places year over year from #21, and 2 places above June 2026’s #39, while still 21 places below its peak #16 from September 2024; by contrast, Wyld held #1 with a 4.3% YoY sales increase and Gron / Grf6n stayed at #2 despite a 5.0% YoY decline, indicating that even leaders with negative growth can maintain position as mid-tier brands like Junk lose rank depth. This relative slippage alongside leaders’ rank stability and mixed sales trends suggests Junk’s trajectory implies share erosion within the mid-pack unless a reversal in rank momentum converts the recent 2-place quarterly uptick into a sustained climb.
Notable Products
THC/CBN 2:1 Dreamboat Functional Magic Gummy 10-Pack (100mg THC, 50mg CBN) delivered the headline move with an 86.1% month-over-month gain to rank 1, while CBD/THC 1:1 Field Trip Functional Magic Gummies 10-Pack (100mg CBD, 100mg THC) fell 26.3% and slid to rank 4. Sleepy Dreamboat Gummies 10-Pack (100mg) rose 29.5% at rank 2, and Tiger Blood Gummies 10-Pack (100mg) added 8.2% at rank 3, indicating three of the top four slots are Edible SKUs within functional or flavor-led gummies. The concentration of Edibles in the top ranks alongside one sharp decline implies Junk’s product mix is coalescing around sleep-oriented and high-THC gummy formats while mixed-ratio CBD offerings are losing traction.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

