

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Kelso Kandy (aka Kelso Kreeper) is stocked at 101 licensed dispensaries across Washington, with the deepest coverage in Tacoma, Seattle, Spokane, Everett, and Vancouver. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
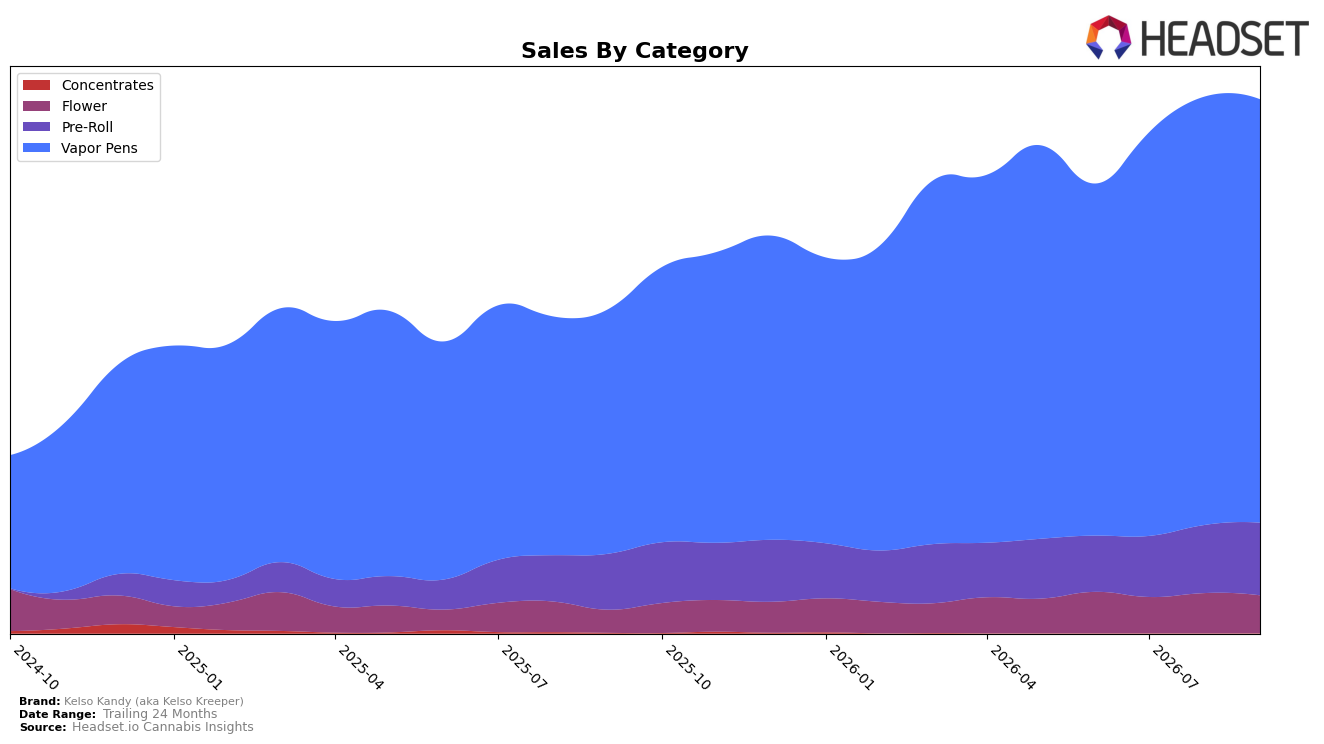
Kelso Kandy (aka Kelso Kreeper) concentrated 79.39% of September 2026 sales in Vapor Pens with 73.24% year-over-year growth but a 1.16% month-over-month decline, while Pre-Roll held 13.56% share with 30.07% YoY and a 6.68% MoM increase; Flower represented 7.05% share with 65.33% YoY but a 5.61% MoM drop. Across the portfolio, brand sales grew 65.00% YoY and the average price rose 3.40%, yet Vapor Pens’ average price sat at $7.46 versus $2.30 in Pre-Roll, pointing to mix-led revenue expansion concentrated in a single anchor category. The pattern implies upside concentration risk: September 2026 revenue depends on a category that is expanding YoY but softening MoM, while the smaller Pre-Roll line is gaining MoM traction that could cushion volatility.
Positioning skews toward value-access vapor as the top category ranks 21 in Washington Vapor Pens and carries the brand’s 79.39% mix, while the growing Pre-Roll segment’s 6.68% MoM and 30.07% YoY suggest an entry ramp for broader shelf presence. With Flower slipping 5.61% MoM despite 65.33% YoY, the brand’s near-term momentum hinges on stabilizing Vapor Pens MoM trends and selectively amplifying Pre-Roll where velocity is improving; this mix implies a tactical shift from single-category dependence toward a two-pillar assortment to preserve the 65.00% YoY brand uplift into future months.
Competitive Landscape
Kelso Kandy (aka Kelso Kreeper) sits at rank #21 in WA Vapor Pens in September 2026, improving 10 positions from #31 year over year, and edging up 4 spots from #25 in June 2026, while also matching its peak rank at #21 in September 2026; by contrast, Crystal Clear moved from #3 to #1 with a 26.4% YoY sales change and Mfused slipped from #1 to #2 alongside a -30.9% YoY sales change. This combination of a double-digit YoY rank gain and a recent quarter-on-quarter climb, alongside a reshuffling at the very top, implies Kelso Kandy (aka Kelso Kreeper) is on a catch-up trajectory where incremental distribution or product mix gains can convert recent rank momentum into entry toward the top 20.

Notable Products
Blue Hawaiian BHO Distillate Cartridge (1g) led September 2026 with rank 1 but slipped by 6.7% month over month, while Blue Razzberry Distillate Cartridge (1g) at rank 6 fell 8.8% and Golden Pineapple Distillate Cartridge (1g) at rank 9 declined 5.1%. In contrast, Banana Split Distillate Cartridge (1g) climbed 11.3% to rank 2 and Strawberry Distillate Cartridge (1g) gained 3.5% at rank 8, and nine of the top ten SKUs are Vapor Pens, concentrating mix risk in a single category. The single Pre-Roll, Watermelon Infused Pre-Roll (0.8g), eked out a 1.4% MoM lift at rank 5 against multiple Vapor Pen declines near the top, and the leading SKU’s $39,538 in sales did not prevent share from tilting toward mid-pack movers. The pattern implies reliance on a Vapor Pens core with softening at the very top and incremental wins in mid-tier flavors, suggesting near-term growth leans on breadth within pens rather than diversification.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

