

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
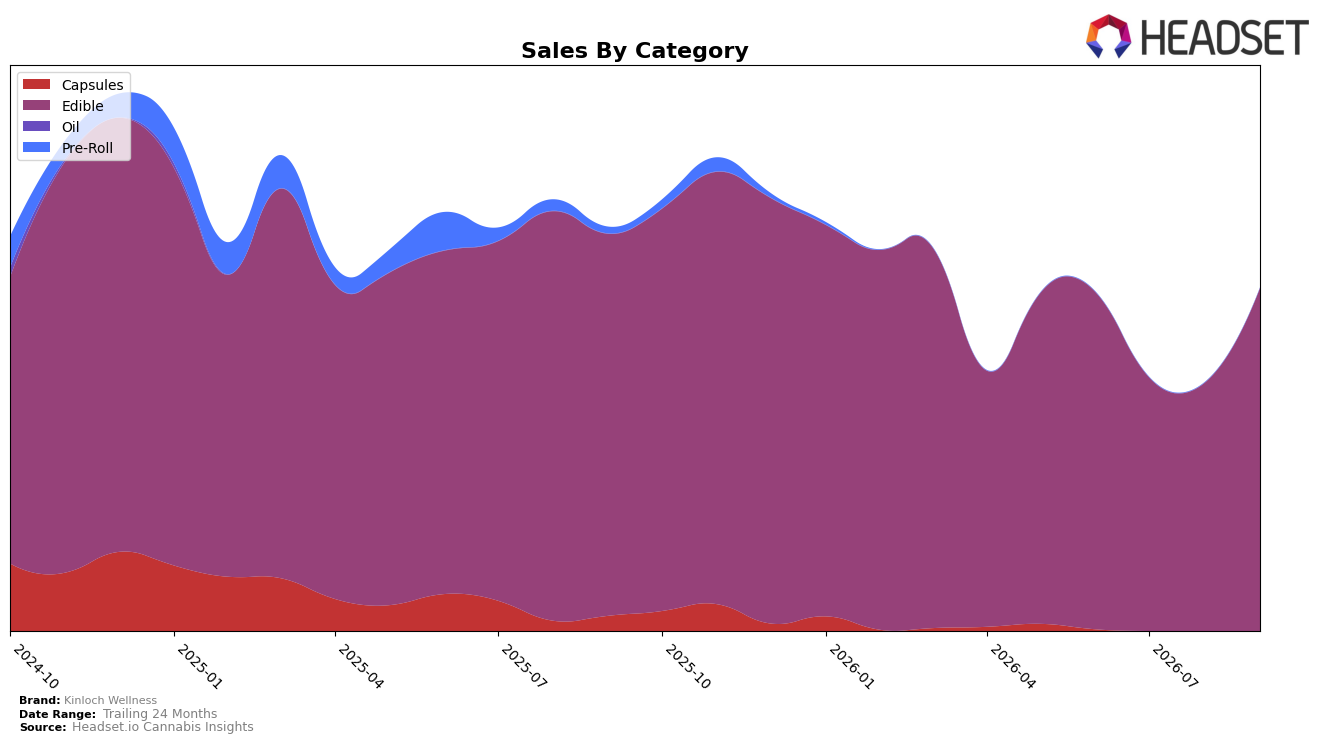
Kinloch Wellness operated as a single-category brand in September 2026, with Edible accounting for 100.0% of sales, up 38.23% month over month while down 10.25% year over year; this concentrated mix coincided with an overall brand sales decline of 15.06% YoY and a 24.48% drop versus 24 months. Average price reached $33.20, rising 28.03% YoY alongside the MoM volume rebound in Edibles, and the brand held rank 18 in Ontario Edibles; the pattern implies pricing power is countering, but not reversing, year-over-year softness concentrated in a single format.
The shifts imply Kinloch Wellness is leaning into premiumized Edibles—elevated pricing up 28.03% YoY and a 38.23% MoM sales jump—while its year-over-year Edibles contraction of 10.25% and brand-level −15.06% indicate price-led gains are not fully offsetting demand erosion. With Edibles at 100.0% of mix and a category rank of 18 in Ontario, the brand’s positioning hinges on defending share through differentiated offerings rather than portfolio breadth; this suggests near-term growth depends on sustaining MoM momentum without further elasticity drag at the $33.20 average price.
Competitive Landscape
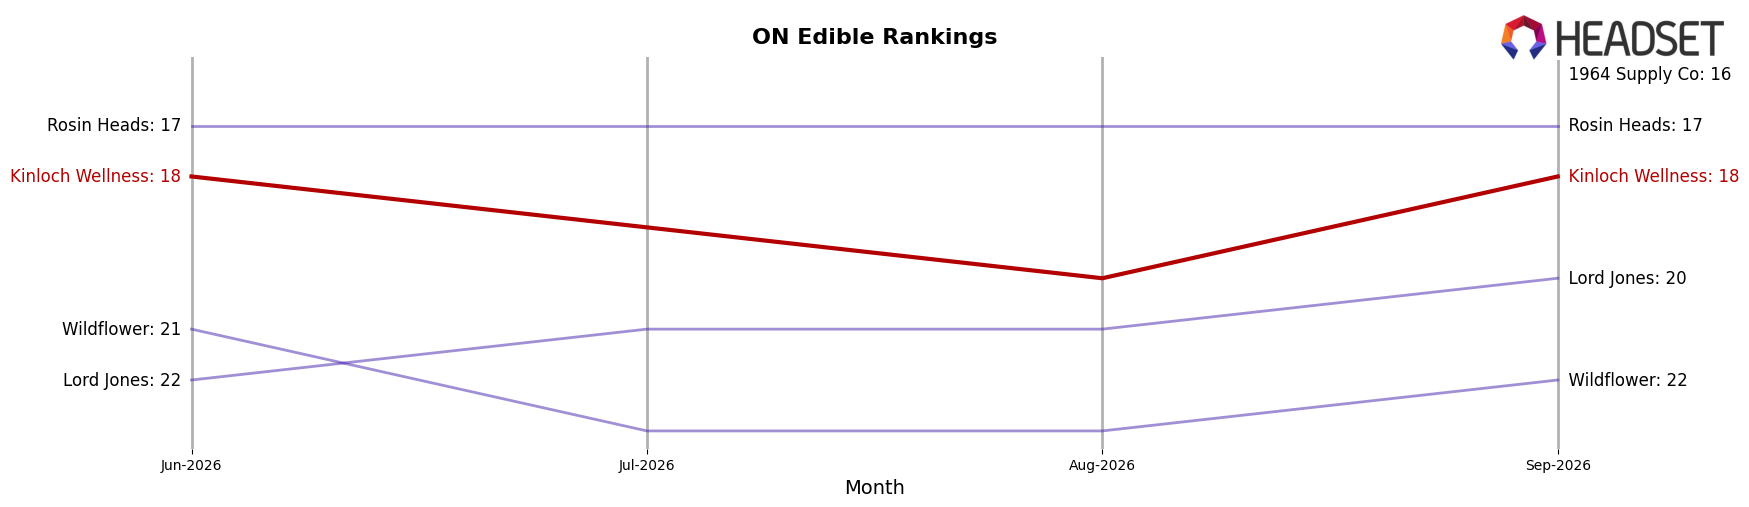
Kinloch Wellness is currently ranked #18 in ON Edible in September 2026, a 2-position improvement from #20 year over year, while its rank held flat versus three months ago at #18; this stability contrasts with Olli rising from #5 to #3 with 46.97% YoY sales growth and Wyld slipping from #4 to #5 despite 17.81% YoY growth. Compared with the top tier, Spinach remained #1 year over year with 7.30% YoY growth and Gron / Grön held #2 with 4.73% YoY growth, indicating a relatively fixed podium while Kinloch Wellness reached its peak rank of #18 in September 2026; the pattern implies Kinloch’s incremental ascent is tied to stability rather than share-taking, so future movement likely depends on breaking the mid-pack stasis as peers either advance (e.g., Olli) or soften (e.g., Wyld).
Notable Products
Elevate CBD Blackberry Lemon Gummy 30-Pack (900mg CBD) posted the largest month-over-month gain at 110.1% to rank 2, while Serene- CBD Green Apple Gummy 30-Pack (1500mg CBD) rose 41.5% and held rank 1. By contrast, CBZ CBD/CBN 2:1 Pomegranate Berry Gummy 4-Pack (80mg CBD, 40mg CBN) fell 50.9% to rank 5, and Refresh - CBD:CBG 1:1 Mango Gummies 15-Pack (300mg CBD, 300mg CBG) dropped 24.0% at rank 3. Five of the top six SKUs are Edibles, indicating a concentration in gummies that is tilting share toward high-dose CBD offerings at the expense of smaller CBN/CBG formats. The pattern implies Kinloch Wellness is consolidating around flagship CBD gummies with momentum concentrated in 30-pack formats, a mix that prioritizes velocity over breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

