


Where to Buy
Leafers is stocked at 88 licensed dispensaries across Arizona and Nevada, 60 of them in Arizona, with the deepest coverage in Phoenix, Mesa, Tucson, Glendale, and Chandler. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
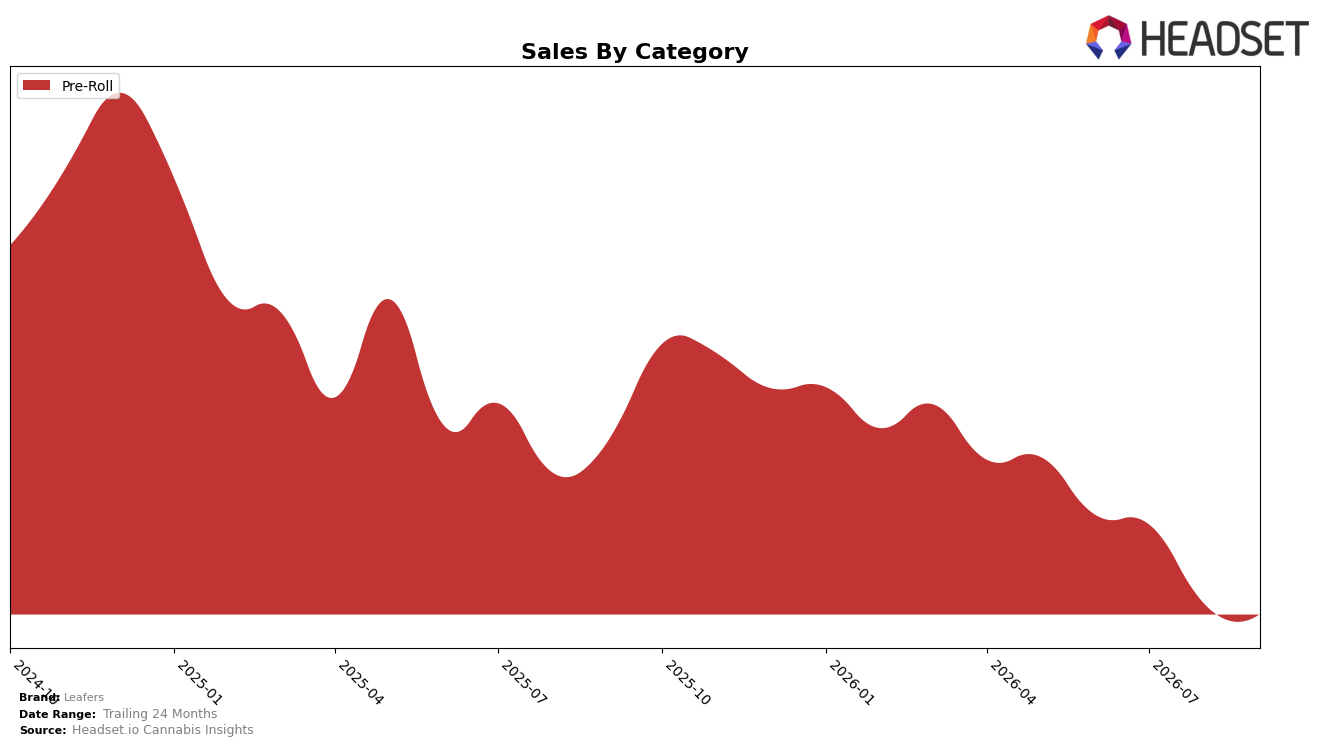
In September 2026, Leafers operated as a single-category brand with Pre-Roll at 100.0% of sales share, while Pre-Roll sales declined 31.1% year over year and 2.5% month over month. The average price fell 7.5% year over year to $15.03, indicating a price-led contraction alongside volume pressure, and Leafers held rank 11 in Pre-Roll within Arizona. The pattern implies concentration risk: a fully concentrated mix at 100.0% combined with a 31.1% year-over-year sales drop and an 11th-place rank suggests the brand’s exposure to category-specific headwinds is translating into share and pricing pressure.
The combination of a 2.5% month-over-month sales decline against a 7.5% year-over-year price decrease points to sustained elasticity effects rather than a short, promotional dip, while a 31.1% year-over-year contraction alongside rank 11 signals limited insulation from Pre-Roll category volatility. With the 24-month sales trend down 46.5% and Pre-Roll still at 100.0% share, the implication is that Leafers’ positioning is defined by price-sensitive Pre-Roll demand where deeper discounting is not converting into rank gains, suggesting the need to pivot mix or elevate differentiated propositions within Pre-Roll to avoid further erosion.
Competitive Landscape
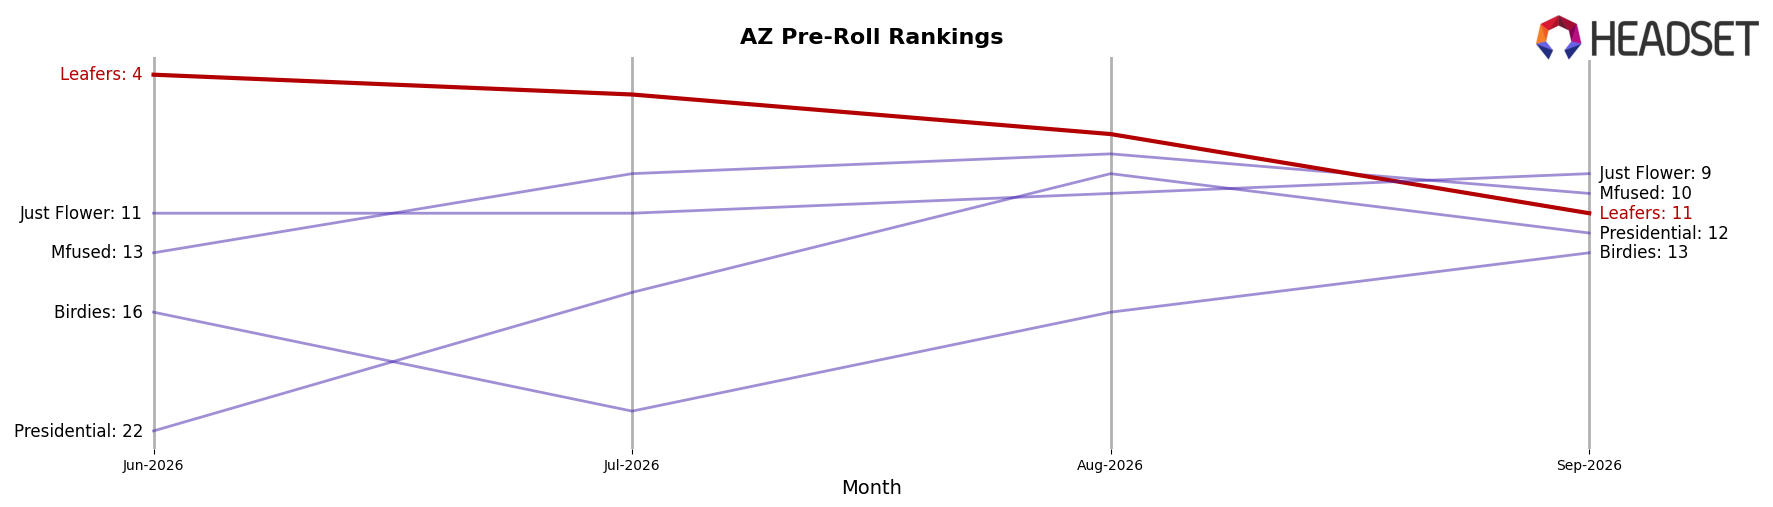
Leafers sits at rank #11 in AZ Pre-Roll in September 2026, down 7 positions from #4 year over year, and 7 spots below its June 2026 rank of #4, while also trailing its historical peak of #3 from March 2025; in contrast, Jeeter held #1 both this year and last (rank #1 to #1) with sales up 16.8% year over year, and STIIIZY stayed at #2 (rank #2 to #2) despite a 20.3% YoY sales decline, indicating stalemates at the top even as Anthem surged from #39 to #4 with an 851.7% YoY sales lift; meanwhile Dusties advanced to #3 with a 187.4% YoY increase as Tumble edged from #6 to #5 on 18.4% YoY growth, implying Leafers’ slide from #4 to #11 is less about broad market contraction and more about being displaced by faster-advancing mid-pack rivals.
Notable Products
Indica Blend Infused Live Resin Diamond Pre-Roll 3-Pack (1.5g) led with the steepest drop at -50.9% month over month while holding rank 1, and Sativa Blend Live Resin Diamond Infused Pre-Roll (1g) fell -12.7% at rank 5. In contrast, OG Kush Blend Live Resin Diamond Infused Pre-Roll 3-Pack (1.5g) rose 15.8% at rank 2 while Sativa Blend Live Resin Diamond Infused Pre-Roll 3-Pack (1.5g) was essentially flat at +0.05% at rank 3. With all top 10 SKUs in Pre-Roll and four 3-Pack formats clustered in the top 4, the mix points to reliance on multi-pack pre-rolls even as the top SKU contracts, implying a trade-up to value multi-packs rather than single-stick formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

