


Where to Buy
The Pharm is stocked at 64 licensed dispensaries across Arizona, with the deepest coverage in Phoenix, Tucson, Mesa, El Mirage, and Glendale. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
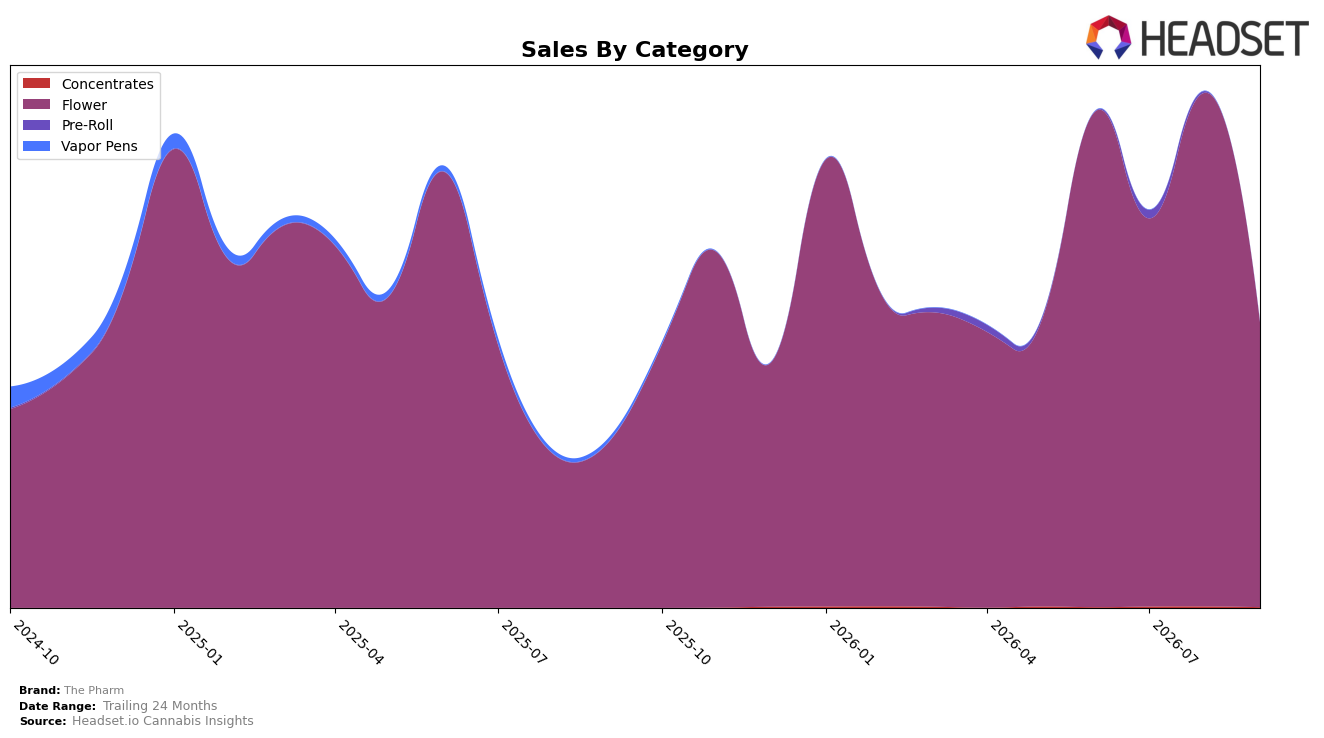
The Pharm concentrated 99.61% of September 2026 sales in Flower, with Concentrates at 0.26% and Pre-Roll at 0.12%, indicating a narrowly focused mix; within that, Flower grew 72.83% year over year while dropping 44.56% month over month, and Pre-Roll spiked 908.85% year over year while falling 71.50% month over month. Average price rose 75.03% year over year to $23.68 while the Flower average price sat at $23.86, and Concentrates declined 49.32% month over month alongside Pre-Roll’s 71.50% month-over-month decline; together, the divergent YoY/MoM signals imply a demand base expanding on an annual horizon but sensitive to recent price or promotional shifts that compressed near-term volumes.
With a 99.61% sales share in Flower and a rank of 10 in Flower in Arizona, the brand’s heavy concentration raises vulnerability to category cyclicality even as brand-level sales climbed 69.79% year over year. The combination of a 44.56% month-over-month contraction in Flower and a 75.03% year-over-year price increase suggests price-led mix and ticket expansion drove annual gains while near-term price elasticity or inventory cadence curtailed recent sell-through; positioning therefore skews toward premiumized Flower that can sustain share at current ranks but risks further rank pressure if price remains elevated relative to month-to-month demand.
Competitive Landscape
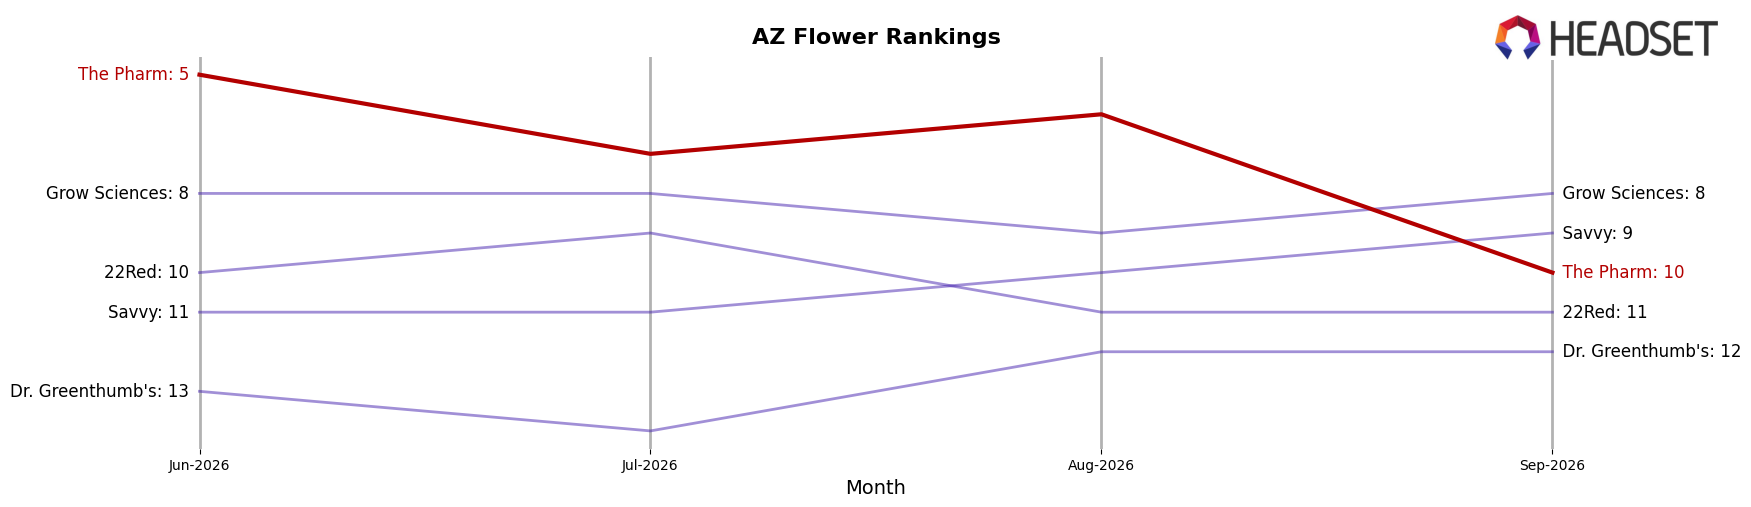
The Pharm sits at rank #10 in Arizona Flower for September 2026, improving 7 positions from #17 year over year, yet slipping 5 ranks from #5 in June 2026 to #10 by September 2026; meanwhile, Just Flower held #1 year over year and remains #1 currently, and Find. advanced from #3 to #2 as Loud Pax surged from #51 to #5 with a 2181.5% YoY sales increase, outpacing The Pharm’s three-month slide from #5 to #10; this pattern implies The Pharm’s YoY climb is being offset by rapid share consolidation among top-five movers, making sustained top-10 retention contingent on countering competitors’ faster rank gains.
Notable Products
GMO (14g) posted the steepest decline in September 2026, down 21.7% month over month while sitting at rank 2, and its $78,588 tally contrasts with Cheddar Mints (4g) holding rank 1 despite no reported month-over-month figure. With four of the top ten in 14g formats and six of the top ten concentrated in Flower ranks 1–6, TK Skunk (14g) at rank 3 underscores the weight of large-format Flower in the upper tier. The pattern implies The Pharm is consolidating share around high-rank 14g Flower SKUs even as a key volume driver like GMO (14g) softens, suggesting a portfolio tilt toward fewer, heavier-weight winners.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

