

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
NEXT is stocked at 19 licensed dispensaries across New York, with the deepest coverage in Rochester, Brooklyn, Buffalo, New York, and Albany. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
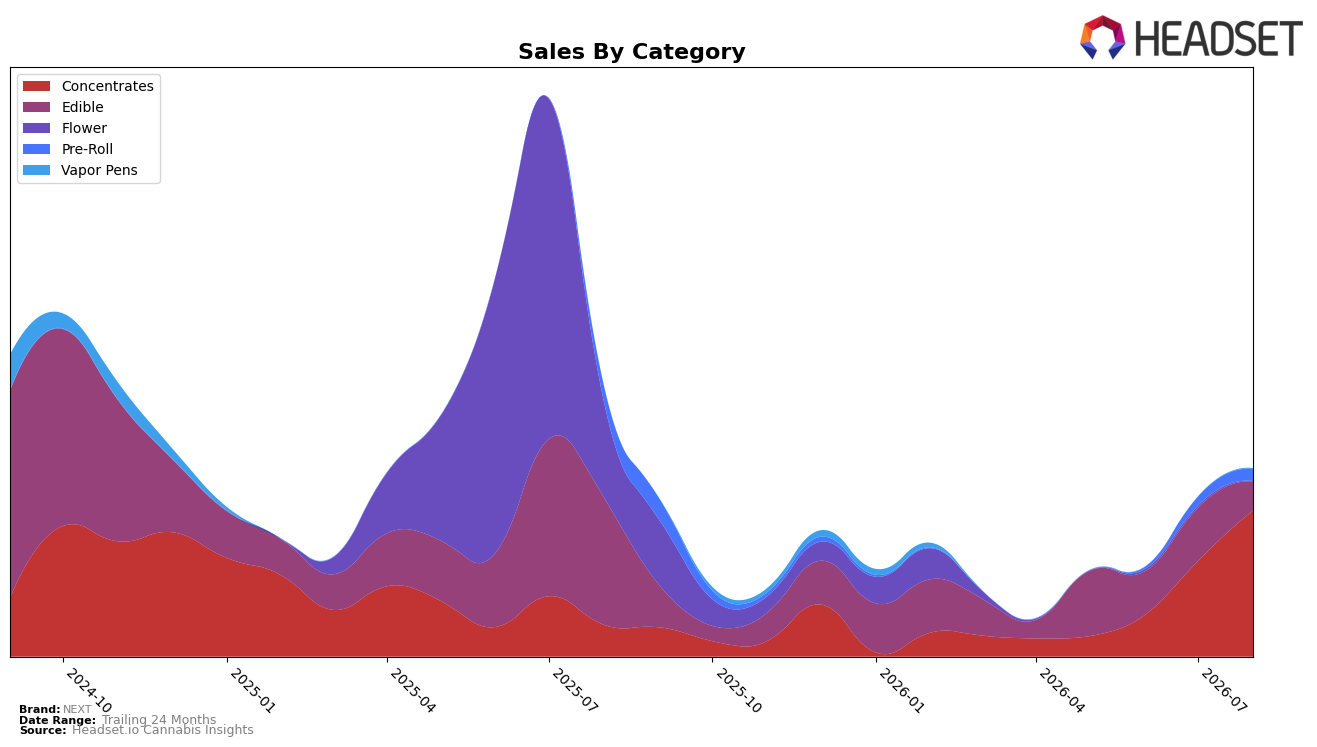
Concentrates now account for 78.05% share with a 362.27% year-over-year surge and 53.23% month-over-month lift, while Edible has fallen to 15.33% share with a 77.41% YoY decline and a 45.84% MoM drop; Pre-Roll holds 6.16% share with a 26.42% YoY decline but a 31.42% MoM rebound, and Vapor Pens sits at 0.46% share with insufficient trend data. Despite overall brand sales down 30.60% YoY and average price up 27.19%, NEXT’s category footprint is concentrating into higher-priced Concentrates at a state rank of 46 in Concentrates for New York, which implies a pivot away from Edible and a tactical bet on potency-led baskets.
The pivot toward Concentrates at 78.05% share alongside a 53.23% MoM gain, contrasted with Edible’s 45.84% MoM contraction and 77.41% YoY slide, indicates a deliberate mix shift favoring higher ticket items despite total brand sales falling 30.60% YoY. With Pre-Roll improving 31.42% MoM yet still down 26.42% YoY, and a Concentrates rank position of 46 in New York, the pattern implies NEXT is trading breadth for depth: prioritizing a premiumized Concentrates identity to stabilize volumes at higher price points while accepting reduced exposure in Edible and limited presence in Vapor Pens.
Competitive Landscape
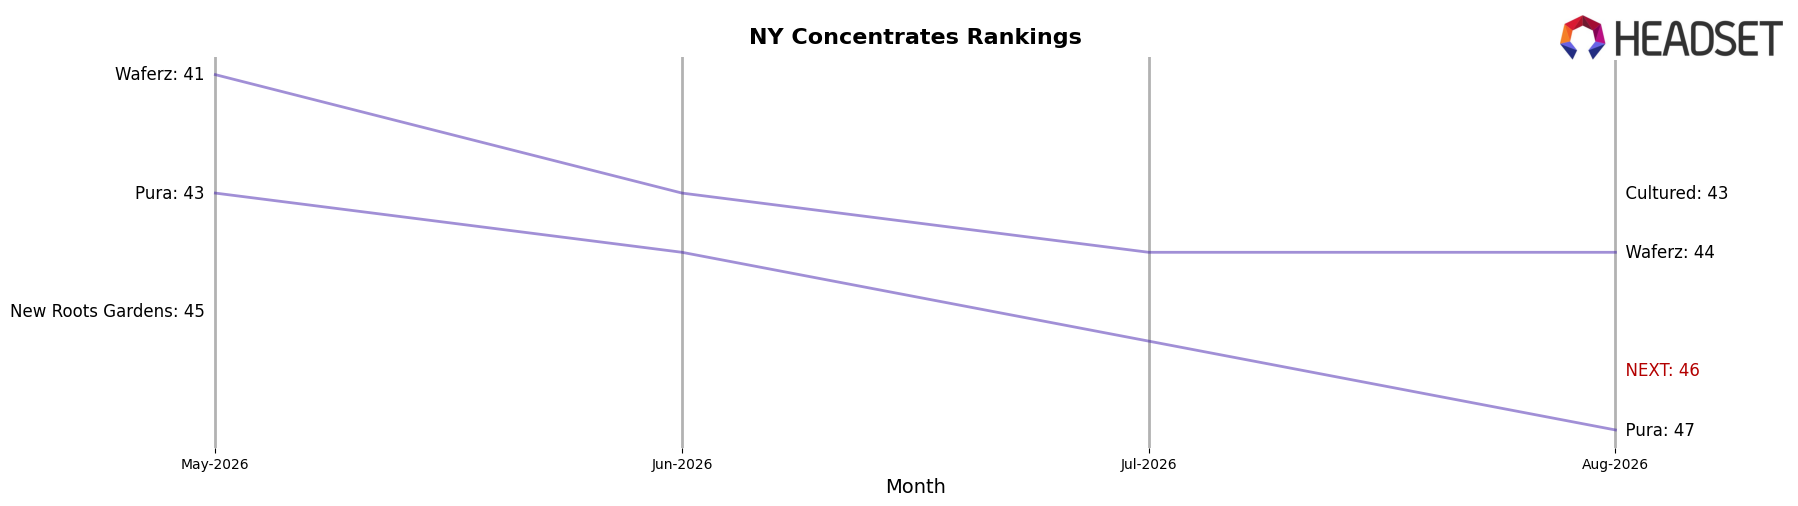
NEXT sits at rank #46 in New York Concentrates in August 2026, improving 4 positions from #50 year over year and jumping 27 spots from #73 over the past three months, while still trailing its peak of #25 from October 2024; meanwhile, Mfny (Marijuana Farms New York) held steady at #1 with a 42.4% YoY sales lift and UMAMII surged from #33 to #3 alongside a 3,294.5% YoY sales increase, indicating NEXT’s mid-pack ascent is due to consistent rank gains rather than outsized velocity and that maintaining double-digit laddering will require closing the gap with top-three climbers.
Notable Products
Sour Diesel Live Resin (1g) delivered the headline move in August 2026 with a 486% month-over-month surge and a jump to rank 1, indicating a demand pivot toward high-potency concentrates. Runtz Live Resin (1g) fell 21% MoM while holding rank 3, and Mango Nectar Bites Gummies 10-Pack (100mg) declined 52% MoM at rank 5, together signaling a rotation away from edibles. Two of the top six SKUs are Edibles while three are Concentrates, and Concentrates include two of the top three ranks, pointing to a portfolio weighting that is concentrating around extracts rather than sweets. The mix implies NEXT is tilting its commercial focus toward Live Resin-led potency segments, with gummies playing a secondary, price-sensitive role.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

